
DICK'S Sporting Goods (DKS) Stock May Be A Bargain On Dividend Pressure
DICK'S Sporting Goods has seen its share price fall sharply over the past year, and fresh headlines around its dividend sustainability and a securities lawsuit have put the focus squarely on what investors are paying for its earnings today. With the stock last closing at US$134.63, the real issue for you is whether that price still lines up with what the business is currently earning.
- The share price has declined 38.2% over the past 12 months, which makes the current earnings based valuation more sensitive to any change in how durable those profits look.
- Recent reports of thinning free cash flow linked to the Foot Locker deal, halted buybacks and expected margin pressure may shape how much value investors ascribe to DICK'S future earnings stream.
- The analysts covering DICK'S Sporting Goods have run their own numbers. See what analysts think DICK'S Sporting Goods's shares could be worth.
The issue now is whether DICK'S Sporting Goods' current share price is justified by the earnings power that the business is producing today.
If you want a broader earnings based watchlist while you study DICK'S Sporting Goods, a focused stock screen can help you spot 27 high quality undervalued stocks as a starting point for deeper research.
Does DICK'S Sporting Goods Look Undervalued on Earnings?
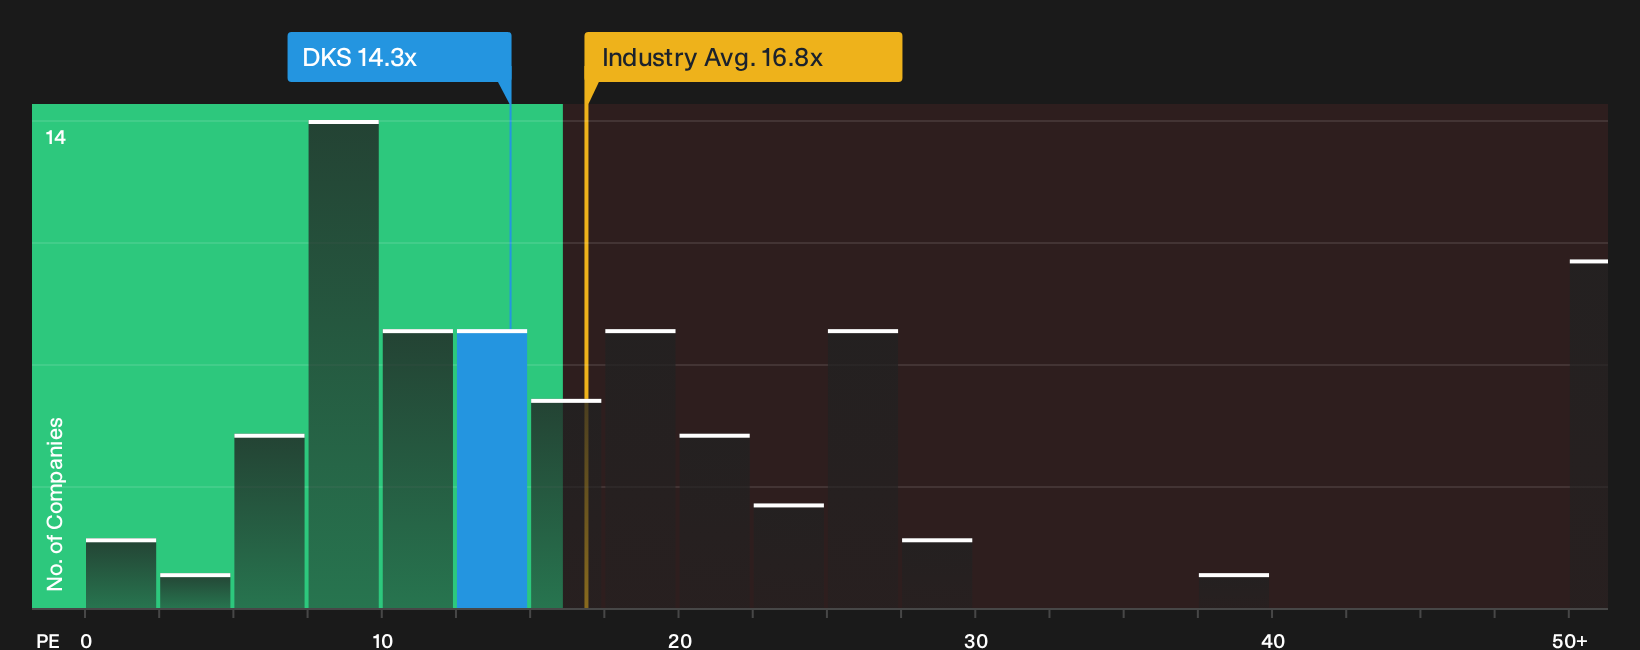
The P/E ratio is a useful lens for DICK'S Sporting Goods because earnings still sit at the center of how investors judge this retailer. At the current price, the stock trades on roughly 14.3x earnings, which sits below both the Specialty Retail industry average of about 16.8x and a broader peer group closer to 20.9x.
That gap persists even though recent headlines around the securities lawsuit and pressure on free cash flow have already cooled sentiment. The lower P/E multiple suggests the market is applying a clear discount to DICK'S Sporting Goods compared with what similar retailers fetch. On a tailored yardstick that adjusts for the company’s growth profile, profitability, size and risks, the current P/E also screens below where you might expect it to land, which points to the shares looking undervalued on this metric. Explore the numbers behind DICK'S Sporting Goods's P/E valuation.
The DICK'S Sporting Goods Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the P/E puzzle for DICK'S Sporting Goods' stock leaves off, by explaining which paths for growth, margins and earnings would need to occur for the current valuation to appear either too low or too rich. Each narrative treats fair value as a thesis about how DICK'S Sporting Goods' business might evolve that you can track over time, rather than just a static snapshot.
Community views on DICK'S Sporting Goods split between those who see the current price discounting too much Foot Locker risk and those who think recent execution raises fresh questions.
Bull case: 15% undervalued
"The current valuation suggests that the market is heavily discounting the Foot Locker risks and the recent guidance cuts, and is not fully recognizing DICK'S Sporting Goods for the contribution from high-ROI store formats, ancillary platforms, and the potential benefits of the combined athletic footwear ecosystem..."
Discover why this Narrative puts DICK'S Sporting Goods at 15% undervalued.
Bear case: 19% overvalued
"The Foot Locker "inflection point" has been deferred, full-year Foot Locker pro forma comp guidance moved from 1.5% to 3% growth to 2% to flat, the operating income expectation shifted from a profit of $110M to $150M to a loss of $40M to $80M..."
Explore why this Narrative puts DICK'S Sporting Goods at 19% overvalued.
DICK'S Sporting Goods: why the price is only half the story
Even if DICK'S Sporting Goods looks interesting at today’s multiple, the real test is whether you are comfortable with the other risks our checks highlight, which sit outside the valuation itself. Take a closer look at 4 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com