
Nuclear Power Deal Might Change The Case For Investing In Google (GOOGL)
- Alphabet’s Google has agreed a 20 year, US$4.3 billion nuclear power purchase with Constellation Energy to secure 890 megawatts of new carbon free capacity and 3,590 megawatts of contracted electricity for its AI and cloud data centers on the PJM grid.
- The long dated deal hardwires energy costs and power availability into Alphabet’s AI and Google Cloud build out, tying data center economics directly to nuclear-backed, round the clock supply at a time when electricity demand and pricing pressures are rising.
- We will look at how Alphabet's AI heavy investment narrative is reshaped by this 20 year nuclear power commitment for data centers.
Alphabet Investment Narrative Recap
To own Alphabet, you need to believe that heavy AI and data center spending converts into durable demand across Search, YouTube and especially Google Cloud. The big near term swing factor is how quickly that US$514b cloud backlog turns into revenue and cash, given rising energy, depreciation and financing costs tied to AI infrastructure.
The nuclear power deal speaks directly to that tension. It may steady Alphabet’s energy costs for AI data centers, but it does not change the main short term catalyst, which is evidence of profitable Gemini and Cloud uptake. The largest immediate risk remains execution on AI monetisation while free cash flow is already under pressure.
The Google and Unity partnership on an integrated AI gaming platform is the clearest tie in to this AI and power story. It pushes Alphabet’s AI stack deeper into a high engagement use case, with Playground and Unity Spark giving creators more reasons to rely on Google’s models and cloud tools.
For you as an investor, that partnership matters because it is another potential on ramp into the existing AI weighted cloud backlog. Strong execution here could help support Cloud utilisation and margins tied to all that new data center and nuclear backed capacity, while missteps would add to concerns about monetising Alphabet’s escalating AI spend.
What Alphabet’s Forecasts Assume About AI Powering The Business
Alphabet’s current analyst blueprint ties the nuclear backed data center build to a revenue path that targets US$795.9b of sales and US$243.1b of earnings by 2029. This is underpinned by a projected 21.3% annual top line expansion and an earnings move from US$244.1b today to US$243.1b that implies a US$1.0b decline rather than growth.
Those figures sit alongside expectations that overall profit margins compress from 54.8% to 30.5% over the next three years, even as AI infrastructure and long dated power contracts scale up. For you as a shareholder or prospective investor, that mix of higher revenue, lower margin and slightly softer earnings indicates that analysts are effectively assuming that AI and cloud related volume offsets thinner profitability per dollar of sales.
The projected earnings path also hinges on the market paying a richer multiple for Alphabet. The current analyst framework uses a P/E of 28.9x on those 2029 earnings, compared with 17.2x today and 10.0x for the broader US Interactive Media and Services group. That gap matters because it highlights that a sizeable part of the story is about how much investors might be willing to pay for each dollar of Alphabet’s profit if the AI and data center thesis develops in line with these models.
This set of assumptions also includes modest dilution, with analysts expecting the share count to rise by about 1.35% a year for three years. For anyone tracking per share outcomes, that incremental issuance means earnings per share need to work a little harder just to keep pace, let alone exceed headline profit, especially while free cash flow is under strain from AI and power investments.
Uncover how Alphabet's fair value indicates a 23% potential upside to its current price, which could narrow quickly if AI execution convinces more investors.
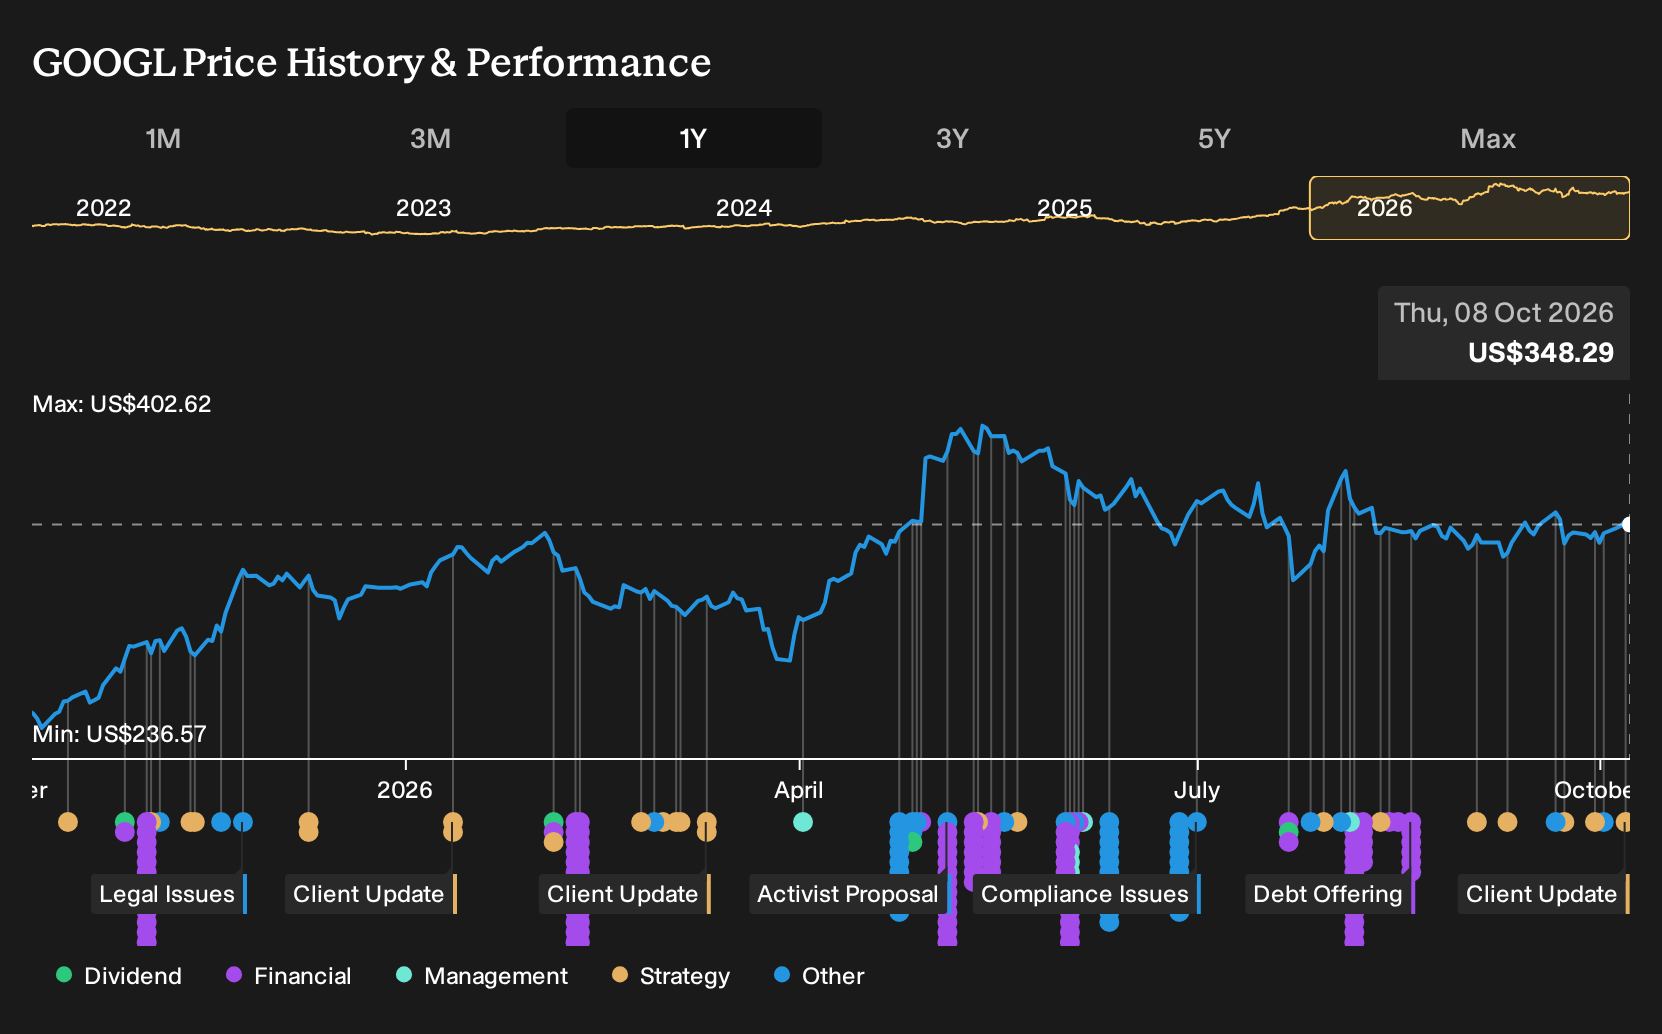
Exploring Other Perspectives
Regulatory risk is where the lowest Alphabet analysts push hardest. They sketch a world where tougher privacy rules and antitrust action bite into ad targeting just as AI power needs surge, and they only pencil in revenue of about US$581.2b and earnings near US$170.1b by 2029. That is more cautious than the consensus view. The new nuclear power deal, plus the Google and Unity gaming partnership, could influence both forecasts. It can be useful to compare several narratives before deciding how this story fits in a portfolio.
Explore 65 other Alphabet fair value estimates, including one that suggests as much as 42% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Alphabet research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Alphabet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alphabet's overall financial health at a glance.
Looking For More Ideas Beyond Alphabet?
If this Alphabet story has sharpened your view on AI, power and long term cash generation, it can be useful to scan for other businesses that line up with your preferred risk and return profile using the Simply Wall St Screener.
- For investors who want potential high growth in smaller companies and are comfortable with volatility, review 10 elite penny stocks with strong financials that already clear a quality and financial strength bar.
- If value and resilience matter more to you, focus on companies trading below estimated worth with robust fundamentals by checking out 27 high quality undervalued stocks.
- When capital protection and balance sheet strength are the priority, filter for financially resilient businesses with prudent leverage and liquidity by using our 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com