
How Investors May Respond To PayPal Stock AI Commerce Push
- PayPal Holdings has been refocusing its business, stabilizing core checkout while pushing into AI driven "agentic commerce" and higher growth areas such as Venmo, Braintree, credit and Buy Now Pay Later, ahead of its upcoming Q3 2026 earnings release.
- The shift toward an AI enabled payments layer and a broader financial services mix highlights how PayPal is trying to offset pressure from lower transaction take rates and intense competition in digital payments.
- The next step is to see how this AI led pivot and financial services expansion may reshape PayPal Holdings' broader investment narrative.
Scan how other payment and fintech stocks are positioned for AI led commerce shifts alongside PayPal Holdings through a curated set of 27 high quality undervalued stocks
PayPal Holdings Investment Narrative Recap
To stay on board as a PayPal Holdings shareholder, you essentially need to believe the shift toward AI driven payments, Venmo, Braintree and broader financial services can more than offset pressure from lower take rates and slower branded checkout. The immediate catalyst is execution on this pivot around the Q3 2026 earnings update, where investors are watching for evidence that core checkout is holding while newer channels scale.
The biggest near term risk is that mix shift and pricing pressure continue to weigh on transaction margin faster than cost savings and AI efficiencies show up, especially with earnings forecasts already pointing to slight declines over the next few years. Recent AI and agentic commerce headlines do not yet change that risk reward balance in a material way until there is clearer operating data.
The clearest announcement that ties back to this setup is PayPal’s plan to repurchase about US$6b of shares in 2026. That decision leans on the firm’s view of its own cash generation and on the idea that the current P/E near 9.6x, which is below peer averages, signals an undervalued equity story while management works through restructuring and technology upgrades.
For you as an investor, that buyback plan mainly interacts with the same catalysts already in focus, namely execution on AI enabled payments, Venmo monetisation and the US$1.5b cost program. If these programs stay on track, the reduced share count can amplify per share metrics, but if take rate pressure or restructuring issues deepen, the repurchases simply reduce flexibility without changing the core operational challenges.
PayPal Holdings' current analyst setup anchors on revenues of US$38.7b and earnings of US$4.7b by 2029. This implies 4.3% yearly revenue growth and an earnings decline of US$0.2b from the US$4.9b recorded today.
Uncover why PayPal Holdings' fair value indicates a 3% potential upside to its current price, which could narrow quickly.
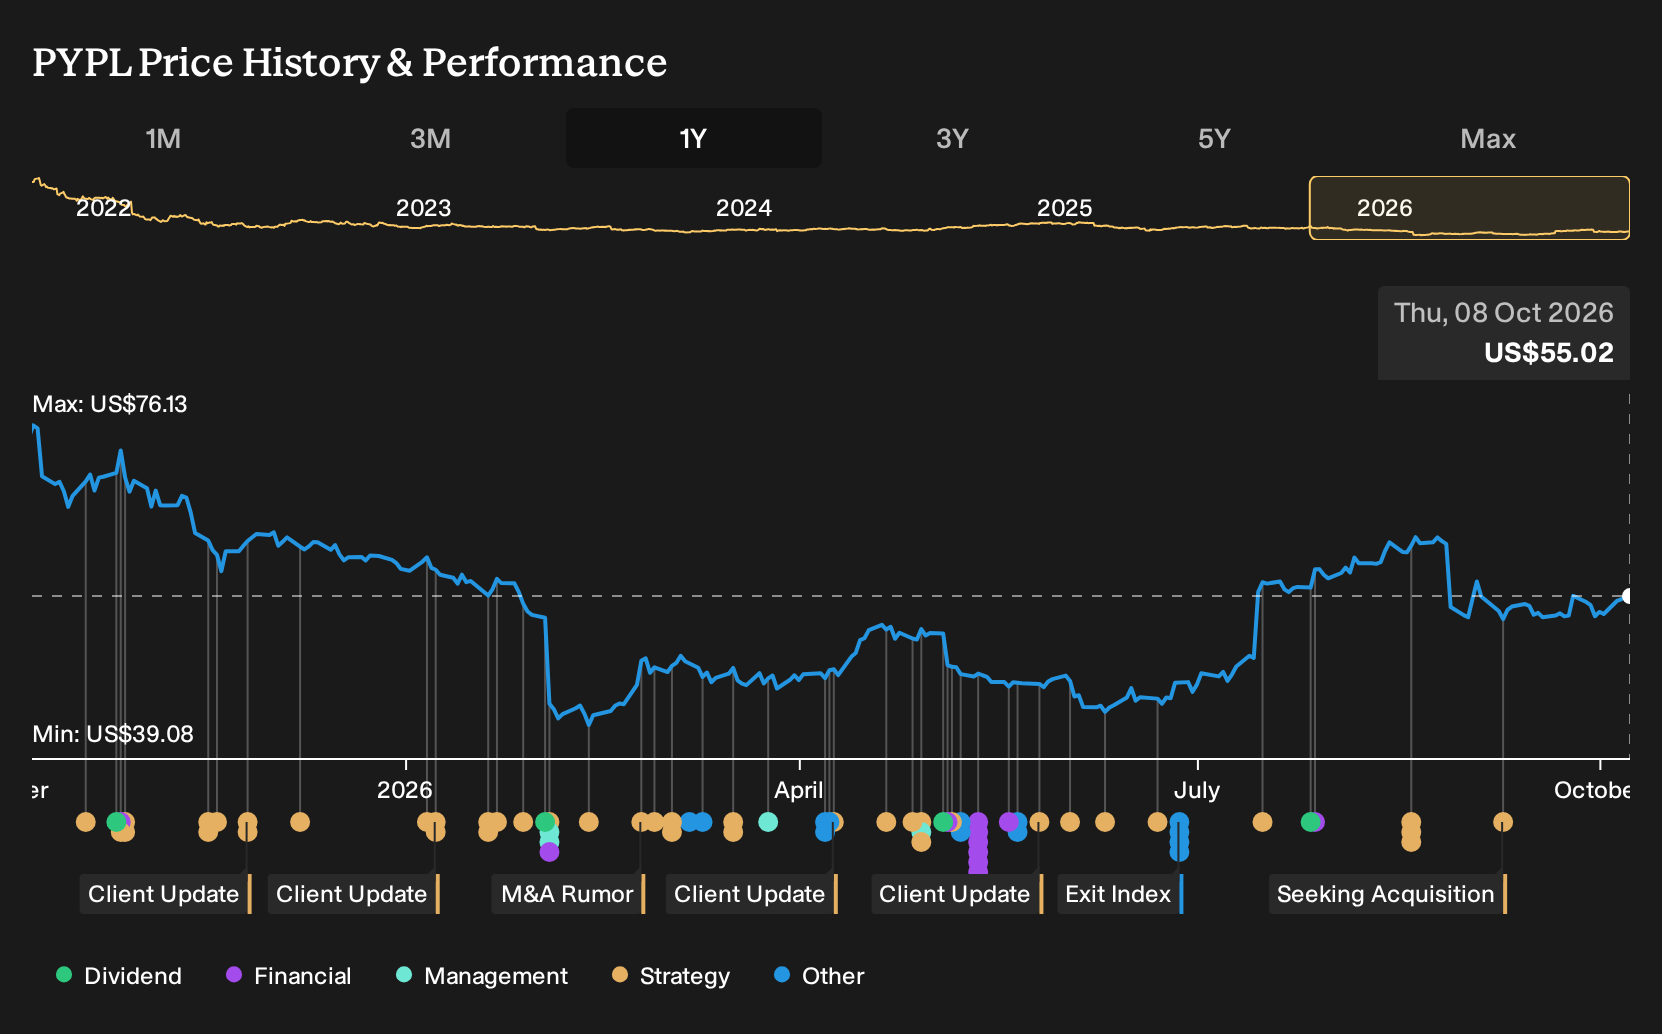
Exploring Other Perspectives
One alternate view puts the take rate pressure at the center of the PayPal Holdings story. The most bearish analysts were pencilling in revenue of about US$37.2b and earnings of US$3.9b by 2029, well below consensus, and argue that heavy AI and agentic commerce spending could keep squeezing profits. These forecasts were set before this week’s AI focused news. You may want to compare how that fresh information could shift both the upbeat and the more pessimistic narratives.
Explore 26 other PayPal Holdings fair value estimates, including one that suggests it could be worth just $56.89.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your PayPal Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PayPal Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review PayPal Holdings' overall financial profile at a glance.
Looking for more investment ideas beyond PayPal Holdings?
If the PayPal Holdings story has sharpened how you think about risk, reward and execution, it can be useful to line it up against other stocks that share some of the qualities you care about. Use the Simply Wall St Screener to spot opportunities that better match your preferences on valuation, balance sheet strength or income potential.
- For investors who want quality and value to work together, scan a curated group of 27 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect them.
- If capital protection matters just as much as upside, check out a 31 resilient stocks with low risk scores that focuses on businesses with stronger financial resilience and lower overall risk scores.
- When you are hunting for underfollowed potential, use a 20 high quality undiscovered gems that highlights financially sound companies which may receive less market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com