
How Investors May Respond To Wendy's (WEN) AI Drive Thru Problems
- Wendy's recently faced public scrutiny after a viral video of its AI operated drive thru highlighted customer frustration and raised questions about current restaurant technology execution.
- The incident puts a spotlight on how Wendy's broader push into AI and digital tools may affect everyday service quality and operating efficiency across the system.
- This article reviews how Wendy's investment narrative is shaped by AI drive thru execution risks and broader restaurant technology spending.
Scan how other restaurant and consumer stocks are handling AI rollouts and customer experience pressure by reviewing the curated 35 profitable AI stocks that aren't just burning cash alongside Wendy's next.
Wendy's Investment Narrative Recap
To own Wendy's, you need to believe the chain can fix U.S. traffic pressure, support franchisee economics, and make its digital and AI spending actually improve throughput instead of creating new headaches. The viral AI drive thru video points to execution risk, but on its own does not appear to change the core near term story.
The bigger swing factor in the coming quarters is whether system optimization, Project Fresh, and digital tools together can stabilise same restaurant sales while commodity and wage costs remain elevated. The main risk remains stressed franchisees facing weaker sales, higher beef inflation, and reduced advertising support at the same time.
The upcoming third quarter 2026 earnings release on 5 November now carries extra weight. Investors get a clean read on how Wendy's is talking about AI deployment after the drive thru incident and whether management adjusts timelines, capital spending, or expectations around automation benefits and customer satisfaction.
Attention will likely sit on commentary about U.S. traffic trends, franchisee health after recent operator issues, and how digital initiatives are affecting restaurant level margins. Any detail on how the AI rollout is being refined, and how that ties into broader technology spending plans, will matter for judging near term execution risk.
Wendy's narrative projects US$2.3b revenue and US$148.4 million earnings by 2029. This assumes revenue growth of 1.9% per year and an earnings increase of about US$22.3 million from current earnings of US$126.1 million.
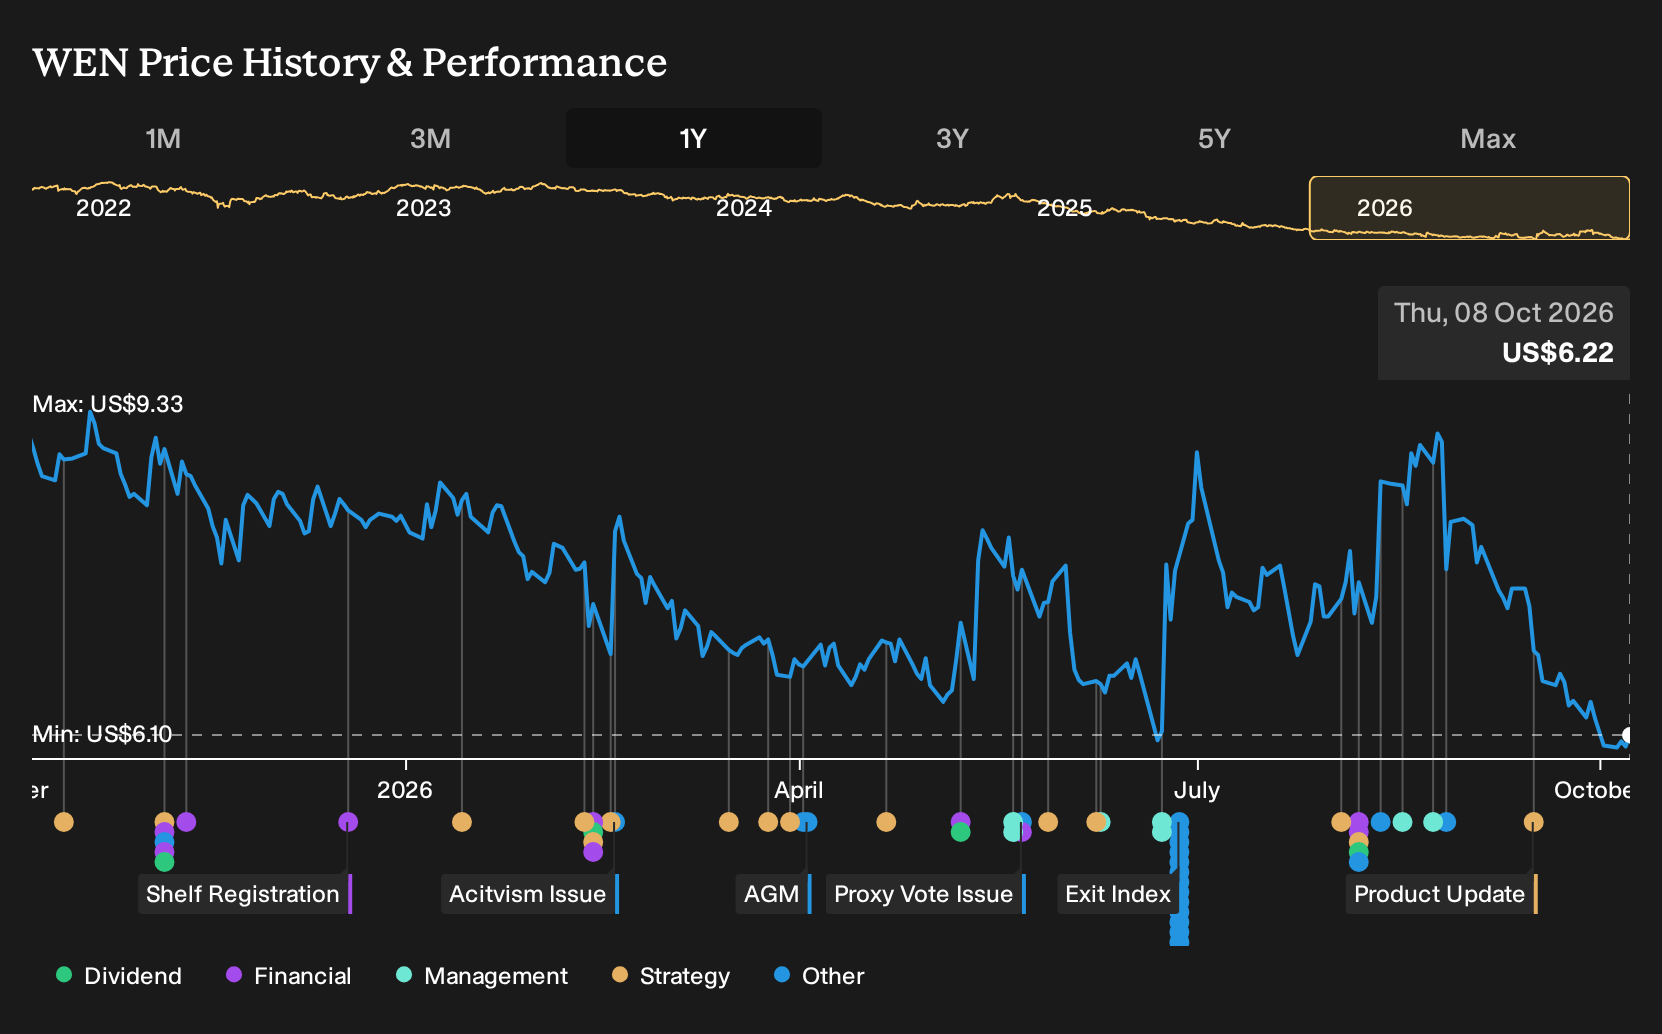
Uncover why Wendy's fair value indicates a 22% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on Wendy's treats AI as a fresh source of earnings risk rather than a fix. The most bearish analysts already modeled revenue of about US$2.2b and earnings near US$97.7 million by 2029, well below consensus. After the viral drive thru clip, those pre event assumptions may shift again. It may be useful to explore both narratives before deciding.
Explore 5 other Wendy's fair value estimates, including one that suggests as much as 20% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Wendy's research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Wendy's. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wendy's overall financial health at a glance.
Looking For More Ideas Beyond Wendy's?
Once you have a view on Wendy's, it can help to compare it with other opportunities that fit different goals such as value, income, or capital protection. The Simply Wall St screener tools provide a quick way to scan for stocks that match the type of risk and reward profile you are comfortable with.
- If you care most about finding strong businesses at appealing prices, scan a curated set of 27 high quality undervalued stocks that combine quality with more modest expectations reflected in their share prices.
- For investors who want income to play a bigger role in returns, focus on companies in the 8 dividend fortresses that offer higher yields and are assessed on payout strength and stability.
- If capital preservation comes first and excitement comes second, start with the 31 resilient stocks with low risk scores that score well on balance sheet strength and smaller historical drawdowns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com