
Is MP Materials (MP) Undervalued As It Expands Rare Earth And Magnet Supply Deals?
Recent progress at MP Materials (MP) on rare earth mining, heavy element processing, and magnet manufacturing, combined with fresh government backed supply deals, has pushed the stock back into focus for investors.
Against that backdrop, MP Materials’ share price has come under pressure, with the stock down 16.7% over the past 30 days and 16.1% year to date, even though the 3 year total shareholder return is up about 1.7x. This suggests recent momentum has faded even as the longer record remains strong.
Explore a curated set of rare earth and critical materials plays that reflect the MP Materials story through the 33 best rare earth metal stocks.
The share price reset now coincides with MP Materials’ heavy spending and government backed contracts. Does that combination still leave enough upside potential to justify the risks at today’s valuation?
Most Popular Narrative: 37% Undervalued
Against a last close of $46.14, the most followed valuation narrative for MP Materials points to a fair value of $73.00, implying a wide gap that depends heavily on execution of long-term contracts and downstream expansion.
The company is expanding its vertically integrated processing and magnet manufacturing capacity with the "10X" plant and a modular recycling facility. Together with significant CapEx support from Apple and the DoD, this is expected to capture more value-added margins and potentially improve net profit and operating leverage as they ramp downstream operations.
See why 200 investors see MP Materials as 37% undervalued.
This widely followed narrative uses a 9.05% discount rate and assumes MP Materials can grow revenue at about 38.9% a year with profit margins eventually reaching 26.6%. Those inputs, along with earnings forecasts through 2029, are what underpin the $73.00 fair value figure and frame the stock as materially undervalued relative to the current share price.
Result: Fair Value of $73.00 (UNDERVALUED)
Still, the MP Materials story can break if the heavy build out of magnet facilities runs into cost overruns, or if key customers like Apple or the DoD pull back or renegotiate.
Find out about the key risks to this MP Materials narrative.
Another View: MP Materials Looks Expensive On Sales
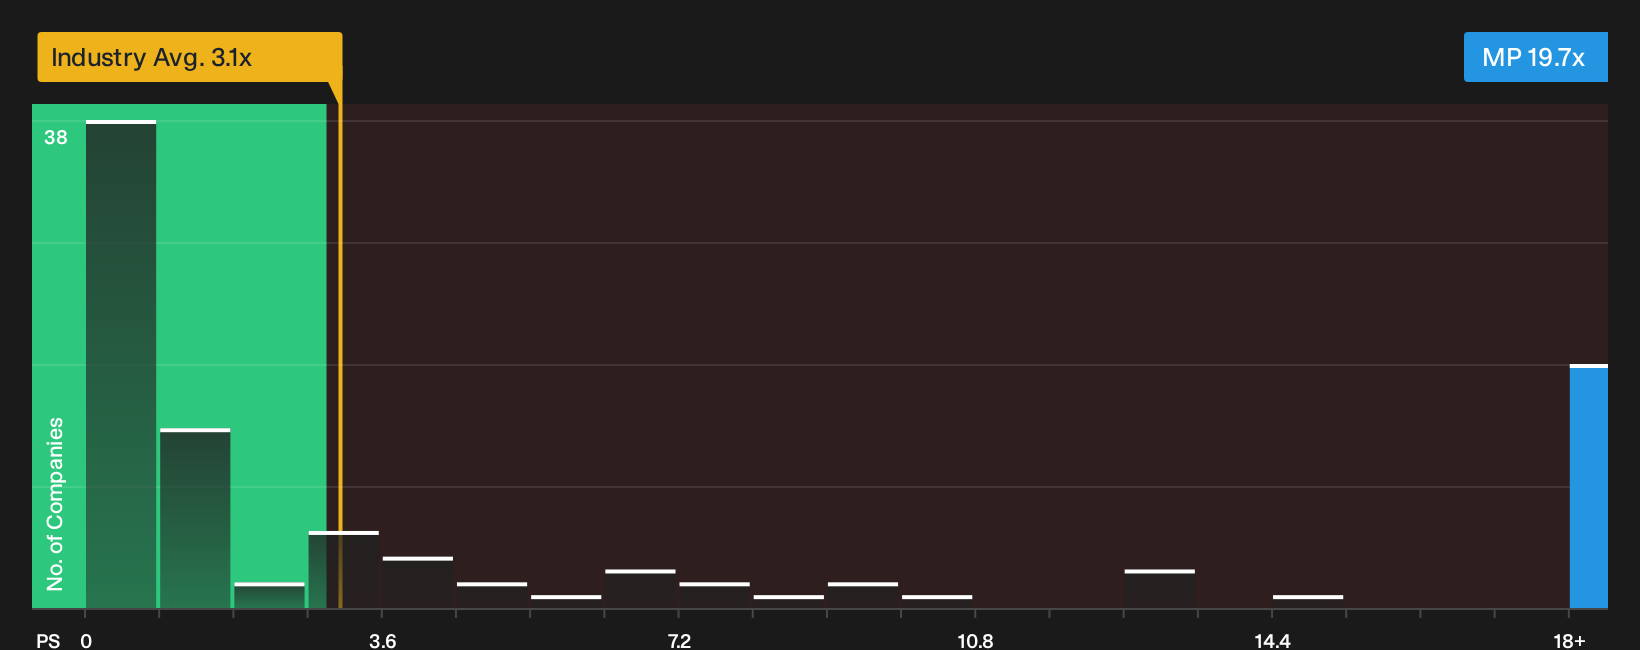
On a simple, sales-based lens, MP Materials screens as richly priced. The stock trades on a P/S ratio of 19.7x compared with 3.1x for the US Metals and Mining industry and 15.5x for peers, while the fair ratio sits much lower at 6.7x. That gap points to meaningful valuation risk if sentiment cools.
Investors who rely more on market-based yardsticks than growth narratives may want to stress-test their thesis against this higher starting point, and ask what would need to go right for today’s multiple to hold up over time.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this piece may sound confident, but the real edge comes from testing the numbers yourself and pressure testing every assumption in context. To judge whether MP Materials’ potential rewards match your own risk tolerance and time horizon, start by reviewing the 2 key rewards.
Looking for more investment ideas beyond MP Materials?
If you stop with MP Materials, you risk missing other setups that fit your style, so line up a few quality options and keep your watchlist working.
- Target potential mispricings by scanning a 27 high quality undervalued stocks that filters for stronger fundamentals at prices that may not fully reflect them yet.
- Build more dependable income streams by focusing on a 8 dividend fortresses that screens for higher yields with supporting balance sheets.
- Sleep easier through rough markets by zeroing in on a 31 resilient stocks with low risk scores designed to highlight companies with more resilient risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com