
Merchants Bancorp (MBIN) Stock May Be Undervalued As Earnings Support Its Price
Merchants Bancorp has rewarded shareholders over recent years, and the valuation conversation now circles around a simple question: Does the current share price fairly reflect what the bank is earning today and what those earnings may support over time?
- Over the past 5 years the stock has returned 89.4%, which puts real weight on whether that climb is in step with the underlying earnings power of the business.
- Merchants Bancorp leans heavily on lending and fee income, so the durability of its net interest margin and credit quality can be crucial to how much of those earnings are available to equity holders.
- Your read on Merchants Bancorp is one view; the desks covering it have another. See what analysts think Merchants Bancorp's shares could be worth.
The issue now is whether the current price of Merchants Bancorp is justified by the level and quality of the earnings investors are paying for.
If you want context on whether Merchants Bancorp’s earnings multiple feels rich or reasonable, it can help to compare it with 27 high quality undervalued stocks.
Is Merchants Bancorp a Bargain on Earnings?
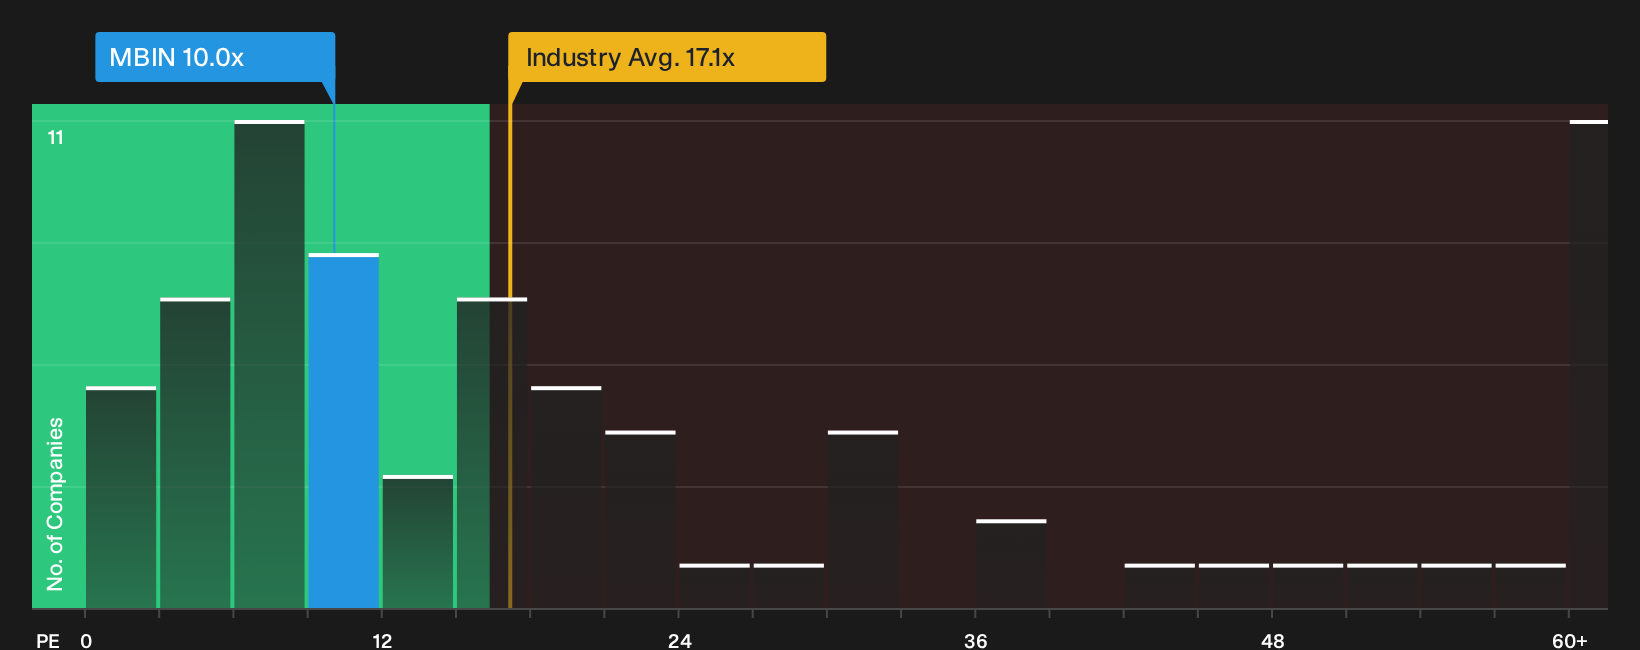
A P/E lens fits Merchants Bancorp because earnings are the key driver for a lender like this. The stock trades around 10.0x its recent earnings, which is below both the Diversified Financial group average of 17.1x and a peer set closer to 14.5x. For an investor comparing options within the sector, that alone flags a lower price tag on each dollar of Merchants Bancorp’s profit.
The fair multiple implied by the valuation model, which blends the company’s profitability profile, risk and size, sits above where the shares currently change hands. That gap suggests the market is applying a discount to Merchants Bancorp’s earnings that is steeper than the model would indicate. Investors may want to consider whether concerns around its lending mix, credit cycle exposure or funding costs justify that gap or leave room for upside over time. Explore the numbers behind Merchants Bancorp's P/E valuation.
The Merchants Bancorp Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E debate leaves off for Merchants Bancorp by spelling out which specific paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s valuation. Each one turns Merchants Bancorp's implied fair value into a thesis about the business that can be revisited over time, and they sit on Simply Wall St's Community page.
A clear, number-driven narrative on Merchants Bancorp gives you a structured way to test your expectations on where its growth, margins and execution go from here. It also creates a reference point that can be checked against future results so you can see whether the original assumptions still hold up or need adjusting.
Share your own Narrative for Merchants Bancorp and set out the assumptions behind your valuation.
Before you move, Merchants Bancorp has one more signal to check
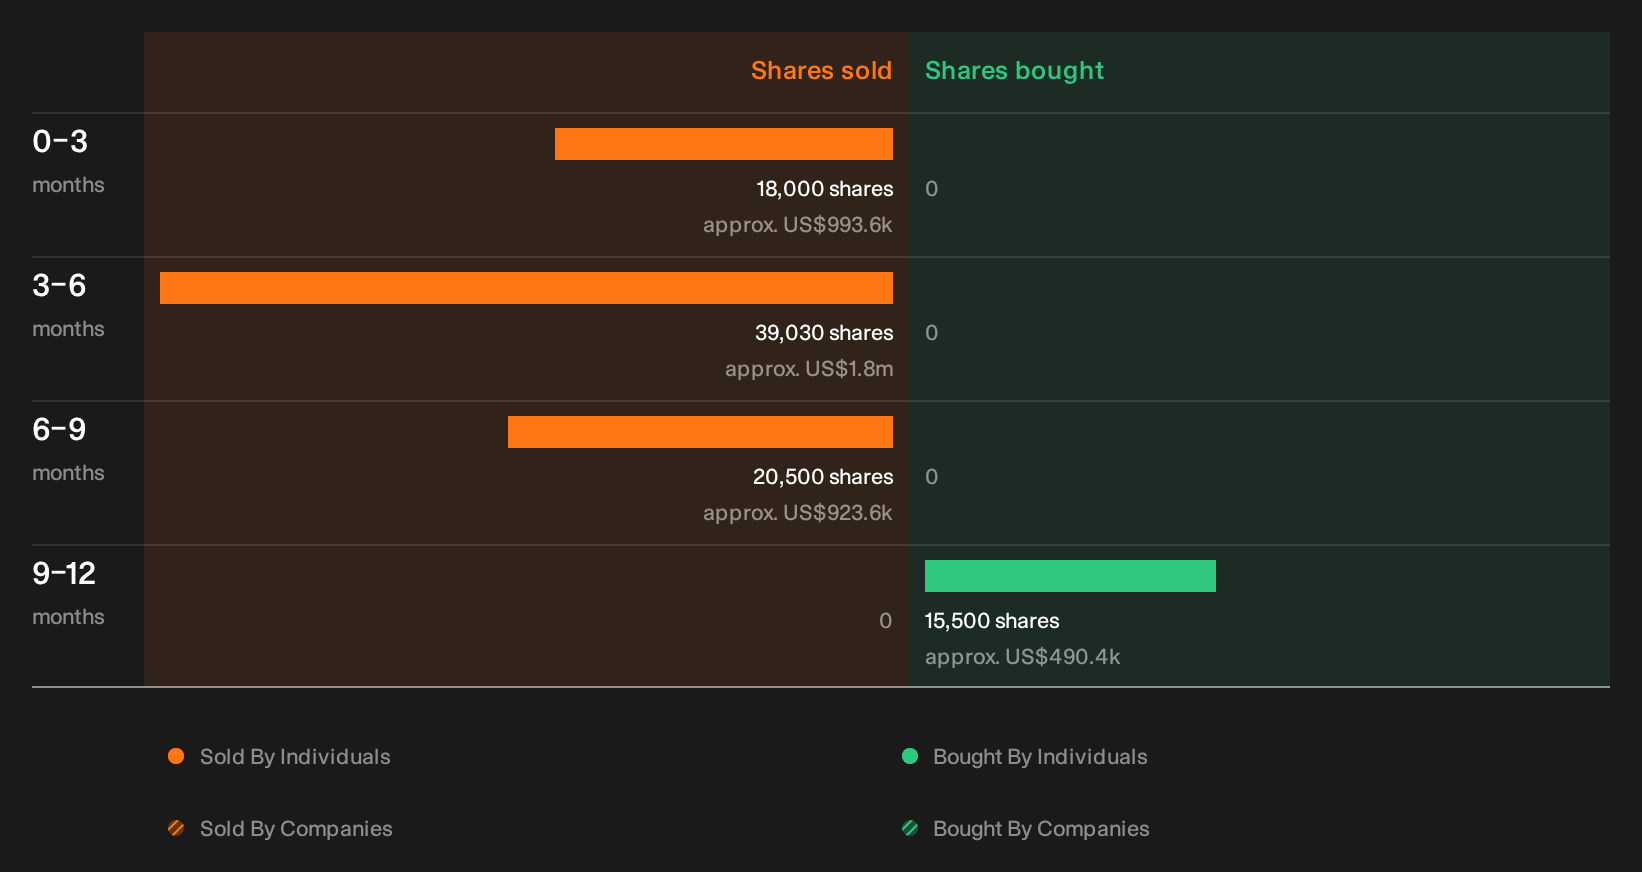
Valuation only tells part of the story for Merchants Bancorp, because recent trades by people inside the business have been flagged by our checks and the who, how much and what it might suggest are still for you to inspect. See the recent insider selling flagged for Merchants Bancorp.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com