
Learn Why The Bull Case For Royal Caribbean Cruises Stock Could Change Following Fleet Expansion
- Royal Caribbean Cruises is shifting from post pandemic repair work to expansion, with management signaling higher capacity and net yield growth on a larger fleet base.
- The combination of expanded ships and elevated capital spending, alongside existing debt, puts more focus on how efficiently new capacity converts into earnings.
- The next area of attention will be how Royal Caribbean Cruises' investment narrative reflects this capacity led earnings push and higher spending.
Scan beyond Royal Caribbean Cruises and compare its capacity driven story with a curated set of travel and leisure operators by reviewing the 27 high quality undervalued stocks that are currently on investors' radar.
Royal Caribbean Cruises Investment Narrative Recap
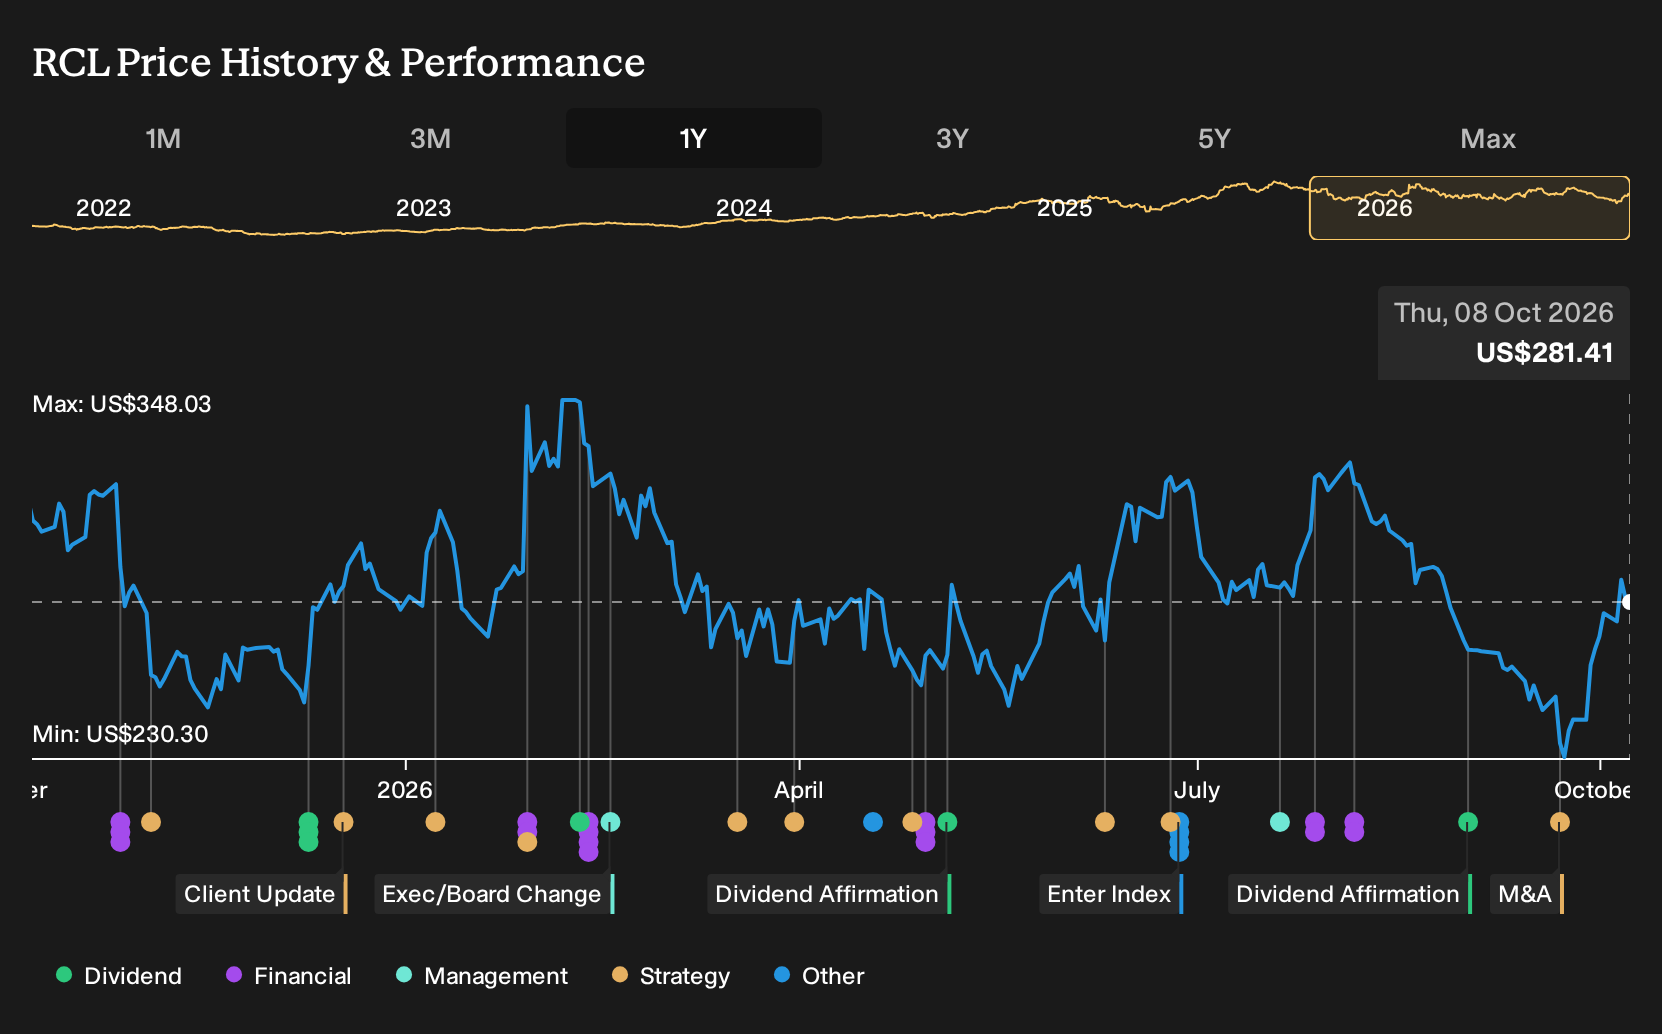
To own Royal Caribbean Cruises, you need to believe that higher capacity, new ships and destination projects can translate into durable earnings on a larger base, despite heavy investment and debt. The near term swing factor is how effectively 2026 capacity and net yield growth show up in revenue and margins, given recent share price volatility.
The biggest operational risk right now is softer demand or pricing, especially in regions like the Mediterranean, colliding with elevated fuel costs and capital spending. If booking trends or onboard spending weaken while leverage remains high and fuel costs stay elevated, that would pressure the earnings story tied to this expansion phase.
Recent commentary around 2026 capacity and net yield growth is directly tied to that thesis. Royal Caribbean Cruises is leaning into a bigger fleet, plus projects like Perfect Day Mexico and Royal Beach Club Cozumel, to support revenue per passenger and onboard spending over the next few years, alongside higher app usage and loyalty driven repeat guests.
Against that, investors are still watching macro sensitivity, fuel exposure and early signs of softer Mediterranean bookings. With valuation metrics currently below some peer and industry averages, the key question is whether upcoming quarters confirm that new ships and higher capacity are earning their keep without eroding financial flexibility.
Royal Caribbean Cruises' current analyst narrative points to revenues of US$24.3b and earnings of US$6.4b by 2029, based on a forecast revenue growth rate of 9.1% a year and an earnings increase of about US$2.0b from US$4.4b today.
Discover how Royal Caribbean Cruises' fair value indicates a 25% potential upside to its current price that could narrow quickly if sentiment becomes more optimistic.
Exploring Other Perspectives
One bearish twist on Royal Caribbean Cruises focuses on passenger cruise day growth staying weak. The lowest analysts were already penciling in slower revenue, at about US$23.6b by 2029, and slightly lower earnings of US$6.2b. Those forecasts, set before this news, show how sharply opinions can differ and why it helps to compare several viewpoints.
Explore 5 other Royal Caribbean Cruises fair value estimates, including one that suggests it could be worth just $275.45.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Royal Caribbean Cruises research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Royal Caribbean Cruises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Royal Caribbean Cruises' overall financial health at a glance.
Looking for more Royal Caribbean Cruises style investment ideas?
If the Royal Caribbean Cruises story has you thinking about what else might fit your portfolio, use this moment to widen the net. The Simply Wall St Screener lets you scan for other stocks with different risk profiles, balance sheet strength, and income potential so you can build a line up that matches your goals rather than just following headlines.
- For steadier profiles that aim to limit downside, start with companies screened for resilience and risk controls through the 31 resilient stocks with low risk scores.
- If quality plus financial strength matters most, filter for businesses with strong fundamentals and cleaner balance sheets by reviewing the list of solid balance sheet and fundamentals (25 results).
- For investors hunting earlier stage opportunities with room to mature, scan the 20 high quality undiscovered gems and see which lesser known stocks meet your criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com