
Discovering 3 Undiscovered Gems in the United Kingdom Market
In the current landscape, the United Kingdom's market has been experiencing fluctuations, with the FTSE 100 index recently closing lower due to weak trade data from China, highlighting global economic interdependencies and their impact on domestic indices. Despite these challenges, investors can find opportunities by identifying stocks that demonstrate resilience and potential for growth in uncertain times.
Top 5 Undiscovered Gems With Strong Fundamentals In The United Kingdom
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Yü Group | 12.20% | 31.64% | 40.36% | ★★★★★☆ |
| LSL Property Services | 40.81% | -14.51% | -16.53% | ★★★★★☆ |
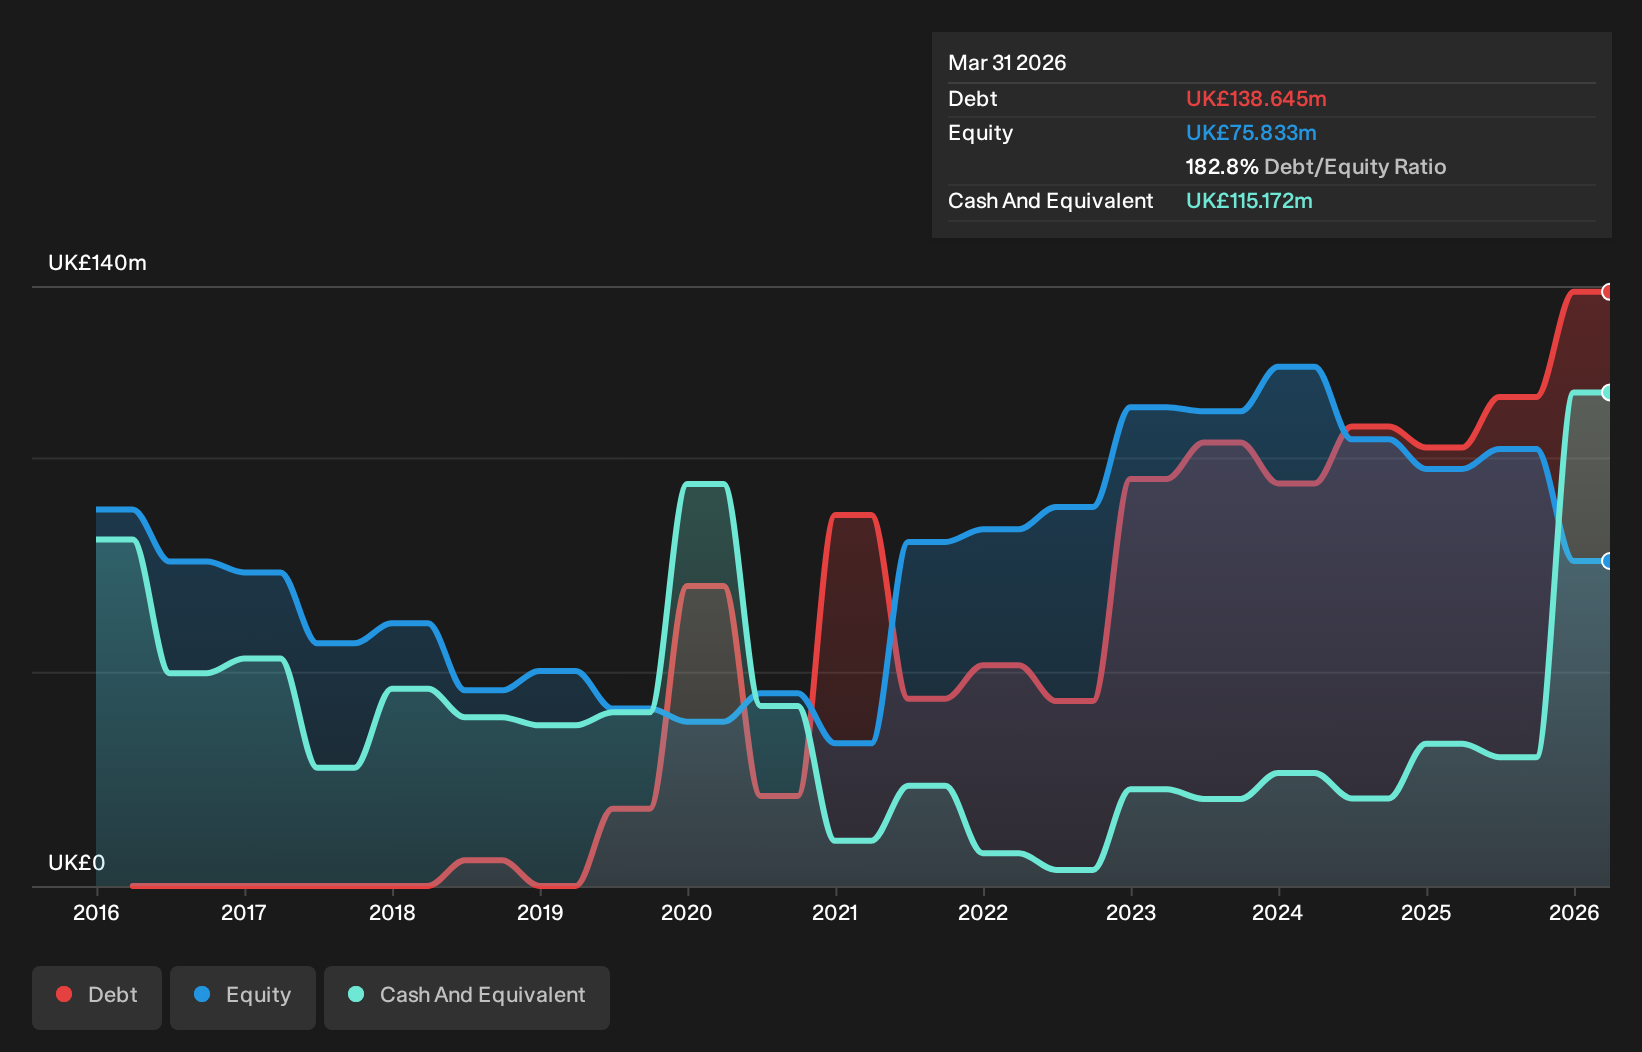
| PayPoint | 182.83% | 21.49% | 0.42% | ★★★★★☆ |
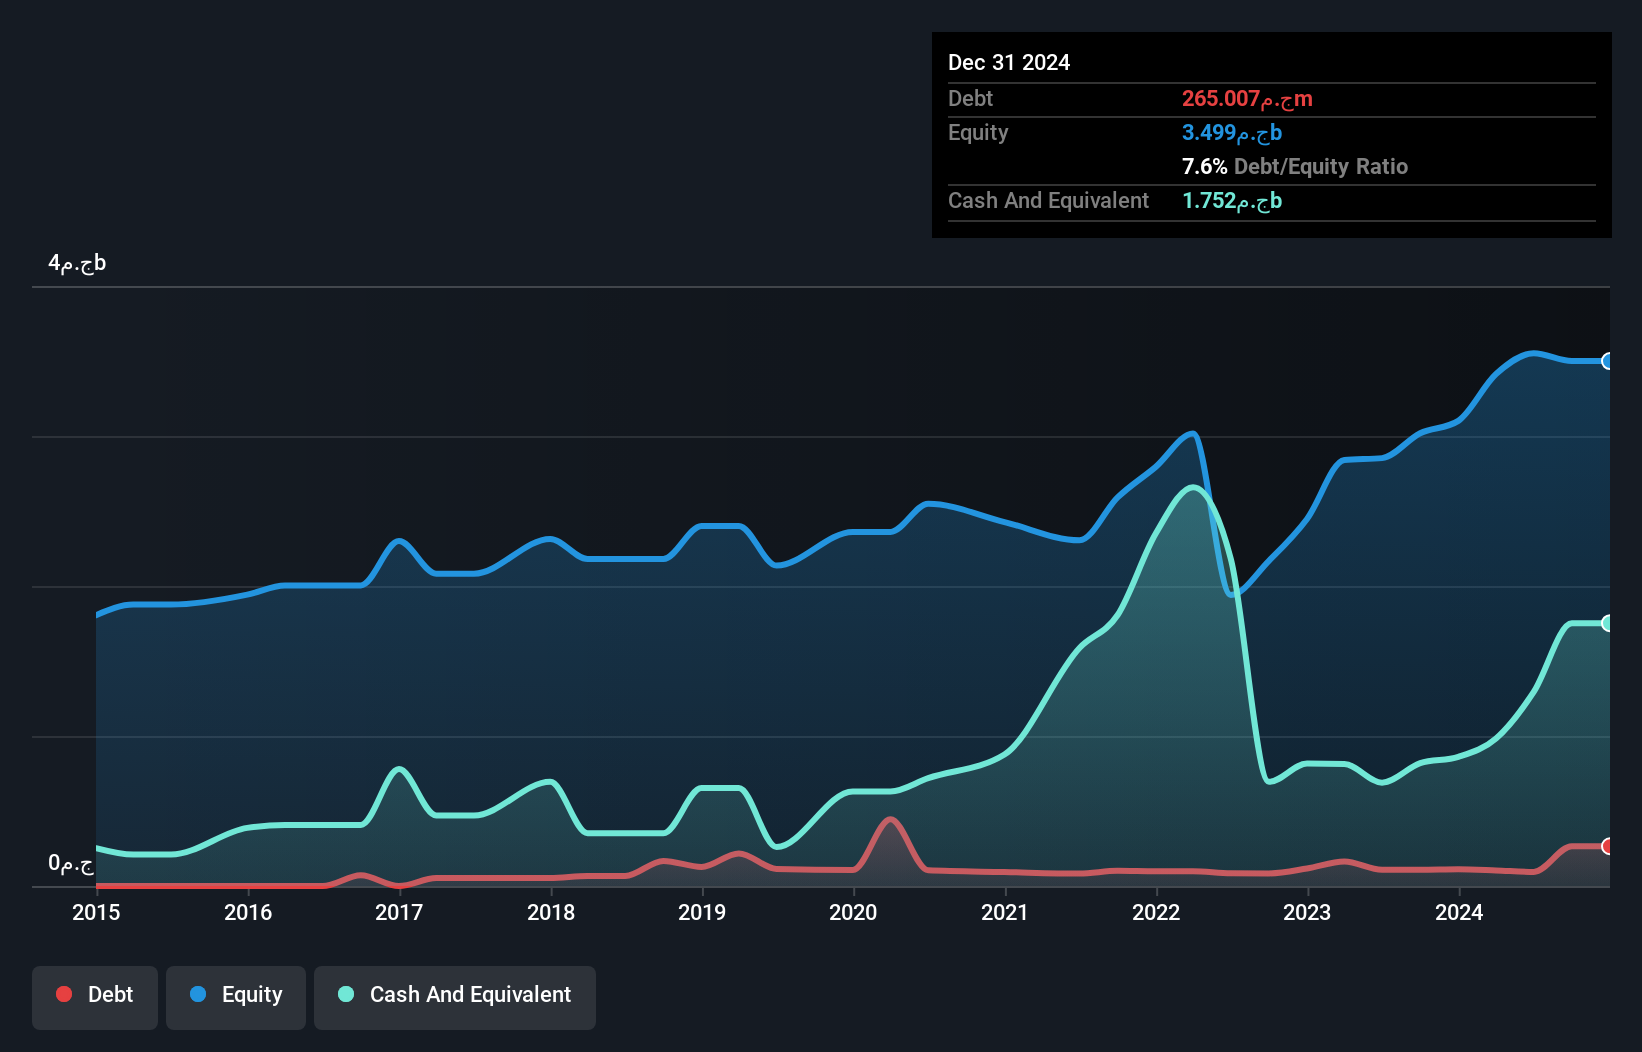
| Integrated Diagnostics Holdings | 7.96% | 15.27% | 4.96% | ★★★★★☆ |
| Distribution Finance Capital Holdings | 15.26% | 36.03% | 48.64% | ★★★★☆☆ |
| ASA International Group | 227.04% | 17.96% | 44.59% | ★★★☆☆☆ |
| Pinewood Technologies Group | 0.10% | -49.10% | -4.03% | ★★★☆☆☆ |
Underneath we present a selection of stocks filtered out by our screen.
ASA International Group (LSE:ASAI)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: ASA International Group PLC operates as a microfinance institution in Asia and Africa, with a market capitalization of £239 million.
Operations: The company generates revenue primarily from its operations in South Asia, East Africa, West Africa, and South East Asia, with notable contributions of $95.38 million from West Africa and $89.01 million from East Africa. It incurs adjustments and eliminations amounting to -$83.30 million in its financial reporting.
ASA International Group, a player in the consumer finance sector, has been making waves with its earnings growth of 44.6% annually over the past five years. Despite trading at 38.7% below its fair value estimate, it faces challenges as its net debt to equity ratio stands high at 164.3%. The company recently reported a half-year net income of US$44.47 million, up from US$27.1 million last year, showcasing robust performance amid industry competition. Additionally, an interim dividend increase of 43% highlights confidence in future profitability despite some financial hurdles like insufficient free cash flow coverage for debt obligations.
- Get an in-depth perspective on ASA International Group's performance by reading our health report here.
Learn about ASA International Group's historical performance.

Integrated Diagnostics Holdings (LSE:IDHC)
Simply Wall St Value Rating: ★★★★★☆
Overview: Integrated Diagnostics Holdings plc is a consumer healthcare company that offers medical diagnostics services to patients and has a market capitalization of $305.20 million.
Operations: IDHC generates revenue primarily from its Contract Segment, which accounts for EGP 6.23 billion, and its Walk-In Segment, contributing EGP 2.94 billion.
Integrated Diagnostics Holdings, a dynamic player in the healthcare sector, has demonstrated robust financial health with earnings growth of 39.5% over the past year, outpacing the industry average of 14.3%. The company is trading at 78.8% below its estimated fair value and boasts high-quality earnings. Impressively, its interest payments are well-covered by EBIT at 77 times coverage, indicating strong operational efficiency. Recent results highlight sales reaching EGP 4.86 billion compared to EGP 3.54 billion last year, while net income rose to EGP 821 million from EGP 551 million previously; basic EPS increased to EGP 1.41 from EGP 0.95.
PayPoint (LSE:PAY)
Simply Wall St Value Rating: ★★★★★☆
Overview: PayPoint plc provides payments and banking, shopping, and e-commerce services in the United Kingdom and New Zealand with a market capitalization of £386.18 million.
Operations: Revenue streams for PayPoint plc primarily include Love2shop and Pay Point, generating £158.23 million and £178.78 million respectively.
PayPoint, a notable player in the UK’s digital payments landscape, is leveraging growth in e-commerce and open banking to diversify its revenue streams. With a net debt to equity ratio of 31%, it stands on solid financial ground. Over the past year, earnings surged by 105%, significantly outpacing the industry average of 14.8%. Despite trading at 38% below estimated fair value, challenges remain with declining traditional retail networks and rising competition from fintechs. Analysts forecast profit margins improving from 12% to 25.6%, though revenue may decrease annually by 13.7% over three years due to market shifts towards cashless transactions.
Key Takeaways
- Dive into all 7 of the UK Undiscovered Gems With Strong Fundamentals we have identified here.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com