
Client Wins Could Be A Game Changer For Thermo Fisher Stock
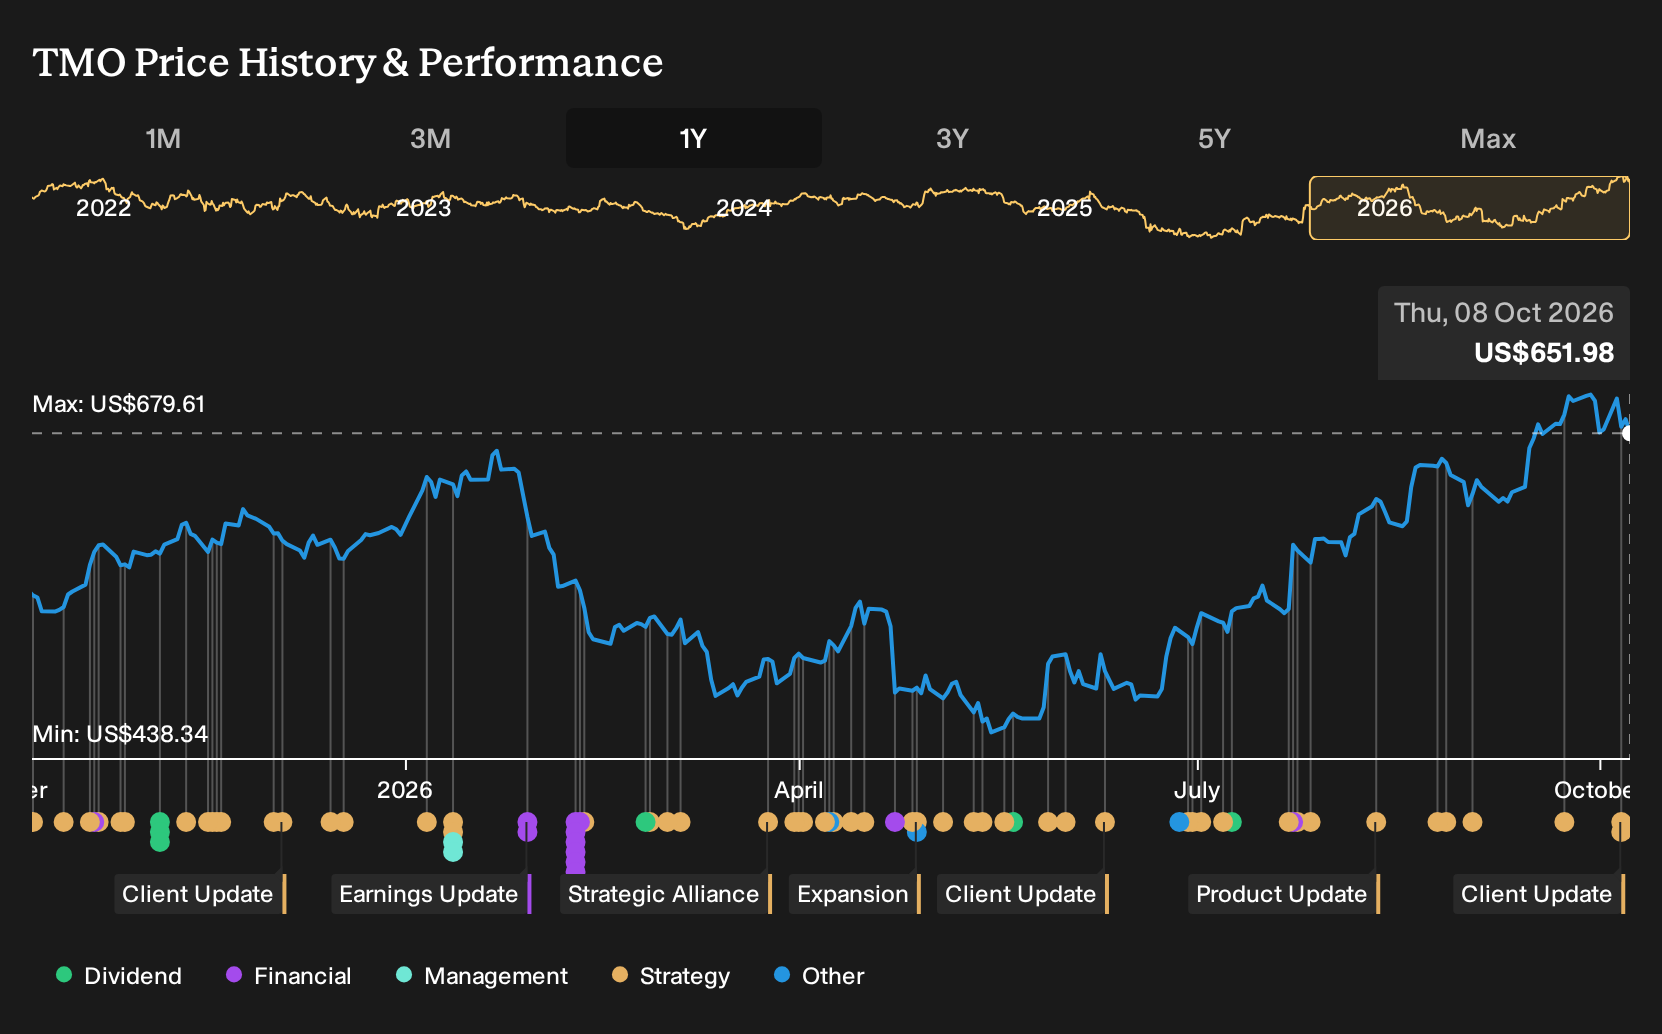
- Quantum BioPharma recently signed a Study Start-Up Agreement with Thermo Fisher Scientific’s clinical research business to run a Phase 2 multiple sclerosis trial, while Thermo Fisher used CPHI Milan 2026 to present new Accelerator Drug Development solutions, OSD Express, Steriles Express offerings, and expanded Gibco media and evidence-generation capabilities.
- The combination of fresh client work in central nervous system research and broader small molecule, sterile, and cell culture platforms highlights how Thermo Fisher Scientific is deepening its role in outsourced drug development workflows rather than relying only on lab instruments and consumables.
- We will look at how Thermo Fisher Scientific's investment narrative is influenced by deeper clinical services exposure through the Lucid-MS Phase 2 collaboration.
Thermo Fisher Scientific Investment Narrative Recap
To own Thermo Fisher Scientific, you need to believe that pharma, biotech and complex lab workflows will keep relying more on outsourced services, data heavy tools and higher value bioproduction rather than just buying stand alone hardware. The Lucid MS trial support fits that view but is small compared with US$46.3b of revenue, so it does not change the near term picture on its own.
The bigger swing factor is still whether funding recovers in more muted academic and government budgets, and whether portfolio changes such as the microbiology divestiture and recent deals translate into the earnings mix that analysts model. High debt levels and expectations for margin expansion remain the key near term risk for Thermo Fisher Scientific.
The CPHI Milan 2026 Accelerator Drug Development announcements are especially important in this context. OSD Express, Steriles Express and the broader Accelerator framework are closely tied to pharma and biotech demand for faster, more integrated development, which is a central part of the existing catalysts around clinical research services and bioproduction.
Those offerings, along with expanded Gibco media and real world evidence initiatives such as the PPD CorEvitas Vitiligo Registry, give Thermo Fisher Scientific more ways to capture volume and data across a program instead of only at the instrument sale. The key operational test is execution and utilization, because if uptake lags, the expected uplift in margins and earnings could fall short of current expectations.
Thermo Fisher Scientific's narrative projects US$54.8b revenue and US$10.0b earnings by 2029. This aligns with analysts assuming 5.8% yearly revenue growth and an earnings increase of US$3.0b from US$7.0b today.
Discover why Thermo Fisher Scientific's fair value appears to be fairly valued at its current price.
Exploring Other Perspectives
One alternate view focuses less on Thermo Fisher Scientific’s clinical services opportunity and more on geopolitical and pricing risk. The most cautious analysts were modelling only US$54.6b of revenue and US$8.9b of earnings by 2029 before this news. That implies tougher assumptions, and it shows how sharply opinions can differ. Consider exploring both narratives as you weigh how deals like Lucid MS and the CPHI launches might reshape expectations.
Explore 3 other Thermo Fisher Scientific fair value estimates, including one that suggests it could be worth just $629.54.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Thermo Fisher Scientific research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Thermo Fisher Scientific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Thermo Fisher Scientific's overall financial health at a glance.
Looking for more investment ideas beyond Thermo Fisher Scientific?
If Thermo Fisher Scientific has sharpened your interest in outsourced science and healthcare platforms, it can help to set up a wider watchlist using the Simply Wall St Screener.
- If you care most about resilient balance sheets and steady fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that can act as potential anchors in a volatile portfolio.
- If upside potential matters more to you than current popularity, filter for 20 high quality undiscovered gems and see which quieter businesses fit your quality thresholds.
- If capital preservation and smoother returns sit higher on your list, focus on 31 resilient stocks with low risk scores that may help reduce overall portfolio swings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com