
Aegon (ENXTAM:AGN) Stock Looks Discounted After Its 119% Five Year Run
Aegon shares have pulled back in recent weeks after a strong multi‑year run, which puts a spotlight on whether the current price still lines up with what the insurer is earning. After that kind of climb and a recent dip, the key issue for investors is how much of Aegon’s earnings power is already embedded in today’s valuation.
- Over the past 5 years the stock has returned 119.0%. As a result, a lot of value has already shifted into the share price and that track record now frames how investors weigh its earnings multiple.
- The recently approved redomiciliation to the US and Omnibus Incentive Plan can influence long term capital allocation, governance and management incentives, which may shape how consistently Aegon converts its insurance operations into earnings available to shareholders.
- The analysts covering Aegon have run their own numbers. See what analysts think Aegon's shares could be worth.
The issue now is whether the current share price is adequately supported by Aegon’s earnings when set against the Fair Ratio benchmark.
If you want to test the same earnings question that hangs over Aegon against a wider field, scan through 180 high quality undervalued stocks.
Does Aegon Look Undervalued on Earnings?
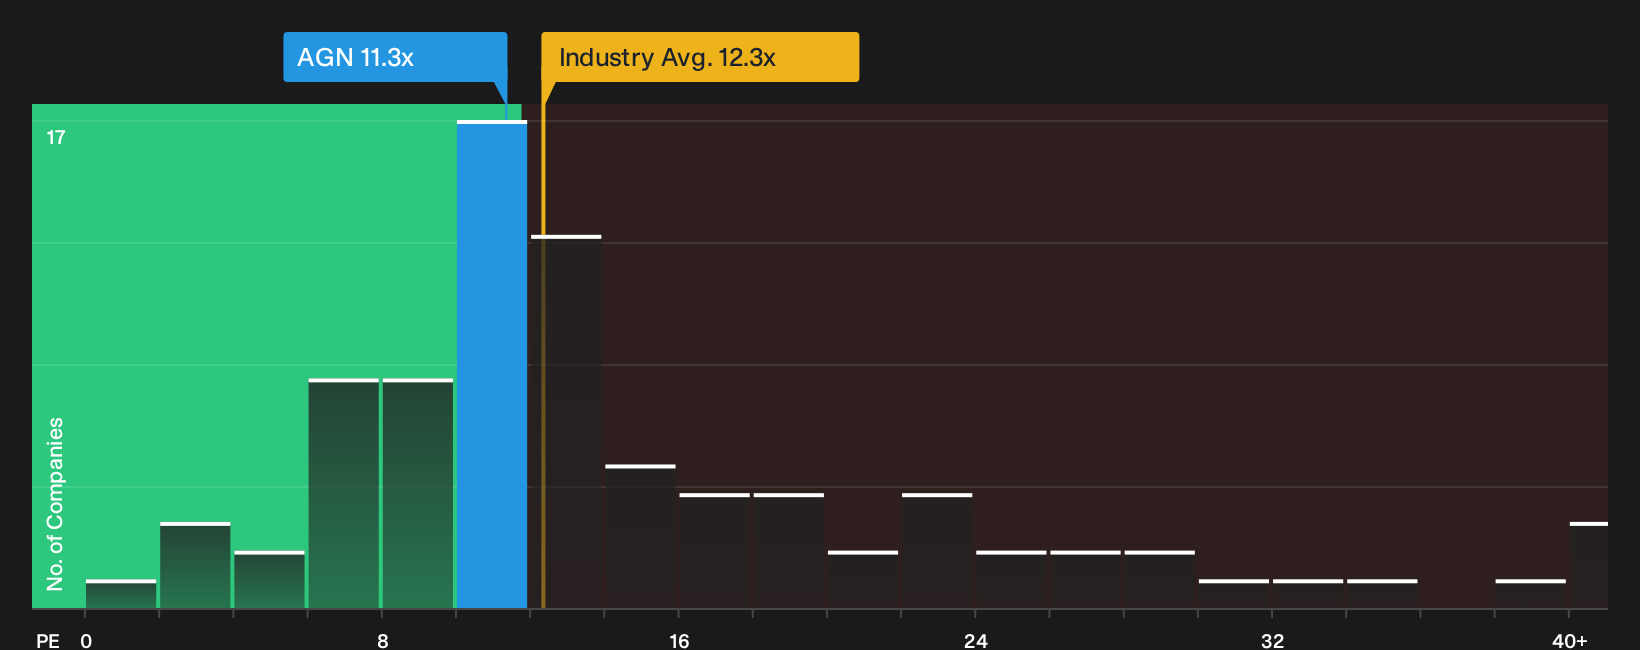
For a mature insurer like Aegon, the P/E ratio gives a direct read on how the market prices its earnings stream. Despite the fresh attention from the approved redomiciliation and Omnibus Incentive Plan, the stock trades on a P/E of about 11.3x, which is close to the wider insurance industry at roughly 11.3x and sits below the peer group near 12.7x.
The Fair Ratio framework, which looks at Aegon’s earnings power in the context of its profitability profile, size and sector risks, points to a higher multiple than the one currently on the screen. That gap means the market is valuing each euro of Aegon’s earnings at a lower level than this tailored benchmark suggests, even though the shares have already rerated over several years. For anyone weighing the pullback against that history, the current earnings multiple may still leave room for a different view on what the business is worth. Explore the numbers behind Aegon's P/E valuation.
The Aegon Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Aegon pick up where the valuation puzzle leaves off by spelling out which paths for Aegon's growth, profitability and earnings would need to play out for the share price to be worth materially more or materially less than it is today, and they sit on the stock's Community page. Each scenario links its number to a clear view on how growth, margins and risk could evolve, which you can then test again as fresh results come through.
Community views on Aegon split between one camp that sees underappreciated earnings power and another that thinks expectations already stretch too far.
Bull case: 9% undervalued
"Ongoing shift toward capital-light, fee-based businesses such as retirement plans, asset management, and alternative fixed income products is likely to increase the stability of revenues..."
Discover why this Narrative puts Aegon at 9% undervalued.
Bear case: 6% overvalued
"Increasing use of reinsurance structures and capital intensive balance sheet actions, such as the SGUL transaction and establishment of a reinsurer, heightens execution and regulatory risk..."
Explore why this Narrative puts Aegon at 6% overvalued.
The share price is only one piece of the Aegon puzzle
Before making up your mind on Aegon, it is worth asking who is actually steering the insurer, what motivates them and how their pay packets line up with your interests. See who runs Aegon and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com