
First Interstate BancSystem (FIBK) Faces A Valuation Test, Is It Still A Bargain?
First Interstate BancSystem (FIBK) drew fresh attention after its recent trading session, with the share price closing at $34.94 as investors weighed mixed short term and longer term return figures.
Recent trading in First Interstate BancSystem has come after a softer patch, with the 30 day share price return down 6.13% and the 90 day share price return down 10.06%. At the same time, the 1 year total shareholder return sits at 17.39% and the 3 year total shareholder return at 74.36%. This points to momentum that has cooled in the short term compared with a stronger multi year run.
Scan how First Interstate BancSystem stacks up against other regional financials by reviewing a hand picked list of solid balance sheet and fundamentals (25 results).
Short term weakness against a stronger three year record puts First Interstate BancSystem in an awkward middle ground. Do you lean into the recent pullback now, or wait for a cleaner valuation setup?
Most Popular Narrative: 13% Undervalued
On the most followed view, First Interstate BancSystem’s recent close at $34.94 sits below a narrative fair value of $40. That gap frames the stock as a value unlock story rather than a short term trading idea.
The real upside over my 3-year horizon is capital appreciation as the market rerates FIBK from an inefficient multi-state bank to a highly profitable, streamlined regional player. (At least that is what I am thinking/hoping will happen.) So far, the predictions my AI assistant and I generated seem to have been fairly accurate. 1) The 11 Nebraska branch sales were completed in Q2, 2) FIBK successfully replaced expensive, non-core brokered deposits and federal debt with a pure, stable localized deposit model, 3) Net Income Margin expanded as per plan to about 3.5%, 4) the big buyback was completed in August, 5) EPS is up to 0.87, and 6) I got the expected dividend which pretty much makes up for the 1% loss in share value since June.
See why 12 investors see First Interstate BancSystem as 13% undervalued.
Result: Fair Value of $40 (UNDERVALUED)
Still, the First Interstate BancSystem narrative could be knocked off course if commercial real estate credit losses spike or if the large securities book continues to pressure tangible book value.
Find out about the key risks to this First Interstate BancSystem narrative.
Another View: What Multiples Say About First Interstate BancSystem
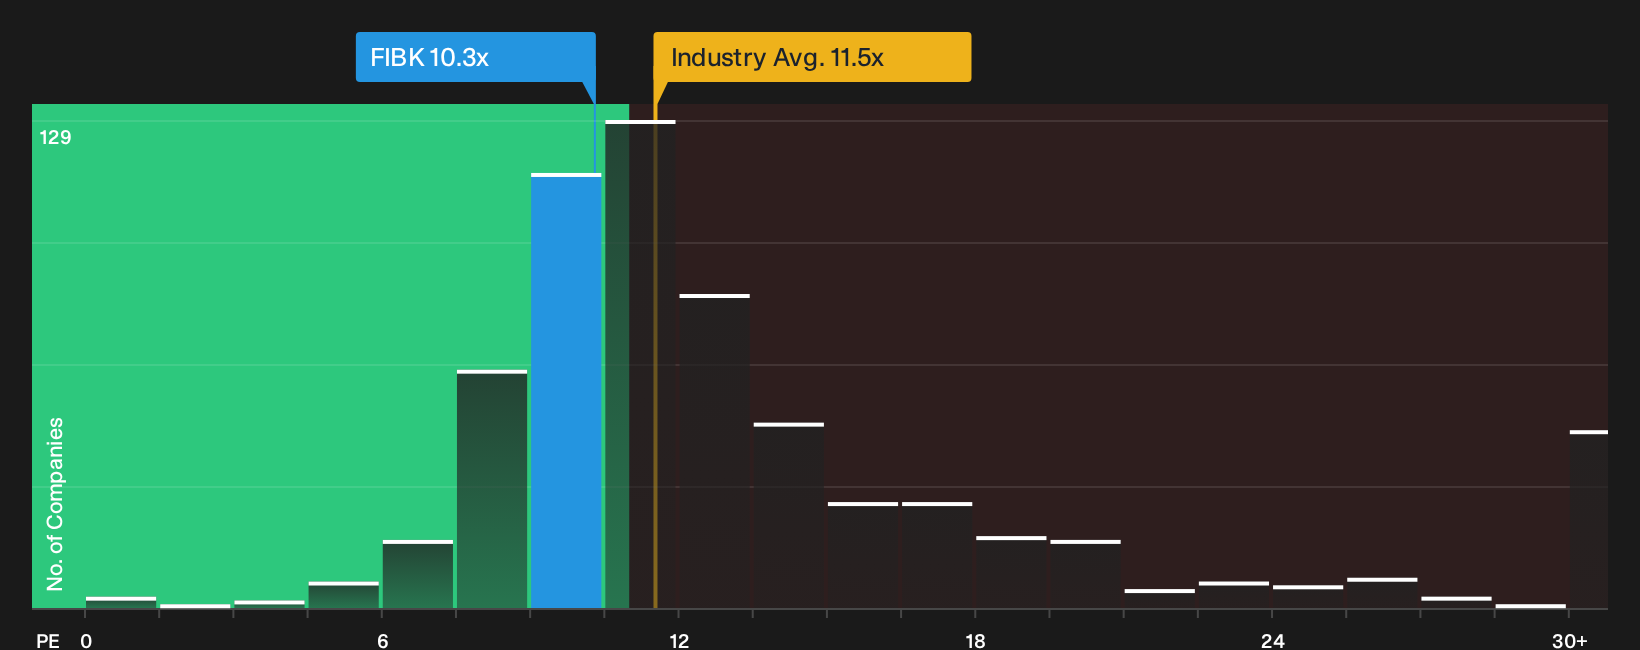
There is a different message in the P/E ratio. First Interstate BancSystem trades on 10.3x earnings, which is cheaper than the US Banks industry at 11.5x and well below peer average at 23.1x, yet above a fair ratio estimate of 8.8x that the market could move toward.
If that fair ratio proves to be the anchor, you are looking at less margin for error than the narrative fair value suggests. This raises the question of which signal to trust more when considering position size or setting entry points.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed views on First Interstate BancSystem at this time. If you want to act before sentiment shifts again, compare the 3 key rewards and 2 important warning signs with your own checklist.
Looking for more investment ideas beyond First Interstate BancSystem?
Do not stop with a single bank story when there are dozens of other potential opportunities on your screen waiting for a closer look today.
- Target value hunters who want quality at a discount by scanning a focused group of 27 high quality undervalued stocks that match strict fundamentals.
- Build a steadier income stream by reviewing a curated set of yield-focused 8 dividend fortresses that pair payouts with financial strength.
- Prioritize resilience in tougher markets by concentrating on a 31 resilient stocks with low risk scores that highlights companies with stronger balance sheets and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com