
3 Core Eurozone Bank Stocks for Investors Watching EU Fiscal Risk
Rising scrutiny of EU finances, from a 3.8% budget error rate to a swelling common debt pile that may approach €1 trillion by 2027, is quietly reshaping how capital treats core eurozone financials. Some banks and insurers in fiscally conservative countries could find this climate a headwind or a cushion. This article walks through three stocks exposed to those fiscal crosswinds and what that context may mean for your portfolio decisions.
The three companies below are just a sample of this theme, and the full screen surfaced 9 more core eurozone financial groups in fiscally conservative countries with equally interesting stories that are not covered here. If you want to go straight to the source and analyze, compare, and identify your own higher conviction ideas, head into the EU Fiscal-Solidarity Beneficiaries (Core Eurozone Financials) screener.
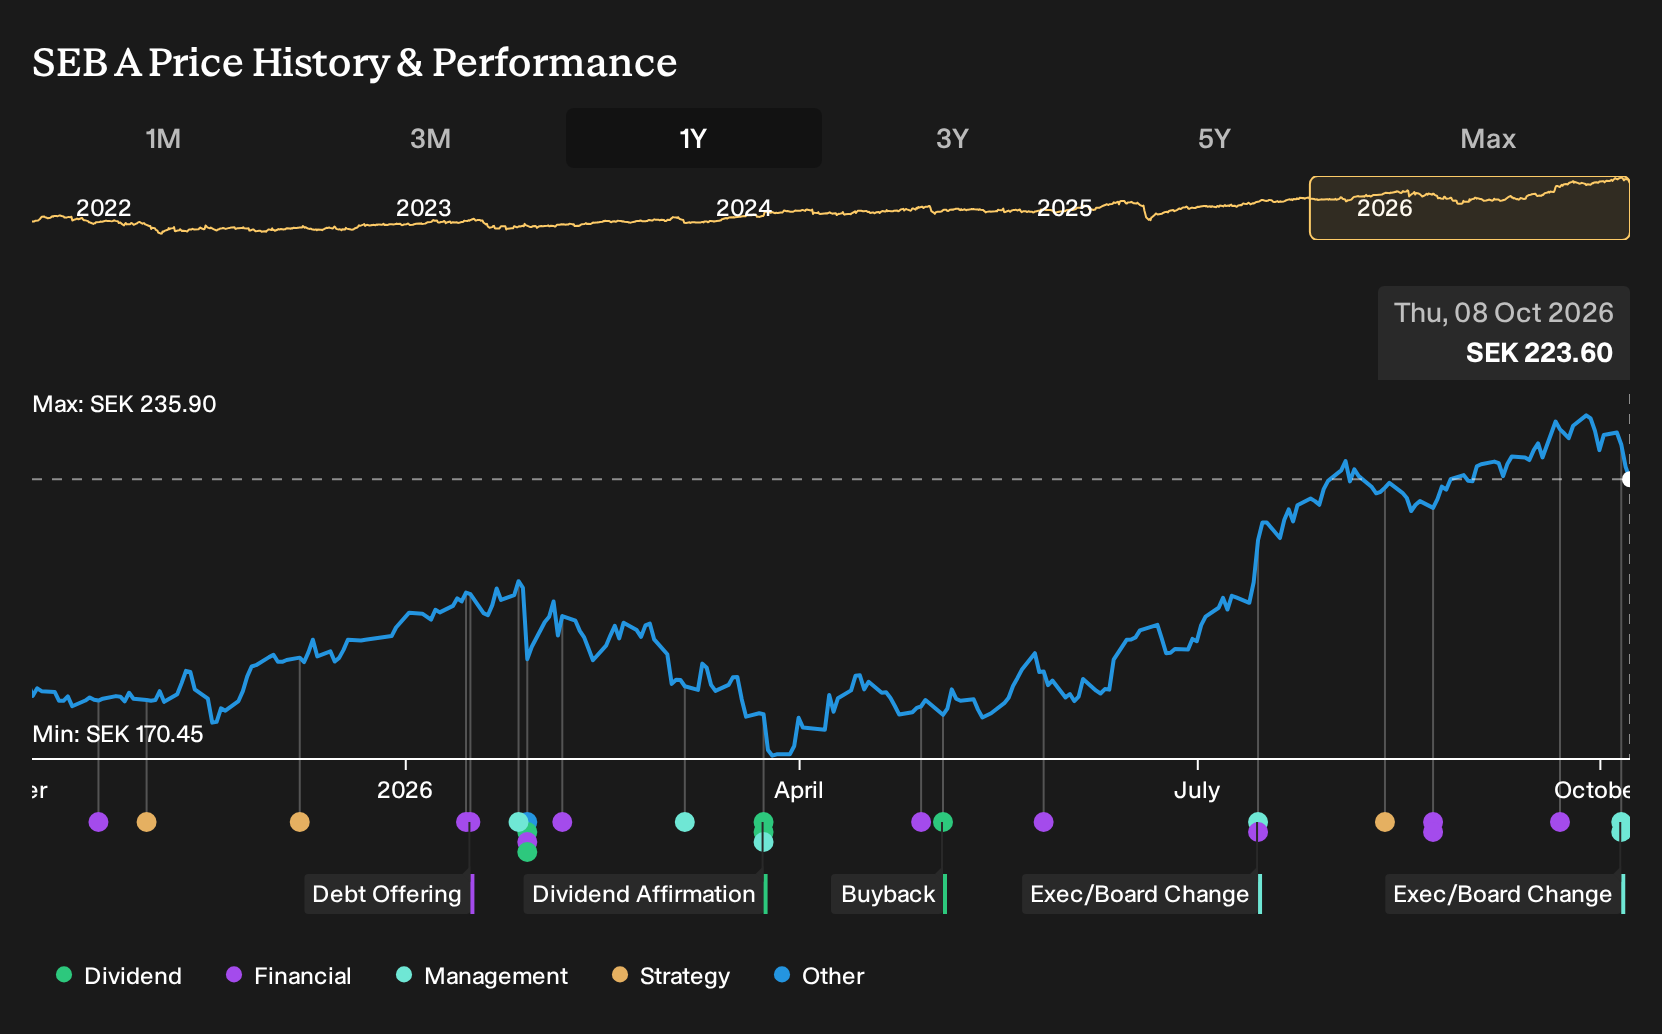
Skandinaviska Enskilda Banken (OM:SEB A)
Skandinaviska Enskilda Banken taps into the fiscally conservative Sweden angle of this screener, giving you a large Nordic lender with broad corporate, retail, and markets exposure that can matter when investors tilt toward stronger core banking systems.
SEB is a universal bank headquartered in Stockholm, active across corporate, retail, wealth and Baltic banking. Corporate & Investment Banking generates about SEK27.7b, Business & Retail Banking SEK22.2b, Wealth & Asset Management SEK11.2b, and the Baltic arm SEK10.5b in revenue, with a market value around SEK434.9b.
"SEB's focus on increasing fees and commissions in the CIB division and customer satisfaction improvements could boost revenue growth."
The real swing factor for Skandinaviska Enskilda Banken sits in how one pressure on future profitability and capital returns ultimately resolves.
How that pressure plays out is only part of the story, and the full narrative for Skandinaviska Enskilda Banken explains where SEB’s capital return ambitions could be accelerating or quietly capped.
BAWAG Group (WBAG:BG)
BAWAG Group is an Austrian bank anchored in a fiscally conservative eurozone country, which ties it neatly to this screener’s focus on core lenders that could be treated differently if investors start to separate stronger sovereigns from the rest.
BAWAG Group runs a broad retail, SME and corporate banking platform across Austria and Western Europe, with most revenue coming from Retail & SME operations at about €1.7b and a further €290 million from Corporates, Real Estate & Public Sector. This gives the business a scale reflected in its roughly €12.9b market value.
For investors watching how EU fiscal discipline and sovereign spreads play out, BAWAG Group offers a pure-play core lender with a tight focus on returns and cost control. Management now points to one operational shift that could matter a lot more than headline macro noise.
"Ongoing integration of Knab and Barclays Consumer Bank Europe, with expected completion by year-end (including exit from transitional service agreements and rebranding), should unlock operational synergies and drive further cost efficiency, supporting higher net margins over time."
The open question is what happens if one untested assumption in that cost story meets a very different path for credit risk or deposit pricing than management expects.
If that cost story feels finely balanced, the full narrative for BAWAG Group shows where BAWAG Group could still accelerate returns or see those efficiency gains quietly absorbed by risk.

ProCredit Holding (XTRA:PCZ)
ProCredit Holding gives you a Germany-based SME and private-client bank that fits the fiscally conservative core eurozone theme while leaning heavily on digital tools to turn that funding base into something more powerful for both earnings and risk control.
ProCredit Holding runs a single Banking segment that generates about €434 million in revenue and has a market value of roughly €501 million.
"Rapid digital onboarding, AI-driven risk management, and rollout of modern banking platforms could, if successful, support margin expansion and potentially move the cost-to-income ratio toward 57%, which would represent an improvement in net margins if achieved."
What really matters now is how one unseen pressure on credit quality and capital discipline interacts with that efficiency story over the coming period.
As that pressure builds around credit quality, the full narrative for ProCredit Holding shows how ProCredit Holding’s efficiency push could accelerate returns or expose hidden fault lines.

Curious About What You Might Be Missing?
Fresh ideas move first. The next breakout stories can build momentum while older themes cool off and drop from view. Scan these under-the-radar lists before the crowd and act now.
- Spot cash generative businesses that still look overlooked by the market and sift through the 620 high quality undiscovered gems before their stories start flying across every watchlist.
- Target resilient balance sheets that can carry earnings power through tough cycles and work through the list of solid balance sheet and fundamentals (206 results) while that quality gap still matters.
- Hunt for durable income streams that might keep paying even when headlines turn messy and search across the 227 dividend fortresses before yields get caught in a rush.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com