
Taysha Gene Therapies (TSHA) Could Be 66% Undervalued On Rett Syndrome Hopes
Taysha Gene Therapies (TSHA) is in focus after recent trading left the share price at US$4.43, drawing attention to how its clinical-stage gene therapy pipeline aligns with current market expectations.
Recent trading tells a mixed story. The share price return over the past month is down 19.16% and the 90 day move is down 30.13%. However, Taysha Gene Therapies still carries a three year total shareholder return of 90.13%, despite a five year total shareholder return that is down 75.98%.
Scan how Taysha Gene Therapies compares with other high potential biotech stories by reviewing the hand picked 20 high quality undiscovered gems shaping this corner of the market.
The recent pullback in Taysha Gene Therapies leaves you weighing an early entry against waiting for more clarity. Does the current price already reflect the risks in this gene therapy pipeline, or not yet?
Most Popular Narrative: 66% Undervalued
On the most followed narrative, Taysha Gene Therapies screens as undervalued, with a fair value of $12.85 against the latest close at $4.43. This puts all the weight on how its Rett syndrome program plays out.
The analysts have a consensus price target of $12.85 for Taysha Gene Therapies based on their expectations of its future earnings growth, profit margins and other risk factors. In order for you to agree with the analysts, you'd need to believe that by 2029, revenues will be $233.1 million, earnings will come to $44.1 million, and it would be trading on a PE ratio of 120.6x, assuming you use a discount rate of 7.2%.
See why 13 investors see Taysha Gene Therapies as 66% undervalued.
Result: Fair Value of $12.85 (UNDERVALUED)
Still, the reliance on a single lead therapy in TSHA-102 and ongoing net losses mean any clinical or regulatory setback could quickly challenge the case that this stock is undervalued.
Find out about the key risks to this Taysha Gene Therapies narrative.
Another View On Taysha Gene Therapies Valuation
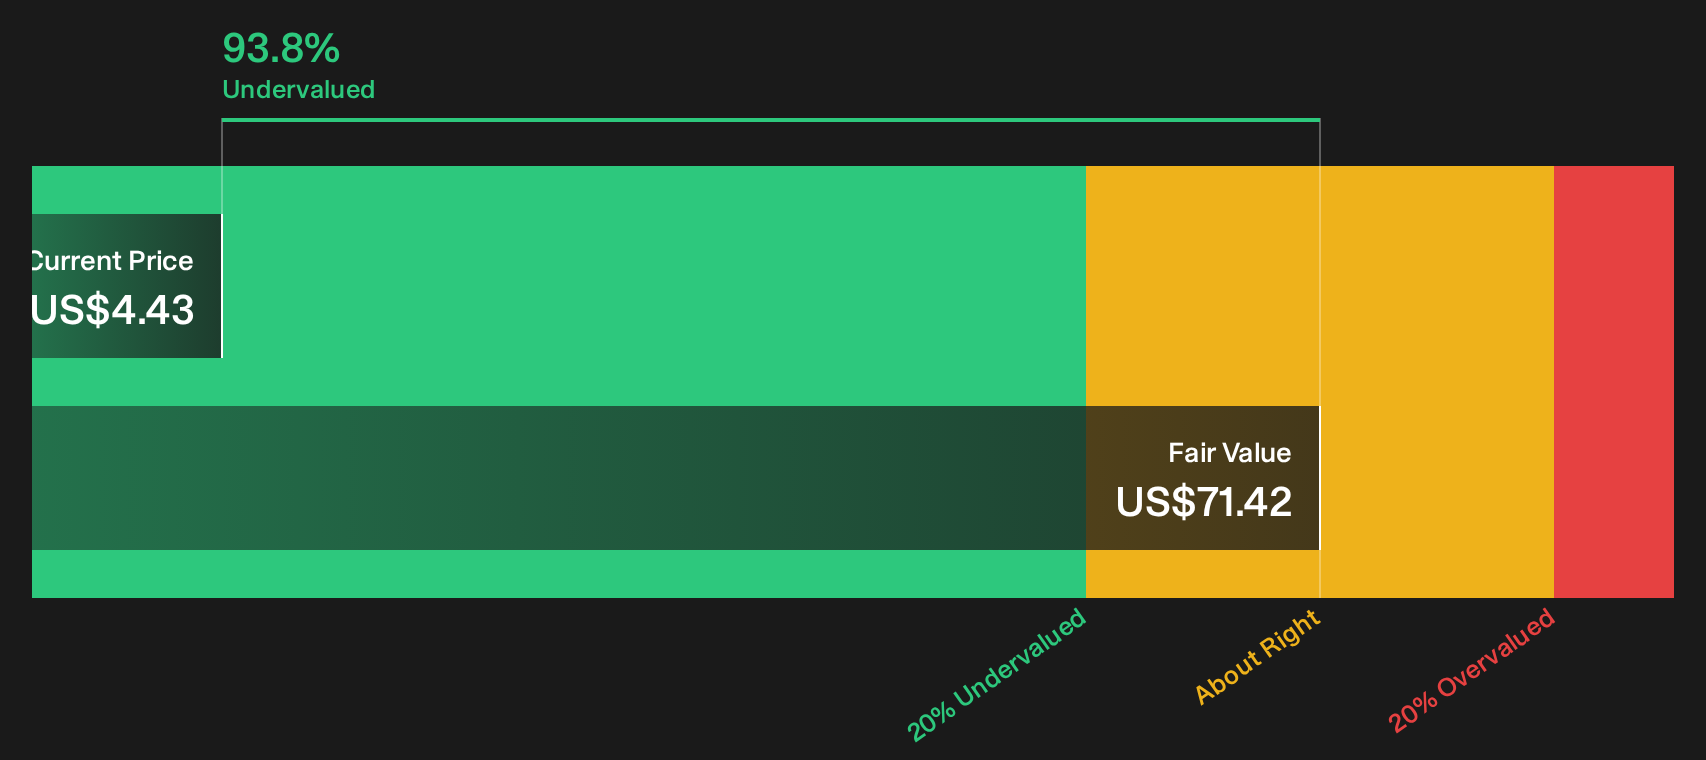
The first story around Taysha Gene Therapies leans heavily on analyst targets and future earnings assumptions. A different lens comes from the SWS DCF model, which places future cash flow value at $71.42 per share against the current $4.43 price, flagging TSHA as deeply undervalued. Does that gap signal mispricing, or just very demanding expectations for Rett success?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed views like these do not settle the question for you; they sharpen it and reward investors who do the homework now rather than later. To weigh both the upside story and the risk list in one place, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Taysha Gene Therapies?
If Taysha Gene Therapies has your attention, do not stop there. Broaden your watchlist with focused stock ideas built from hard numbers, not headlines.
- Target potential mispricing by scanning a curated set of 27 high quality undervalued stocks that pair quality fundamentals with a gap between price and underlying business strength.
- Prioritise resilience first by reviewing a list of solid balance sheet and fundamentals (25 results) that highlights businesses with robust finances that can better handle tougher conditions.
- Hunt for future market leaders early by working through a 10 elite penny stocks with strong financials that focuses on smaller companies with stronger financial profiles than the typical micro cap crowd.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com