
Learn Why The Bull Case For CACI International (CACI) Could Change Following Earnings Beat
- CACI International recently reported earnings that exceeded market estimates, underscoring resilient demand for its national security technology and secure IT solutions for federal customers.
- The earnings beat highlights how CACI International’s mix of electronic warfare, cyber defense, and space programs is contributing to stronger operational execution and contract performance.
- This article examines how CACI International’s investment narrative is affected by this earnings beat as analysts reassess execution risks.
CACI International Investment Narrative Recap
For CACI International, the core belief is that a large, long dated federal backlog in areas like electronic warfare, cyber defense, and space can be turned into steadier earnings and better cash generation. The recent earnings beat supports the idea that execution on existing contracts is tracking well, which helps near term confidence in this conversion story.
The key short term catalyst remains how effectively that record backlog and rising fixed price mix translate into higher margins and free cash flow. The main risk is that heavier capital spending and integration costs do not translate into stronger cash generation, especially given concerns that debt is not well covered by operating cash flow.
Among recent developments, the most relevant to the earnings surprise is the continued shift in CACI International’s portfolio toward higher value defense tech work, including software defined platforms and cyber solutions. Around 60% to 70% of revenue is tied to this type of activity, with EBITDA margins reported in the low to mid teens.
That mix matters for catalysts because many of the highlighted programs, such as Spectral, Domestic Shield, NITE STAR, and Enterprise Space Terminal, sit inside this defense tech bucket and are moving through production phases. As these awards convert and volumes ramp through facilities like the Defense Electronics Manufacturing Center, investors will likely focus on whether EBITDA margins and free cash flow actually track the efficiencies implied by recent results.
CACI International's narrative projects US$12.2b revenue and US$727.8m earnings by 2029. This assumes 8.3% yearly revenue growth and an earnings increase of about US$192m from current earnings of US$535.8m.
Uncover how CACI International's fair value indicates a 23% potential upside to its current price before other investors close that gap.
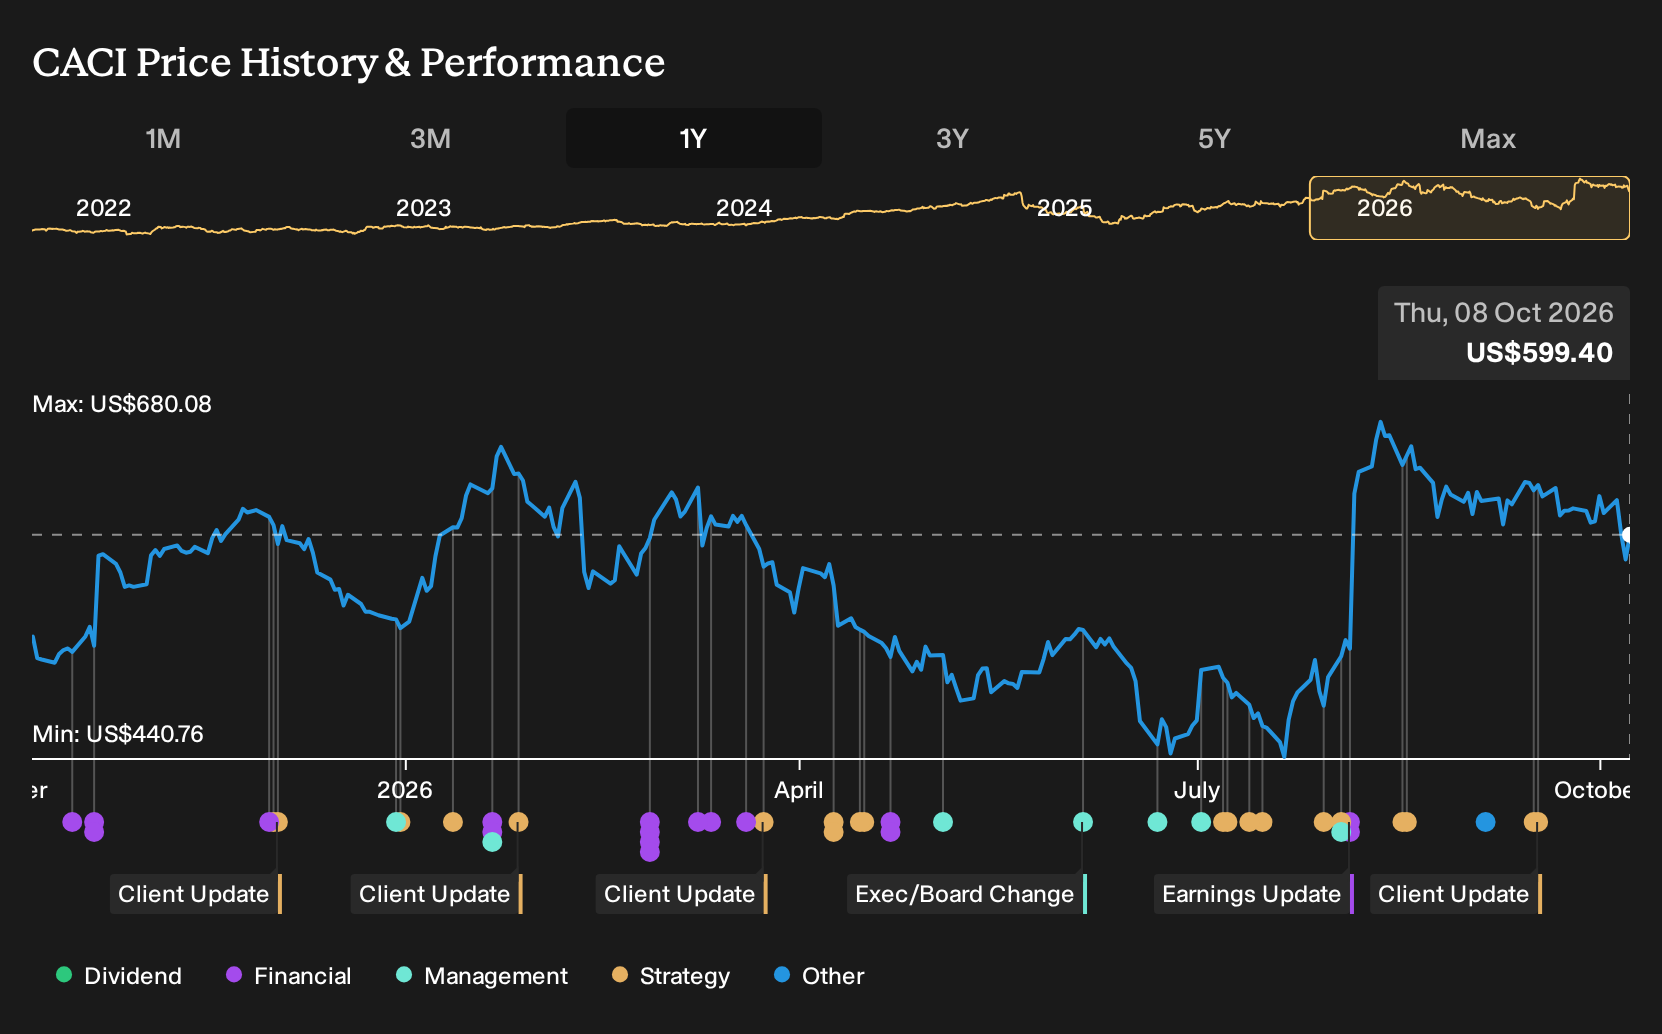
Exploring Other Perspectives
One alternate view focuses on budget risk. The most pessimistic CACI International analysts were already assuming tighter government funding and smaller gains, with revenue modeled at about US$11.8b and earnings of roughly US$625.1m by 2029. That is far below the bullish end. After this earnings surprise, those cautious assumptions may be revisited.
Explore 3 other CACI International fair value estimates, including one that suggests it could be worth just $730.29!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CACI International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CACI International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CACI International's overall financial health at a glance.
Looking for more CACI International style investment ideas?
If the latest CACI International narrative has sharpened your thinking around quality, risk, and cash generation, use that same lens to scan a broader opportunity set with the Simply Wall St Screener.
- If you care most about financial resilience and balance sheet strength, start with a focused list of solid balance sheet and fundamentals (25 results) that already clear key quality hurdles.
- For investors hunting for potential mispricing and quality together, filter for companies on our 27 high quality undervalued stocks and see which businesses show a similar blend of fundamentals and valuation appeal.
- If you prefer to spot opportunities before they are widely followed, cast a wider net across 20 high quality undiscovered gems that pair robust underlying metrics with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com