
Is Joby Aviation (JOBY) Above Fair Value As Sales Stay Thin?
Joby Aviation has seen its stock slide sharply over the past year, even as the business moves closer to launching electric air taxi services. With the share price now reflecting a very different market mood, the key issue for investors is how well that price lines up with the company’s sales.
- The stock has fallen 66.5% over the past 12 months, which puts fresh focus on whether the current valuation can still be explained by Joby Aviation’s revenue base.
- Progress toward FAA certification and preparations for commercial flights, backed by Toyota’s investment and manufacturing support, may influence how quickly future sales can ramp and how much funding the business might still require.
- Your read on Joby Aviation is one view; the desks covering it have another. See what analysts think Joby Aviation's shares could be worth.
The issue now is whether Joby Aviation’s current share price is justified by its sales when judged against the Fair Ratio benchmark.
If you want a broader starting point for research around Joby Aviation’s electric air mobility theme, you could also scan a focused list of 37 AI small caps.
Has Joby Aviation Run Too Far on Sales?
The price-to-sales (P/S) ratio fits Joby Aviation better than earnings-based metrics because the business is still loss making and investors are effectively paying for future revenue potential rather than current profits.
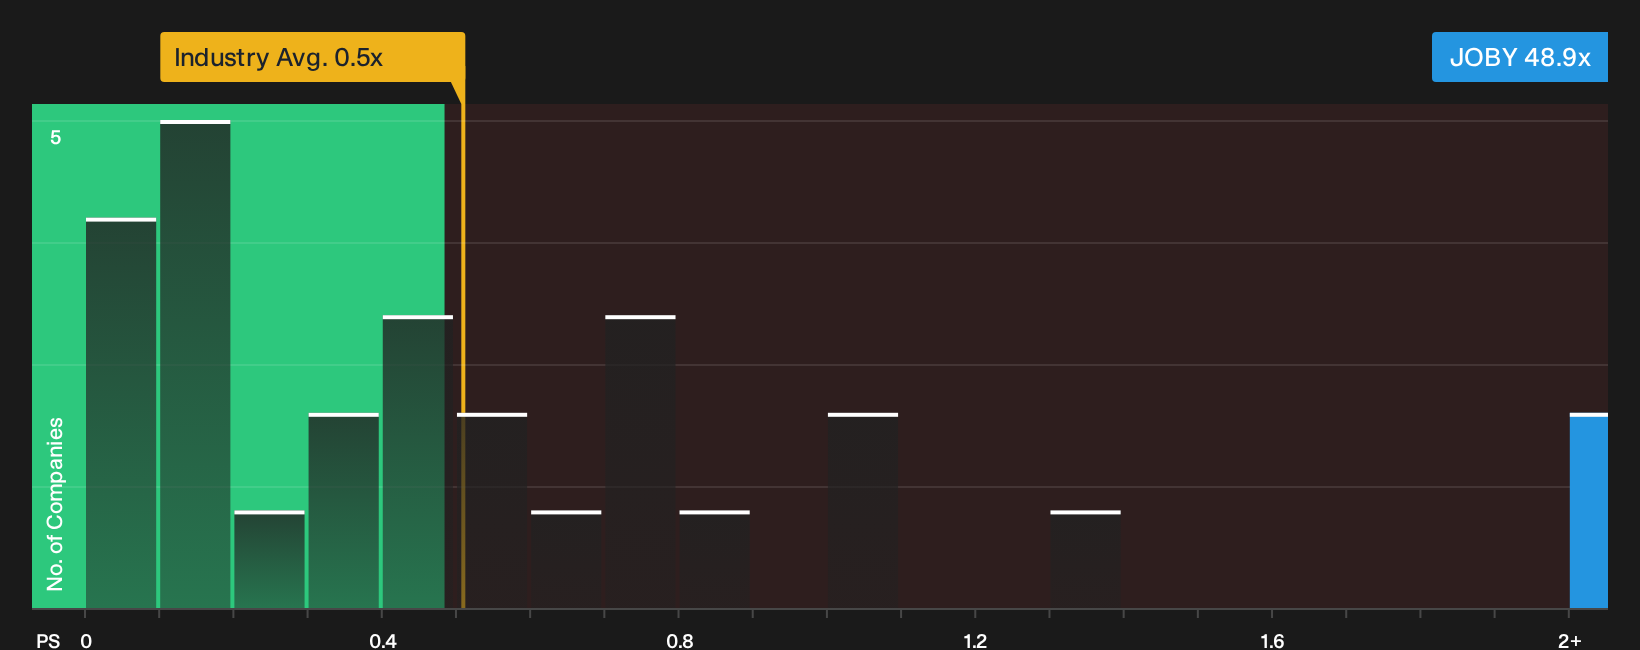
On this yardstick, the stock trades on a P/S of 48.9x, far above the Airlines industry average of 0.5x and a peer group around 0.7x. That is a very rich top line multiple for any transport business, even one building a new category, and it means each dollar of Joby Aviation sales is priced at a heavy premium to more mature operators. The Fair Ratio model, which adjusts for factors such as growth profile, margins, size and risk, flags the current P/S as higher than the level it would expect and effectively treats the gap as a warning signal rather than a precise target.
Because Joby Aviation is progressing toward FAA certification and first commercial flights, and has visible backing from Toyota, faith in the story already appears heavily embedded in the valuation multiple. Despite that support and the Dallas Fort Worth launch plans, the current P/S still screens as expensive on this framework compared with what the Fair Ratio would imply for the stock. Explore the numbers behind Joby Aviation's P/S valuation.
The Joby Aviation Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Joby Aviation pick up where the valuation puzzle leaves off and explain which combinations of revenue growth, profitability and earnings power would need to occur for the stock to be worth materially more or less than today’s market price. While a single ratio or model gives you one number, these scenarios describe the future that number depends on so you can see whether Joby Aviation's actual progress continues to match the story implied by the valuation, all hosted on Simply Wall St's Community page.
One of the top community narratives on Joby Aviation: 68% undervalued
"Partnerships with Toyota, L3Harris, Uber and Blade, combined with expanding manufacturing in California and Ohio, enable production scale and dual use platforms..."
Discover why this Narrative puts Joby Aviation at 68% undervalued.
Joby Aviation’s valuation story still leaves one crucial issue unresolved
Price tags only tell part of the story for Joby Aviation, and our research has also surfaced company specific checks that point to issues investors may want to weigh before going further. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com