
Byline Bancorp (BY) On The Capital Return Story And Its Fair Value Gap
Byline Bancorp (BY) has drawn attention after its recent share performance, with the stock closing at US$36.88 as investors consider its banking focus on small and mid-sized businesses in Chicago and across the United States.
Recent trading has been choppy for Byline Bancorp, with a 1-day share price return of 0.85% but a 30-day share price return down 3.63%. At the same time, the year-to-date share price return of 27.00% and 1-year total shareholder return of 37.14% point to momentum that has been building over a longer stretch rather than fading.
Scan how Byline Bancorp compares with other regional financials that are showing strong momentum and fundamentals by reviewing the curated list of solid balance sheet and fundamentals (25 results)
Byline Bancorp now trades at a clear discount to both analyst targets and some fair value estimates after a strong run. Is that a market overreaction, or a sensible buffer around a regional lender?
Most Popular Narrative: 14.6% Undervalued
Byline Bancorp's most followed narrative pegs fair value at $43.20, which sits above the last close of $36.88 and presents the current discount as a story about efficiency, capital use and regulation rather than just short term trading moves.
The combination of a strong capital position, regular dividend increases and active share repurchases, together with an open stance toward selective bank acquisitions, is characterized as giving Byline Bancorp multiple levers to deploy excess capital in ways that can support earnings per share.
See why 0 investors see Byline Bancorp as 15% undervalued.
Result: Fair Value of $43.20 (UNDERVALUED)
Still, Byline Bancorp is tightly tied to Chicago and the Midwest, and the move past US$10b in assets brings Durbin related fee pressure and extra compliance costs.
Find out about the key risks to this Byline Bancorp narrative.
Another View On Byline Bancorp's Valuation
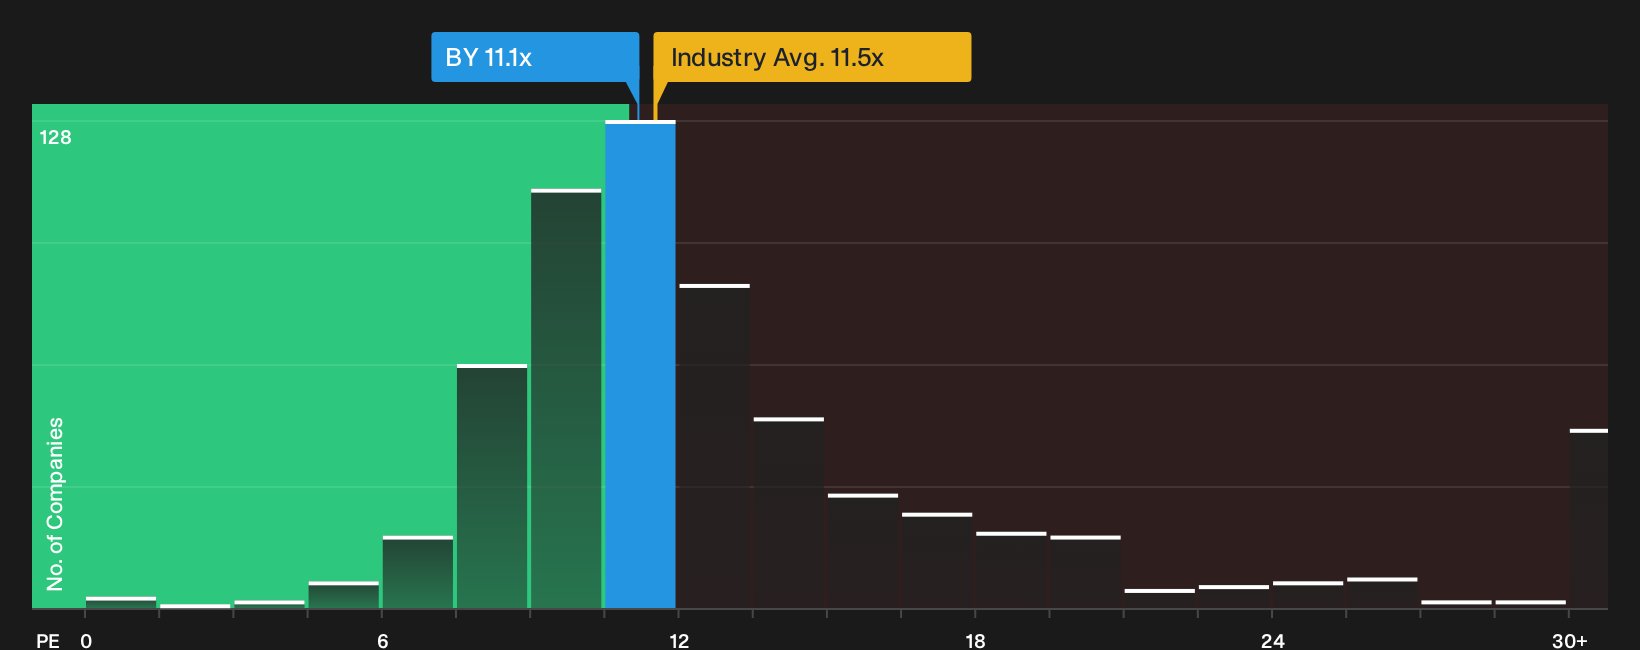
On simple price targets and fair value estimates, Byline Bancorp looks 14.6% undervalued at $36.88 versus a fair value of $43.20. On earnings multiples though, the picture is less one sided. The stock trades on a P/E of 11.1x, slightly above a fair ratio of 10.7x, and only a touch below the US Banks industry at 11.4x and well under the peer average of 21.3x. That mix of small premium to the fair ratio but discount to peers leaves a practical question for investors: Is this more a margin of safety or a signal that expectations are already generous?
For a closer look at how that P/E gap could close over time, including how it compares with both the industry and a fair ratio that the market could move toward, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Byline Bancorp is mixed, with both risks and potential rewards in play. Move quickly and test the numbers against your own expectations by reviewing the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Byline Bancorp?
If Byline Bancorp has your attention, do not stop there. Broaden your watchlist now so you are not chasing the next opportunity after it moves.
- Hunt for mispriced quality by scanning the 27 high quality undervalued stocks that pair solid fundamentals with room for sentiment to catch up.
- Reinforce your income stream by checking companies in the 8 dividend fortresses that focus on higher yields backed by sturdier balance sheets.
- Protect your downside first by filtering through the 31 resilient stocks with low risk scores built around stronger financial health and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com