
How Investors May Respond To Travelers Companies (TRV) Earnings Beat Hopes
- Travelers Companies recently saw increased attention after a period in which it repeatedly beat earnings estimates, supported by a positive Earnings ESP and favorable ranking from analysts.
- This pattern of outperformance highlights how Travelers Companies' current earnings power may be a key focus for investors weighing its longer term profitability profile.
- We will now explore how Travelers Companies' recent history of beating earnings projections could reshape the investment narrative around its future margins.
See how Travelers Companies' earnings momentum compares with other potential outperformers by running through the hand picked 27 high quality undervalued stocks that pair solid fundamentals with attractive pricing.
Travelers Companies Investment Narrative Recap
To own Travelers Companies, you need to be comfortable with an insurer that leans heavily on underwriting discipline, technology spend and capital returns, while accepting that property and casualty cycles can compress profitability. The short term swing factor is whether underwriting results and catastrophe losses keep supporting the current earnings power highlighted by recent estimate beats. The biggest operational risk remains heavier catastrophe activity or casualty severity that pushes combined ratios higher and eats into net income.
The recent pattern of beating quarterly expectations reinforces that Travelers Companies is executing on pricing, risk selection and its US$1.5b technology and AI budget, but it does not remove the structural pressures flagged by analysts. Commentary about commercial pricing already running below loss trends, ongoing long tail casualty uncertainty and competitive personal lines suggest that even strong quarters can sit alongside a tougher medium term margin picture.
With no major new announcements tied directly to this earnings momentum, the clearest reference point is management's emphasis on technology and AI investment, which runs at more than US$1.5b a year. These tools have been linked to around a 0.5 point improvement in the Business Insurance underlying loss ratio in Q2 2026, providing a tangible operational metric to watch as results come through.
For you as an investor, the question is whether that tech and data spend, combined with conservative reserving and 19 years of favorable prior year development totaling US$15b pre tax, can keep underwriting outcomes resilient if pricing softens or catastrophe and casualty trends worsen. That same execution track record sits alongside large capital returns, including US$3.3b of buybacks in the first half of 2026, which concentrates any future earnings swings on a smaller share base.
Travelers Companies Earnings Power Versus Analyst Assumptions
Travelers Companies now sits in a curious spot where recent results have been strong, yet the consensus model points to thinner profitability over the next few years. Analysts are baking in revenue that declines by 1.1% per year and margin compression from 16.8% today to 11.1% in three years. This implies a very different earnings profile than the run of upbeat quarters might suggest.
The earnings path in those models is blunt. Forecast consensus calls for net income of US$5.2b by 2029 compared with US$8.2b today, so the projected earnings pool is expected to be US$3.0b lower even before factoring in any upside or downside from weather or casualty swings. More optimistic analysts are still only at US$6.0b, which keeps the forecast range well under the current earnings base and frames the recent beats as potentially late cycle rather than a new normal.
Valuation work in the same reports leans heavily on that 2029 snapshot. To line up with an average price target, you would need to assume Travelers Companies can generate revenues of US$47.3b and earnings of US$5.2b in 2029, while the shares trade on a P/E of 14.5x compared with 9.5x today and an industry multiple of 11.1x. That mix pairs lower forecast profit with a higher earnings multiple. It effectively asks you to believe the quality and durability of the earnings stream will justify paying more for each dollar of profit even if that profit pool is smaller.
Capital management assumptions add another twist. Analysts are building in a 6.5% yearly reduction in the share count for the next three years, which would mechanically lift earnings per share relative to total earnings and tighten the link between underwriting volatility and each remaining share. For you as a shareholder, that setup means any variance from the US$5.2b earnings path or from the expected margin decline could have an outsized impact on per share metrics.
Travelers Companies' narrative projects US$47.3b revenue and US$5.2b earnings by 2029. This assumes revenue declines at 1.1% per year and earnings fall by US$3.0b from US$8.2b today.
Uncover why Travelers Companies' fair value indicates a 3% potential downside to its current price, leaving little room for error.
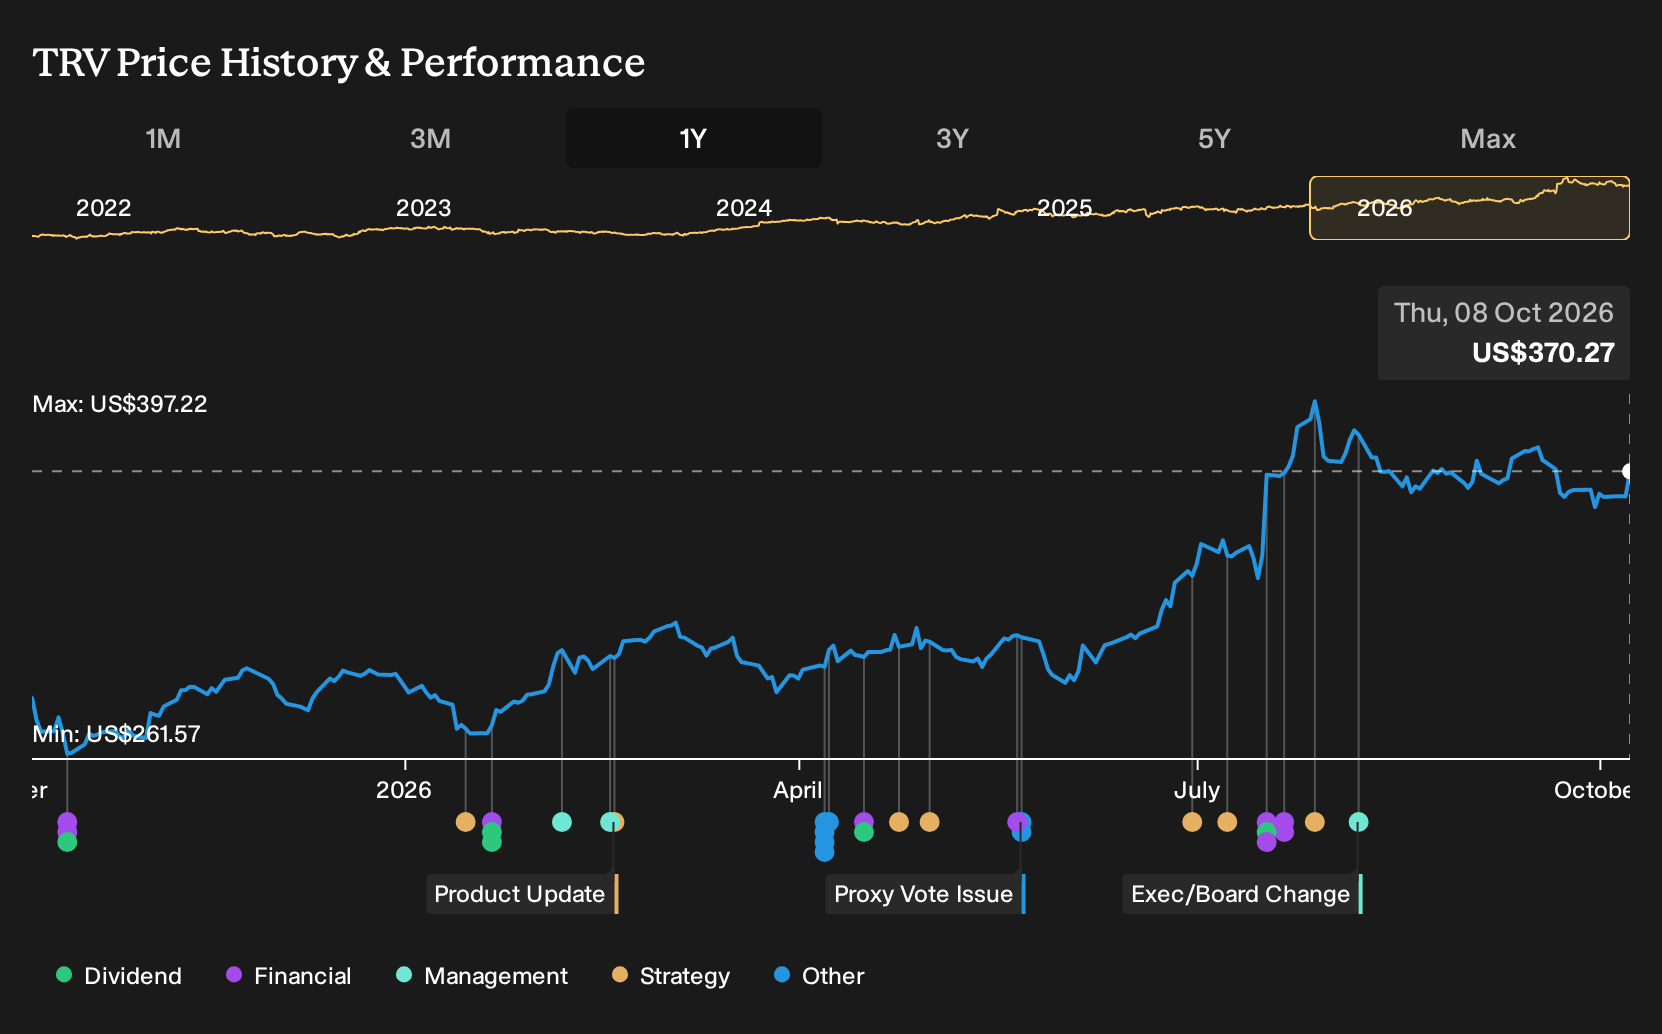
Exploring Other Perspectives
For Travelers Companies, the biggest swing factor that contrasts with the baseline story is how bullish analysts view technology and AI. Some of the highest forecasts were built on US$5.7b of earnings and US$46.9b of revenue by 2029, before this latest earnings news. Those projections reflect a far more optimistic narrative that you can now reassess in light of the fresh update.
Explore 2 other Travelers Companies fair value estimates, including one that suggests there could be up to 106% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Travelers Companies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Travelers Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Travelers Companies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Travelers Companies?
If the Travelers Companies story leaves you wanting a broader watchlist, cast the net wider using the Simply Wall St Screener. You can quickly filter for different types of opportunities and line them up against what you see in Travelers Companies.
- If capital preservation is your priority, start with companies that show steadier profiles by checking out 31 resilient stocks with low risk scores that may help reduce portfolio volatility.
- If reliable cash flows matter most, focus on income opportunities through the 8 dividend fortresses that highlight businesses combining higher yields with more durable payout records.
- If you want to back strong balance sheets, look for financially resilient businesses using the list of solid balance sheet and fundamentals (25 results) which focus on companies with healthier leverage and fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com