
Colruyt Group (ENXTBR:COLR) Faces A Fresh Test As Self Checkout Rollout Meets Valuation Debate
Colruyt Group (ENXTBR:COLR) has hit a fresh technology milestone by rolling out Toshiba’s ELERA Self Service solution to 150 stores with 454 self checkouts, sharpening the focus on customer experience and store efficiency.
Despite this push into self checkout technology, Colruyt Group’s share price return has been mixed. The stock is up 6.81% year to date but has recorded a 30 day share price decline of 13.56%. The 1 year total shareholder return of 7.84% contrasts with a 3 year total shareholder return decline of 7.72%, indicating improving momentum after a tougher multi year stretch.
Spot opportunities around Colruyt Group’s digital push by scanning a curated 88 robotics and automation stocks that are reshaping how retailers run stores and manage customer flows.The recent swing in Colruyt Group’s share price presents a clear decision point for investors. Are markets reassessing the business itself or mainly sentiment as the tills become more digital, and what does the current valuation imply?
Most Popular Narrative: 26% Undervalued
Colruyt Group last closed at €33.90, while the most followed valuation narrative from StoxEurope points to a fair value of €46.08. This frames the recent technology news against a much higher long term estimate.
The StoxEurope estimate is €46.08 per share. It comes from the primary model, the discounted cash flow of the whole business, which was chosen for Colruyt before any value was computed. Across three modelled scenarios the primary model gives a range from €33.71 to €53.25; those are scenarios, not a statistical confidence interval.
See why 1 investors see Colruyt Group as 26% undervalued.
Result: Fair Value of €46.08 (UNDERVALUED)
Still, two issues could challenge that 26% undervaluation story for Colruyt Group: softer earnings guidance after September’s outlook cut and ongoing pressure on free cash flow coverage of distributions.
Find out about the key risks to this Colruyt Group narrative.
Another View: Our DCF Model Flips the Story
The StoxEurope work-up paints Colruyt Group as 26% undervalued at €46.08 per share. Our own SWS DCF model points in the opposite direction. It values future cash flows at €27.04 per share, which is below the current €33.90 price and indicates the stock is overvalued instead.
This gap between a higher narrative fair value and a lower cash flow estimate highlights real disagreement on how durable Colruyt Group’s earnings and payouts might be. As an investor, which signal carries more weight for you: the optimistic scenario range, or the stricter cash flow test?
Look into how the SWS DCF model arrives at its fair value.
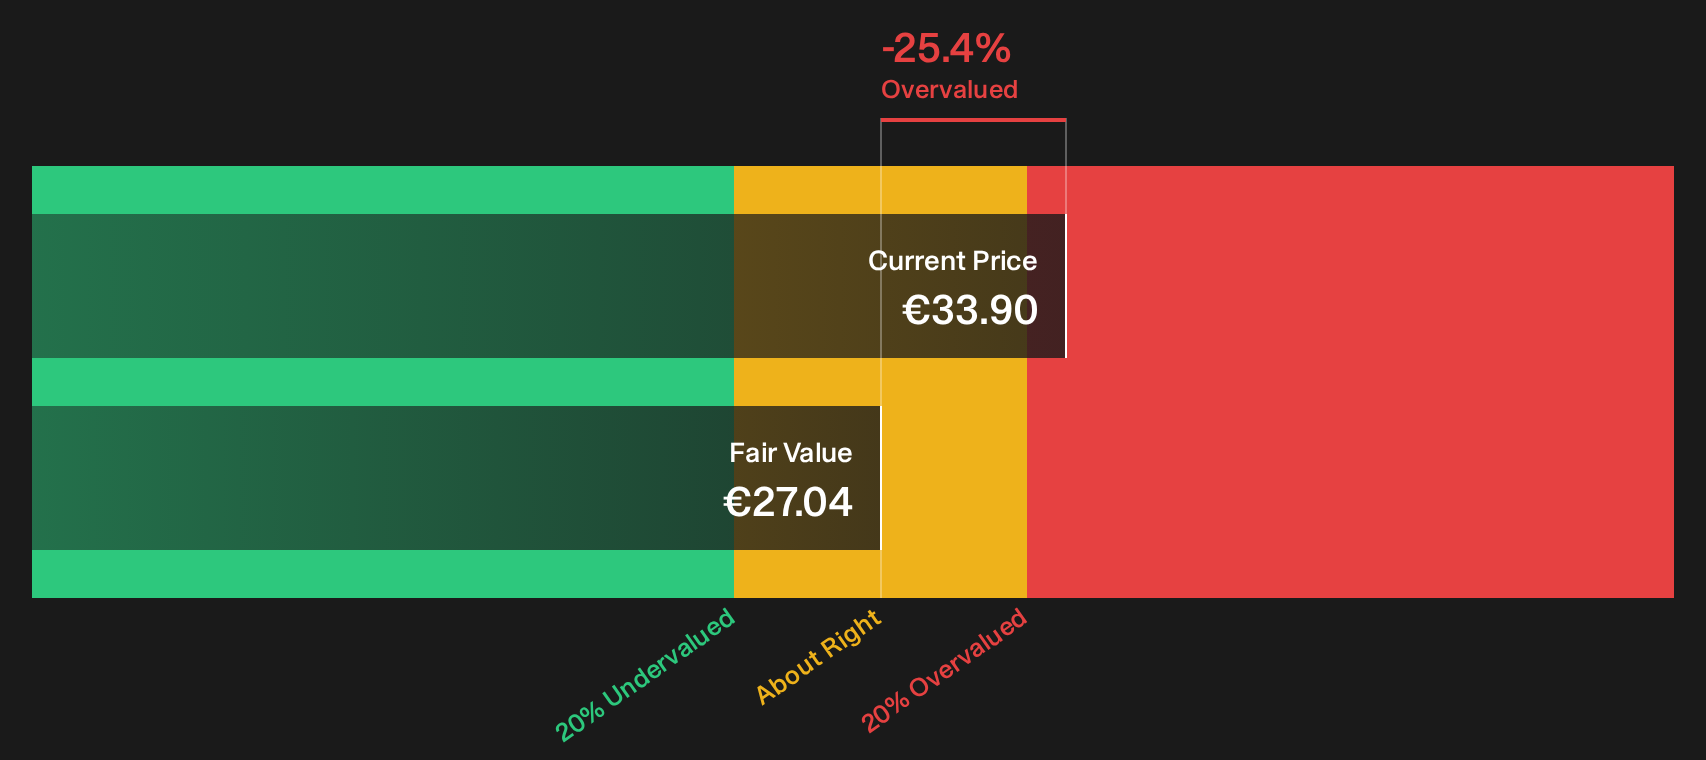
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Colruyt Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Colruyt Group can be useful if you are willing to move fast, pressure test the numbers yourself, and decide where you stand. To see how the potential upside compares with the concerns flagged by other investors, review the 1 key reward and 1 important warning sign.
Looking for more Colruyt Group sized investment ideas?
If you stop at Colruyt Group, you risk missing other opportunities that match your style, risk tolerance, and return goals across different parts of the market.
- Target potential mispricings by scanning a curated set of quality opportunities through the 179 high quality undervalued stocks.
- Strengthen capital preservation by reviewing a focused 225 resilient stocks with low risk scores that keeps volatility and balance sheet concerns in tighter check.
- Hunt for early stage potential by checking a hand picked 119 elite penny stocks with strong financials that filters for stronger financial foundations than typical micro caps.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com