
Visa (V) Could Be 13% Undervalued Following Stablecoin Payment Expansion
Visa (V) has moved deeper into stablecoin and blockchain payments, linking its network to SAP Pay settlements and 24/7 funding tools. This is sharpening investor focus on how the stock prices that role.
Recent crypto conference appearances and stablecoin headlines are landing against a stock that has quietly gathered momentum. Visa’s 7.49% 90 day share price return and 62.07% three year total shareholder return suggest that investors have been willing to pay up as the business leans further into blockchain linked payments.
Spot emerging payment plays that are benefiting from the same blockchain and stablecoin momentum as Visa by scanning our curated list of 20 cryptocurrency and blockchain stocks.Visa’s recent move sits at a crossroads. Is the price tagging along with blockchain headlines and hedge fund interest, or lining up cleanly with what the underlying cash machine is actually worth today?
Most Popular Narrative: 54% Overvalued
Visa last closed at $375.10, while the most followed valuation narrative pegs fair value at $243.70. That gap is steering attention away from blockchain headlines and toward what the underlying cash flows might actually support today.
Visa executes steadily on its three-pillar strategy: Consumer Payments volume growing 8-9% in constant dollars driven by secular cash-to-card conversion and cross-border recovery, CMS at ~20% initially decelerating to ~12% by FY30, VAS sustaining 20-25% growth before decelerating to ~15% by FY32 as the business matures. The DOJ antitrust case resolves with a monetary settlement and limited routing adjustments, painful but not structurally disruptive to the debit network economics.
See why 11 investors see Visa as 54% overvalued.
Result: Fair Value of $243.70 (OVERVALUED)
Still, that script relies on favorable DOJ settlement terms and assumes that account-to-account payment rails remain fragmented enough for Visa Direct to keep its current role.
Find out about the key risks to this Visa narrative.
Another View on Visa’s Valuation
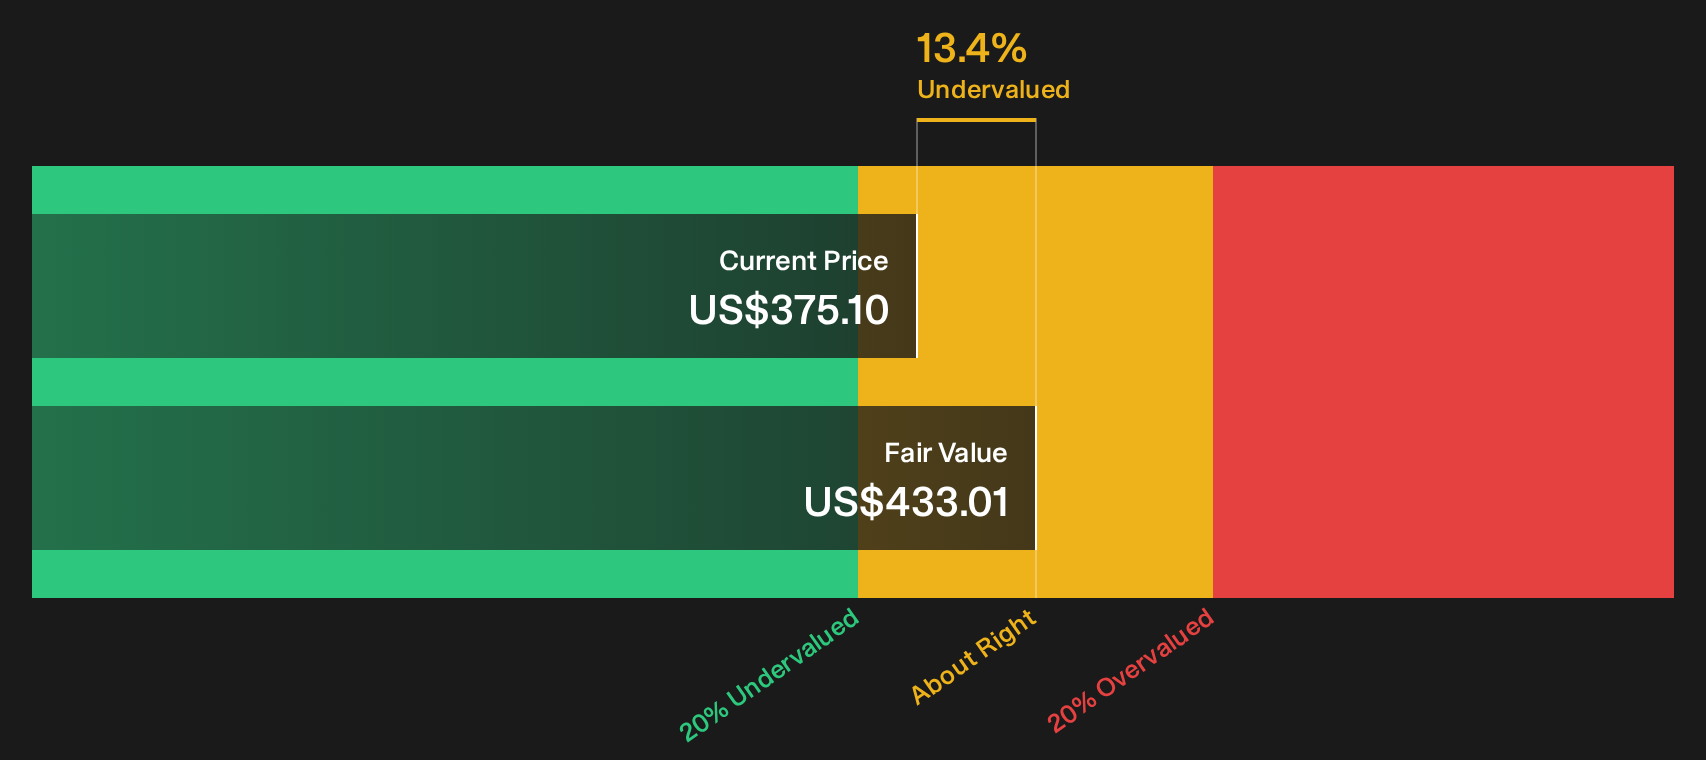
The first narrative tags Visa as 54% overvalued against a $243.70 fair value. Our DCF model lands elsewhere. On that framework, Visa at $375.10 screens about 13% below an estimated future cash flow value of $433.01, which points to upside rather than excess. Which version of “fair” do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on Visa tend to create opportunity for investors who are willing to look past headlines and into the underlying numbers themselves. If you want to weigh the potential rewards against the flagged concerns and come to your own view, start by checking the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Visa?
Visa gives you one angle on digital payments, but your portfolio deserves more than a single story. Let the data surface ideas you might be missing.
- Target resilient compounding by scanning a curated set of companies with steady cash flows and clean finances through the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities by checking a focused group of potential bargains filtered in the 27 high quality undervalued stocks.
- Stack potential income and stability by reviewing a hand picked pool of higher yielding payers in the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com