
DXC Technology (DXC) Could Be 10% Overvalued Following Its AI Insurance Platform Push
DXC Technology (DXC) has rolled out new Assure Platform upgrades, including AI-enabled Smart Apps and low-code workflow tools, aimed at helping insurers modernize operations while keeping existing systems in place.
DXC Technology shares have picked up short term momentum, with a 1-day share price return of 2.91% and a 90-day share price return of 32.73%. However, the year-to-date share price return is down 12.14% and the 5-year total shareholder return has declined 64.25%. This suggests the market is reassessing execution risks and potential benefits from DXC’s insurance focused AI rollout rather than rewarding long term holders so far.
Spot opportunities beyond DXC Technology by scanning a curated set of insurers and AI focused IT providers in the 27 high quality undervalued stocks.DXC Technology has surged in recent weeks, yet long term holders are still nursing steep losses. Is this the start of a broader reset in valuation, or has the easy upside already been taken?
Most Popular Narrative: 10% Overvalued
DXC Technology last closed at $12.37, while the most followed narrative anchors fair value at $11.21 using a 12.54% discount rate. That gap puts the recent rally against a framework that already bakes in both the AI opportunity and the execution risk.
The shift away from linear, labor intensive work toward capital light products such as OASIS, CoreIgnite and insurance SaaS offerings like Horizon and Assure Smart Apps, with recurring software, SaaS and AI revenue in insurance growing at 24%, creates a larger mix of higher margin revenue that can support both net margin expansion and more predictable earnings.
See why 14 investors see DXC Technology as 10% overvalued.
Result: Fair Value of $11.21 (OVERVALUED)
Still, DXC Technology faces two clear pressure points: continued organic revenue declines and persistent weakness in GIS margins, which could quickly challenge the current AI led optimism.
Find out about the key risks to this DXC Technology narrative.
Another View: What DXC Technology’s Earnings Multiple Is Telling You
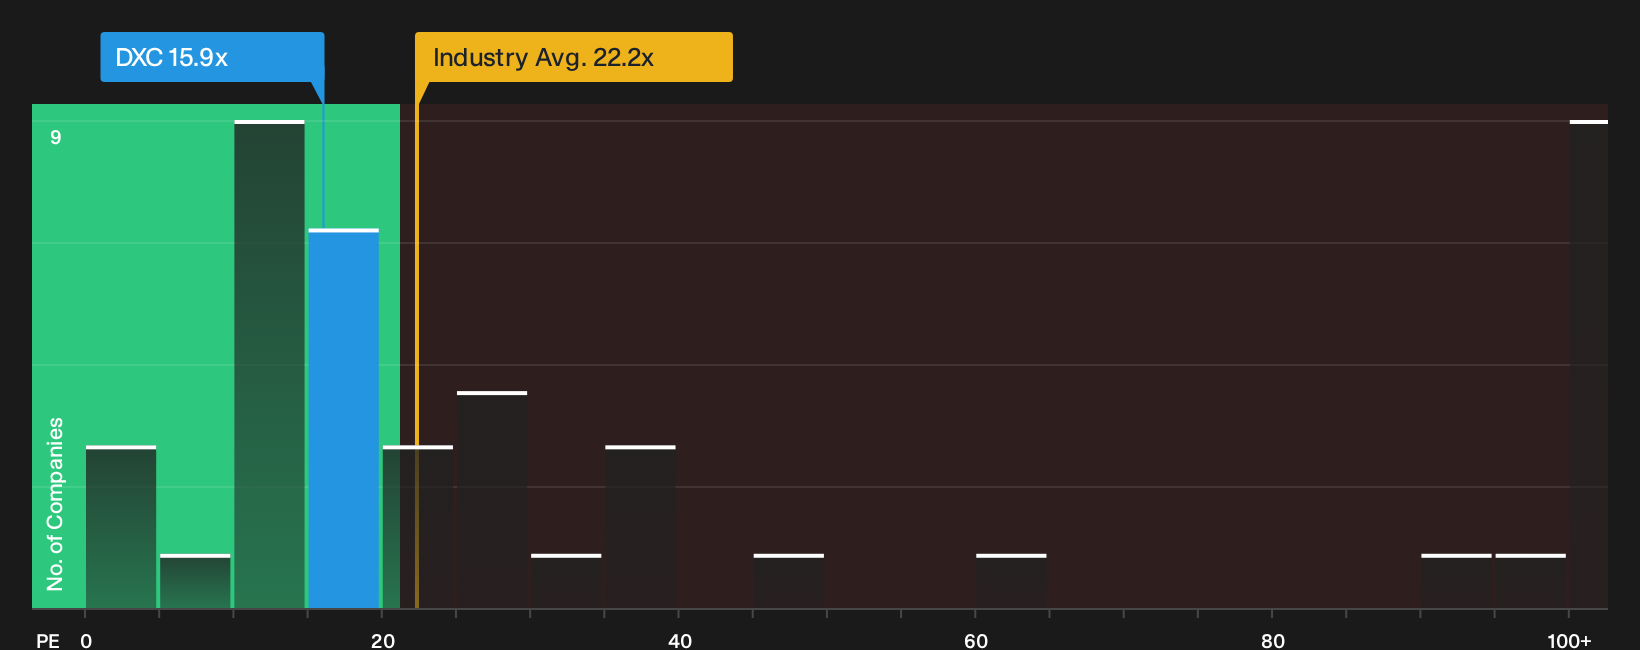
Analyst narratives point to DXC Technology trading about 10% above an $11.21 fair value, yet the market is pricing the stock on a P/E of 15.9x. The fair ratio sits higher at 21.3x, while US IT peers average 22.2x, which implies the market is still pricing in execution risk. If that risk eases, does the gap close, or does the narrative shift instead?
To stress test this earnings based view against the underlying assumptions and see how the fair ratio could change as results come through, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around DXC Technology can create both hesitation and opportunity, so move quickly, review the full picture, and weigh up the 2 key rewards and 3 important warning signs.
Looking for more DXC Technology sized opportunities?
Do not stop at DXC Technology. Broaden your watchlist now with focused stock ideas so you are not chasing the next move after it happens.
- Target potential mispricing by scanning a curated set of quality companies using the 27 high quality undervalued stocks.
- Prioritize resilience by finding businesses with strong finances through the list of solid balance sheet and fundamentals (25 results).
- Hunt for underfollowed potential by checking the 20 high quality undiscovered gems before everyone else turns their attention there.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com