
Ralph Lauren (RL) Could Be 18% Below Fair Value As Growth Narrative Holds
Ralph Lauren (RL) is on investor watch after fresh company data highlighted how its global apparel, accessories, home goods, and fragrance lines contribute to a US$21.5b market value and recent share performance.
Recent trading has been choppy for Ralph Lauren, with the share price at US$367.39 after a 1.73% 1 day gain and a 30 day share price return of 5.81%. The 90 day share price return has declined 6.97%. However, the 1 year total shareholder return of 14.97% and very large 3 and 5 year total shareholder returns point to strong longer term momentum that short term moves only partly reflect.
Scan beyond Ralph Lauren and see how it stacks up against a hand picked 27 high quality undervalued stocks that currently show stronger quality signals on both cash flows and balance sheets.
Ralph Lauren now trades only slightly below one intrinsic value gauge, yet well below the average analyst target. Is the recent share price rebound already fair, or is the gap still doing the heavy lifting in this story?
Most Popular Narrative: 18% Undervalued
On the most followed view, Ralph Lauren shares at $367.39 sit below an implied fair value of $446.71. That gap hinges on how the brand leans into direct to consumer, Asia, and pricing power over time.
Strong digital adoption and a higher mix of direct to consumer activity, with direct to consumer now about 70% of revenue and global retail comps in the low to mid teens, increases exposure to higher margin channels and can support structurally stronger net margins.
Early stage momentum in high potential categories such as women’s apparel, outerwear and handbags, which are growing at more than 20% and already represent a sizeable women’s business with low estimated market share, provides additional product led levers for revenue growth and mix driven operating margin improvement.
See why 26 investors see Ralph Lauren as 18% undervalued.
Result: Fair Value of $446.71 (UNDERVALUED)
Still, the Ralph Lauren narrative can unravel if Europe stays weak on tourism and wholesale partners underperform, which could squeeze margins and reduce that perceived undervaluation.
Find out about the key risks to this Ralph Lauren narrative.
Another View On Ralph Lauren’s Valuation
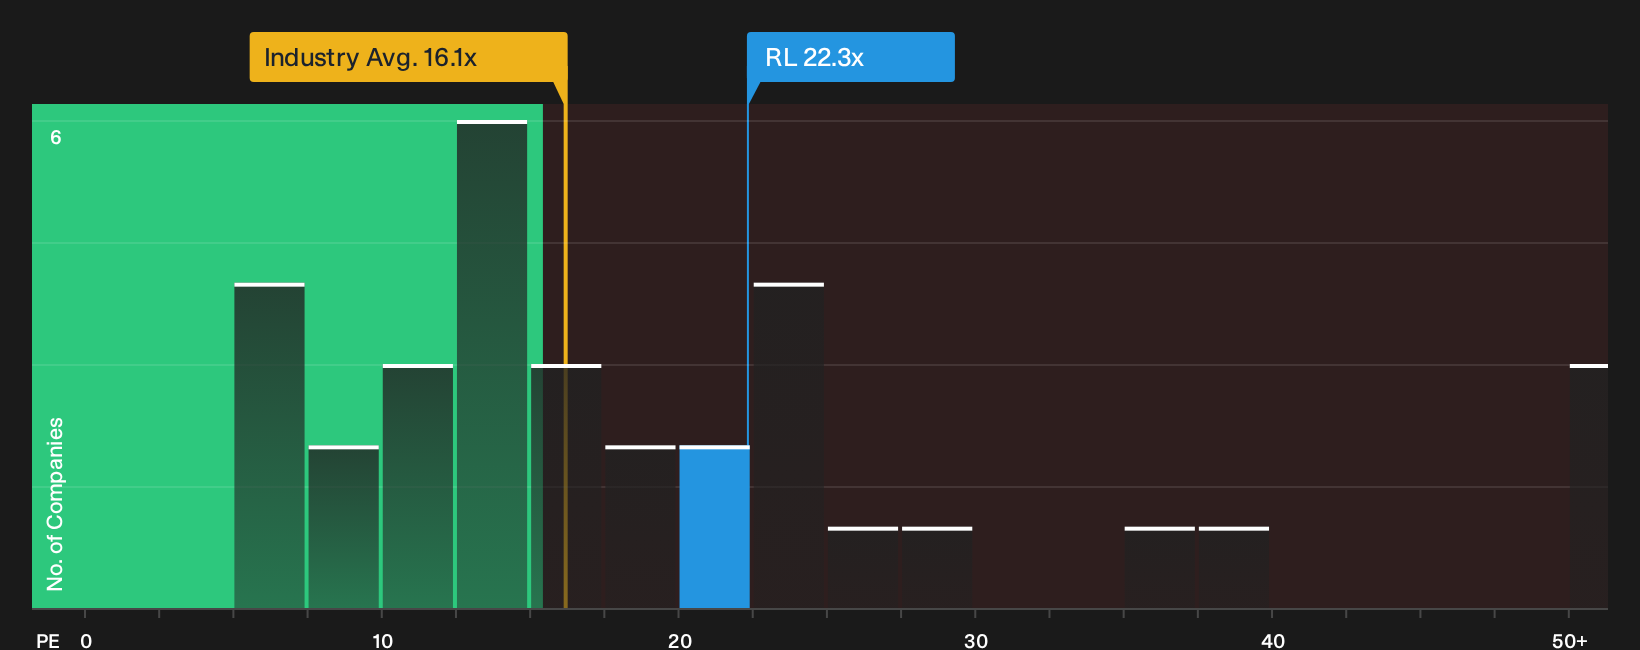
The first story paints Ralph Lauren as undervalued using future cash flows and earnings assumptions. A different lens tells a cooler story. On a P/E of 22.3x, the stock trades well above the US Luxury industry on 16.1x, peers on 15.9x, and even its own fair ratio of 18.4x. That gap points to valuation risk if sentiment or growth expectations soften, rather than obvious upside. Which version of value do you trust more right now?
For a closer look at how this compares with other assessment tools and where the market might eventually gravitate, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Ralph Lauren’s value case so far. Act fast on the fresh numbers, weigh both the upside and the worries, then rely on the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Ralph Lauren?
You have fresh insight on Ralph Lauren. Now put it to work by scanning other opportunities that match your risk appetite, income needs, and quality focus.
- Target potential mispricing and see which companies screen as high quality and trading below estimated worth through the 27 high quality undervalued stocks.
- Build a steadier income stream by reviewing a curated set of higher yielding opportunities in the 8 dividend fortresses.
- Dial down portfolio stress by focusing on businesses that score well on resilience using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com