
3 Australian Growth Stocks With Revenue Growth Up To 37%
AI chip demand is grabbing headlines, with Samsung and TSMC reporting record revenue tied to hardware that powers advanced computing. That kind of technology build out often highlights companies able to grow quickly and reinvest confidently. For Australian investors, this can sharpen interest in local businesses where management and analysts both anticipate continued expansion. This article walks through three such growth stocks from the Australian market.
The three stocks covered next are only a starting sample, since the wider screen surfaced 24 more companies where management and analysts both see strong potential and the full narratives sit outside this short list.
To go broader and identify your own high conviction ideas, head straight into the High Growth High Conviction screener to filter and analyze the full set of High Growth High Conviction opportunities.
Emerald Resources (ASX:EMR)
Emerald Resources is a gold producer focused on the 100% owned Okvau Gold Project in Cambodia, a single asset that anchors its High Growth High Conviction profile. Mine operations generated about A$602 million of its roughly A$612 million revenue, and the group carries a market value near A$4.3b.
Emerald Resources ties directly into the screener theme because almost all of its growth story runs through Okvau, where earnings rose 196.3% last year and net profit margins reached 42.4%. That level of profitability creates clear leverage to what happens when one unseen pressure on funding and expansion shifts.
When funding conditions shift like that, you want to see the DCF valuation analysis for Emerald Resources to gauge how Okvau cash flows compare with the current share price.
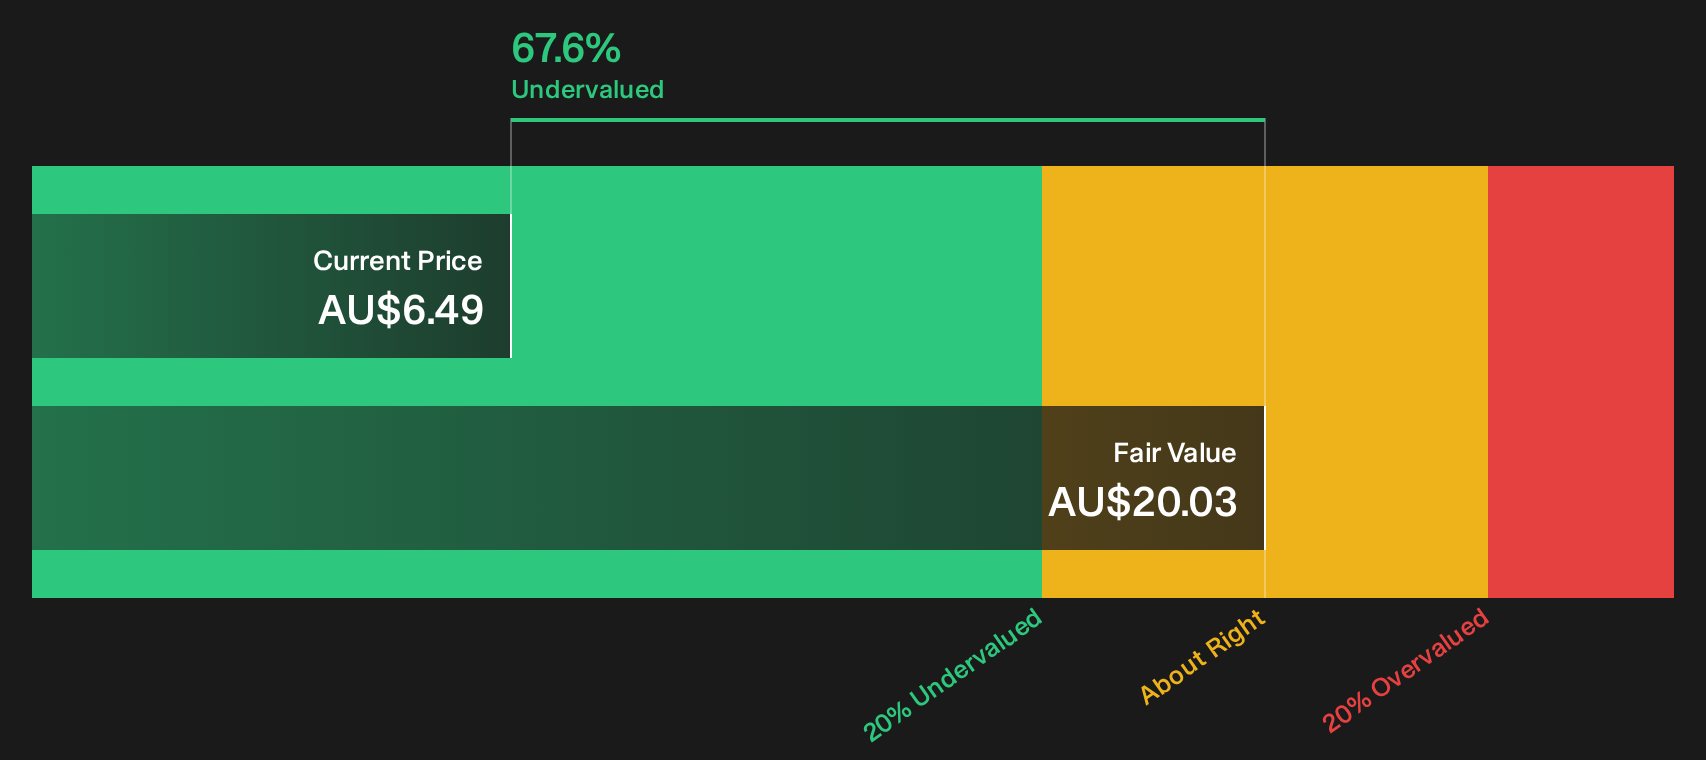
Mesoblast (ASX:MSB)
Mesoblast focuses on regenerative cell therapies that line up directly with the High Growth High Conviction idea, with its remestemcel-L and MPC programs aimed at severe inflammatory and cardiovascular conditions where management is working to turn advanced trials into meaningful commercial traction.
Mesoblast generated about US$120 million from the development and commercialization of its allogeneic cellular medicines platform, and with an Australian market value near A$2.5b it remains a mid-cap biotech that relies heavily on converting late-stage clinical assets into durable revenue.
"The first and only FDA approved mesenchymal stromal cell product in the U.S., Ryoncil, together with over 1,100 patents and established commercial scale manufacturing, positions Mesoblast to benefit if cell therapies gain wider medical adoption."
What matters now is how one pivotal shift in regulatory and clinical outcomes ultimately feeds through into pricing power and long-term earnings quality.
If that shift is what you care about, read the full narrative for Mesoblast to see how Mesoblast’s risk, funding, and pricing power could be pulling in different directions.

Pinnacle Investment Management Group (ASX:PNI)
Pinnacle Investment Management Group builds, distributes, and supports high conviction boutique fund managers through a multi affiliate model, earning A$110 million from funds management operations in Australia and carrying a market value near A$3.2b.
Pinnacle Investment Management Group matters for the High Growth High Conviction theme because its fund services engine is built to help specialist managers scale quickly, which directly ties the business to growth in active strategies rather than just market beta.
"Expansion of international affiliates and clients, with about one third of A$229.4 billion of affiliate FUM now sourced outside Australia and A$75 billion coming from more than 50 countries, can deepen diversification and support a larger revenue base as offshore fee streams build."
What really decides how powerful that opportunity becomes is how one less visible pressure on future fee mix and earnings resilience ultimately plays out.
If that pressure on fee mix is what you are watching, read the full narrative for Pinnacle Investment Management Group to see how Pinnacle Investment Management Group’s growth engine could be accelerating or stalling in the future.

Curious About What You Might Be Missing?
Fresh ideas move first. Breakout trends build momentum while they are still under the radar for now, and slow movers get caught chasing. Scan the next wave and act now.
- Target dependable income streams by reviewing the 5 dividend fortresses before yields start dropping and the most resilient payers get fully priced by everyone else.
- Hunt for future compounders inside the 15 high quality undiscovered gems while these quality operators are still flying below most radars and valuations remain grounded.
- Position ahead of the next AI surge by scanning the 35 profitable AI stocks that aren't just burning cash before momentum traders crowd into the few cash generative leaders.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com