
Amgen (AMGN) In Focus As MariTide Buzz Tests Whether The Stock Is Fully Valued
Amgen (AMGN) is back in focus after fresh attention on its obesity drug candidate MariTide, now in late-stage Phase III testing, and new precision medicine partnerships that together are shaping sentiment toward the stock.
Those headlines are landing on a stock that has already been rebuilding confidence. Amgen’s share price is up 12.12% over 90 days and 24.36% year to date, while its 1-year total shareholder return of 41.74% points to strong, dividend-backed momentum rather than a short-lived pop.
Scan how other drug developers with similar momentum and pipelines stack up beside Amgen by running the hand picked 27 high quality undervalued stocks.
After a 41.74% 1 year total return and a share price near $407, the question around Amgen now is simple: Is the bigger payoff already in the rearview, or is valuation still leaving room ahead?
Most Popular Narrative: 13% Overvalued
On Simply Wall St’s most followed narrative, Amgen’s fair value sits at $359.98 compared with the recent $407.44 share price, which frames the current enthusiasm as already generous.
The "Amgen 2027 Bull Case" relies on a classic top-line fallacy: assuming that macro obesity market growth and FDA's CNPV (Commissioner’s National Priority Voucher) tailwinds will automatically trigger a re-rating.
Here is the cold, data-driven reality:
1. CNPV solves regulatory speed, not the manufacturing bottleneck. Amgen lacks the massive, domestic GLP-1 supply chain infrastructure that Lilly and Novo command. Fast-tracked approval without scale-up capacity only accelerates market-share caps.
2. The consensus ignores the regulatory friction. The CNPV pilot program is facing severe legal durability and structural transparency questions in mid-2026. Betting a 2027 thesis on an unstable, non-statutory policy is a high-risk gamble.
3. Competitors are already using the exact same playbook. Novo Nordisk already secured its Wegovy HD approval via CNPV in March 2026. Amgen is a latecomer trying to enter a crowded arena where the incumbents already hold the fast-track tokens.
4. The timeline mismatch is real. MariTide's commercial ramp-up will take years post-launch, while Amgen’s high-margin legacy moats (Prolia and Enbrel) are already eroding at a brutal -30%+ YoY clip right now.
Amgen is priced for flawless execution, leaving zero margin of safety for the structural vacuum underneath its valuation. AMGN is a speculative premium hiding a legacy erosion.
See why 6 investors see Amgen as 13% overvalued.
Result: Fair Value of $359.98 (OVERVALUED)
Still, that bearish story could be shaken up if Amgen shows durable earnings from its broad immunology and oncology portfolio, or surprises on MariTide manufacturing scale.
Find out about the key risks to this Amgen narrative.
Another View: Amgen On Earnings-Based Value
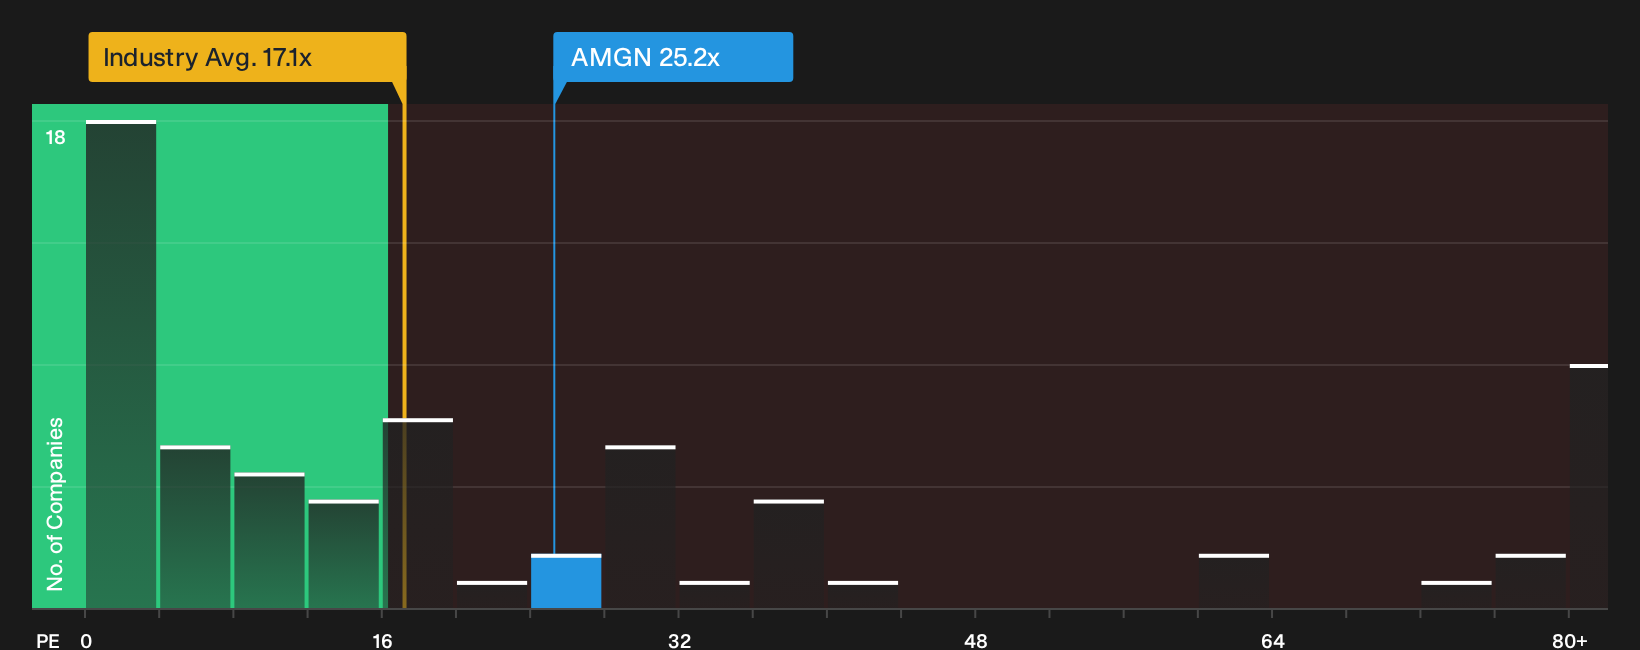
The first narrative paints Amgen as 13% overvalued on a fair value of $359.98 versus the $407.44 share price. Using earnings instead, the picture changes. A P/E of 25.2x is below a fair ratio of 31.5x and far under a 40.4x peer average. This points to valuation risk looking very different depending on which lens is used.
This kind of gap can suggest room for the market to move closer to the fair ratio or for sentiment to cool toward higher growth biotech peers. Investors may consider which side of that tradeoff they prefer to emphasize in their portfolios.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around Amgen feels finely balanced, consider acting while sentiment is still forming and pressure test the numbers yourself with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Amgen?
Do not stop with Amgen. Fresh opportunities are constantly emerging, and a few focused stock lists can help you pressure test your next moves with real discipline.
- Target dependable income by scanning companies that aim to support meaningful payouts with the 8 dividend fortresses.
- Hunt for potential mispricing by reviewing financially strong businesses that still trade on appealing terms through the 27 high quality undervalued stocks.
- Dial down portfolio risk by focusing on companies with sturdier finances and cleaner balance sheets using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com