
Is Rare Disease Approval Altering The Investment Case For Incyte (INCY)?
- Incyte and Mirum Pharmaceuticals reported that the U.S. FDA previously approved Atebrioz (zilurgisertib), an oral ALK2 inhibitor for Fibrodysplasia Ossificans Progressiva in patients aged 12 and older, and granted Incyte a Rare Pediatric Disease Priority Review Voucher.
- The approval of Atebrioz adds a rare disease product and a transferable FDA voucher to Incyte’s toolkit. This development could influence how the business funds and prioritizes its planned shift toward a broader, multi-franchise portfolio beyond Jakafi.
- We will now examine how Incyte's investment narrative could be influenced by Atebrioz's approval and the awarded Priority Review Voucher.
Compare Incyte's rare disease pivot with other potential breakout stories by scanning our curated list of 20 high quality undiscovered gems that may be flying under most investors' radar.
Incyte Investment Narrative Recap
To own Incyte, you need to be comfortable with a transition story. The business is still heavily tied to Jakafi, while management is working to build a multi franchise portfolio across dermatology, hematology, rare disease and GI oncology. The Atebrioz approval fits this plan but, on its own, does not change the near term dependence on existing oncology and dermatology products.
The most important short term swing factor remains how effectively Incyte ramps its newer launches and controls rising R&D and SG&A. The biggest risk is that elevated spending, including recent deals, weighs on margins if newer assets underperform. Atebrioz and the voucher help diversify, although they do not remove that execution risk.
Among recent updates, the scheduled third quarter 2026 earnings release and call on October 29 is the key near term event. For anyone tracking Incyte, that call is where management can clarify how Atebrioz and the Rare Pediatric Disease Priority Review Voucher fit into broader revenue and spending plans.
You will want to listen for any discussion of how rare disease contributions might offset expected pressure from Jakafi loss of exclusivity and accelerating development costs. Commentary on cash deployment, potential voucher monetization and any refinement to guidance could give you a clearer sense of whether the Atebrioz approval meaningfully shifts the balance between catalysts and margin risk.
Incyte's current analyst narrative points to revenues of US$5.8b and earnings of US$1.2b by 2029, with earnings expected to decline by US$0.4b from US$1.6b today, while overall revenue is described as remaining fairly flat over the next 3 years.
Uncover why Incyte's fair value indicates a 14% potential upside to its current price that may not last much longer.
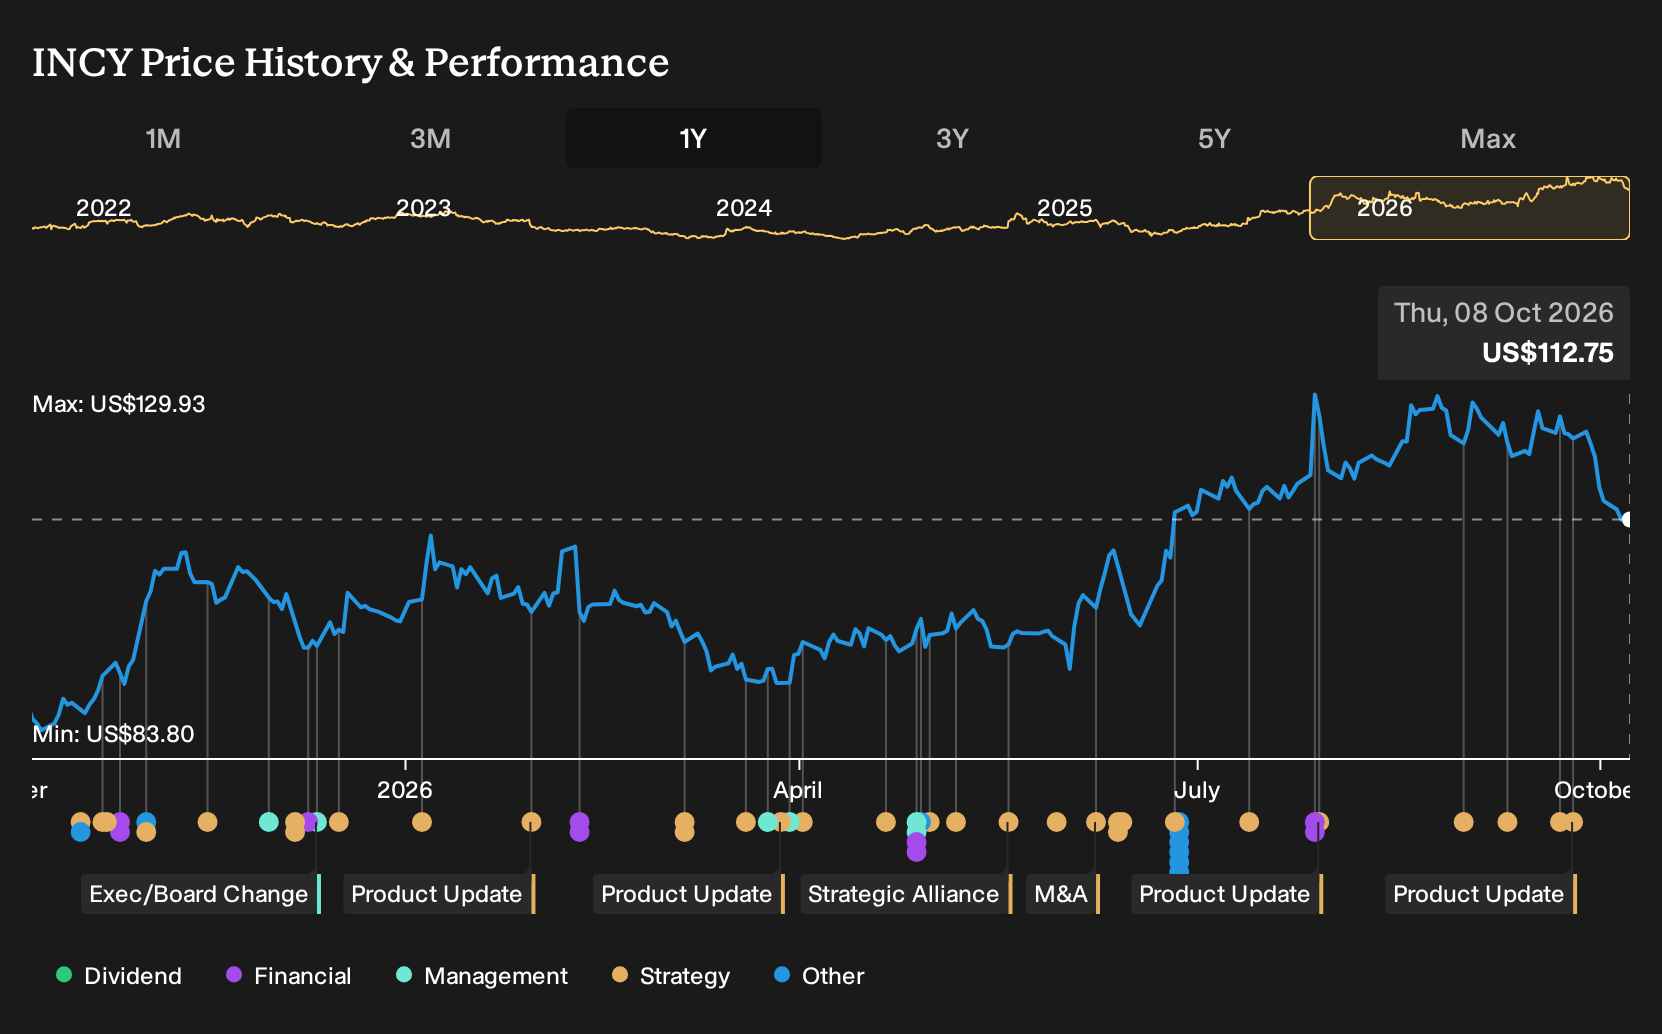
Exploring Other Perspectives
Some of the lowest Incyte forecasts lean heavily on the risk that rising R&D and SG&A, including the roughly US$1.27b Vega outlay, could squeeze profits. Those analysts were modeling revenue of about US$5.4b and earnings of US$1.2b by 2029. They present a more cautious story that might shift once Atebrioz and the voucher are fully discussed.
Explore 4 other Incyte fair value estimates, including one that suggests as much as 17% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Incyte research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Incyte. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Incyte's overall financial health at a glance.
Looking For More Investment Ideas Beyond Incyte?
Once you have a handle on Incyte's setup around Atebrioz and the wider portfolio shift, it can help to widen the lens and compare it with other potential opportunities using the Simply Wall St screener.
- If you are hunting for quality at a discount, line up candidates using the 27 high quality undervalued stocks and see which businesses offer stronger fundamentals at current prices.
- If balance sheet strength is your filter, narrow your watchlist with the list of solid balance sheet and fundamentals (25 results) and focus on companies with more resilient financial footing.
- If you prefer cash returns today, scan income ideas through the 8 dividend fortresses and zero in on higher yielding payers with room in your portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com