
How Management Reshuffle At Aker BP (OB:AKRBP) Has Changed Its Investment Story
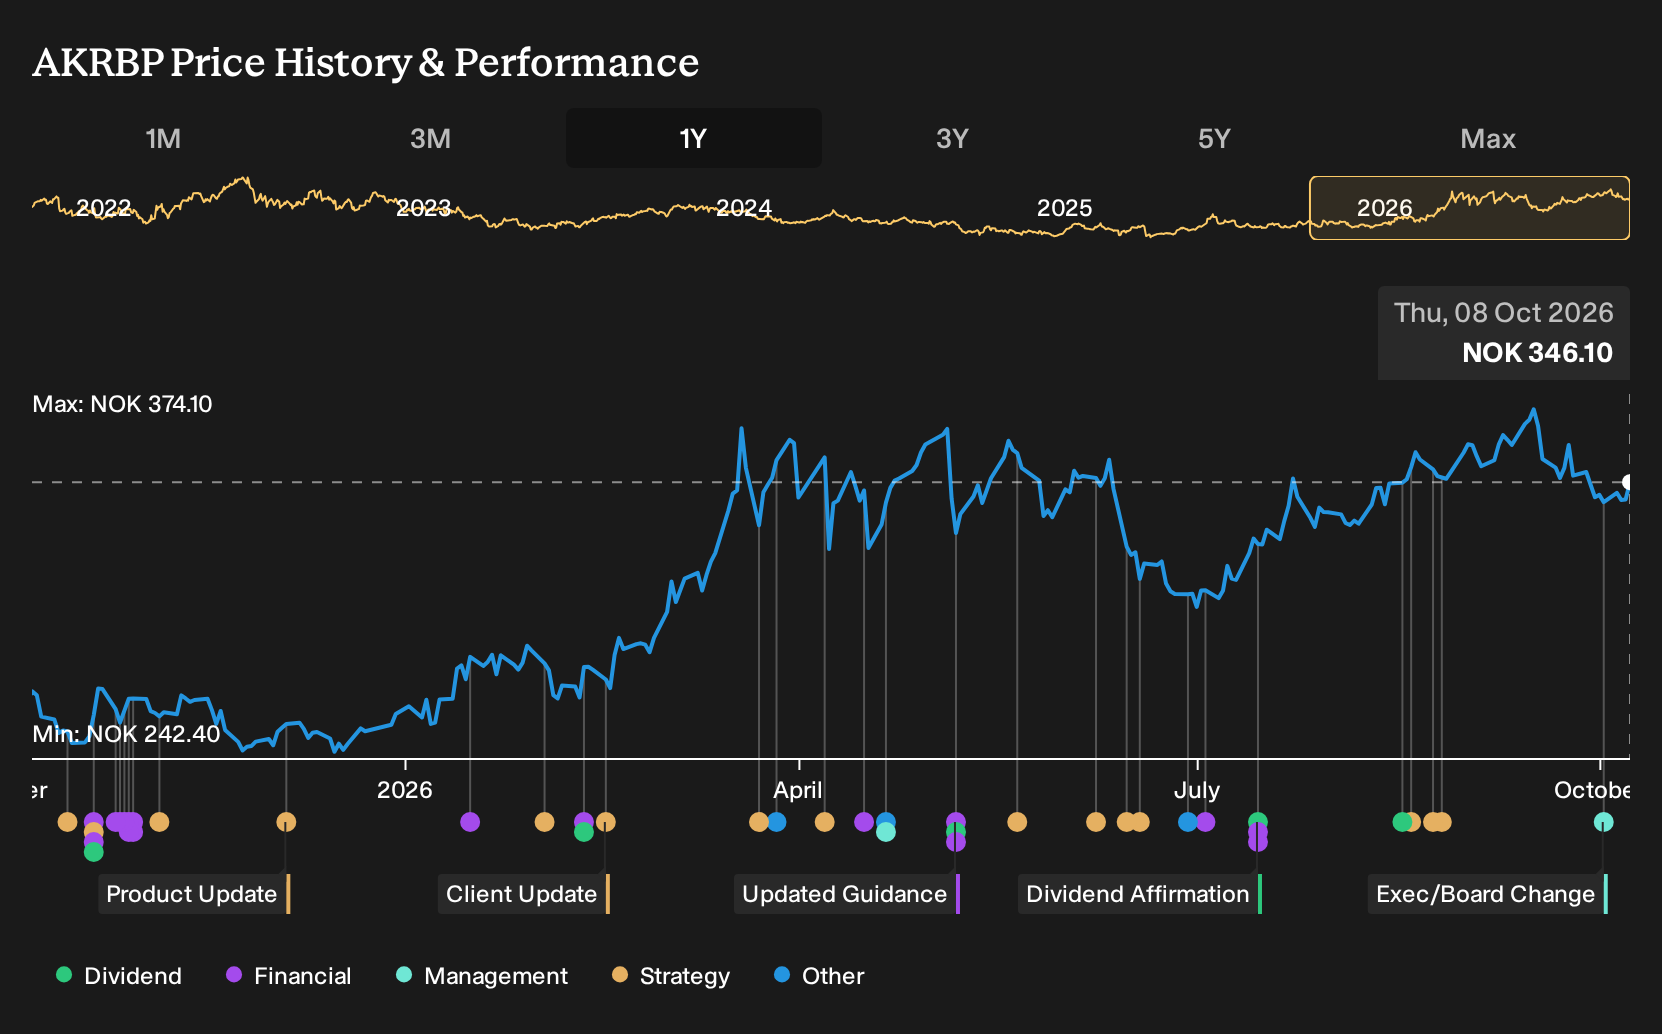
- Aker BP has set a new executive management line up that takes effect in January 2027. It is built around its full oil and gas value chain and is intended to simplify decision making from exploration through to production and optimisation.
- The leadership refresh leans heavily on Aker BP’s long running use of industrial data and artificial intelligence, aiming to embed digital tools directly into how projects are designed, built and operated across the Norwegian Continental Shelf.
- Next, the focus turns to how Aker BP’s revamped value chain led management structure could reshape the investment narrative that analysts built before this announcement.
Aker BP Investment Narrative Recap
To own Aker BP, you need to be comfortable with a concentrated Norwegian Continental Shelf producer that relies on large hubs like Johan Sverdrup and on big projects such as Yggdrasil and Wisting. The key near term catalyst still sits in execution on these developments and in keeping production and operating uptime tight around existing assets.
The new value chain focused executive team may help project delivery and digital execution over time, but the announcement itself does not materially shift those near term drivers. The biggest risk remains project delays, cost pressure and emissions related costs combining with high debt and a dividend that is not well covered by free cash flow.
The management reshuffle builds directly on Aker BP’s long running push into digital tools, including Agile Asset Management and the ACE toolkit. These systems are already aimed at cutting downtime and keeping operating costs in check. Folding them into a clearer “find, build, produce, optimise” leadership structure keeps the focus on turning that digital work into practical results on the fields.
That matters for your catalyst and risk homework. The investment case leans on large, capital intensive projects and a balance sheet that carries meaningful borrowing while paying a dividend flagged as thinly covered. Execution discipline, cost control and steady uptime are the levers that support that setup, so this organisational move mainly looks like an operational bet on doing those basics more consistently.
What The New Aker BP Setup Means For The Numbers
Aker BP's narrative projects $13.4b revenue and $1.8b earnings by 2029. This implies 4.1% yearly revenue growth and an earnings increase of about $0.4b from $1.4b today.
Uncover why Aker BP's fair value indicates a 5% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate angle on Aker BP is the very optimistic view that the real catalyst is faster project execution, powered by its data and AI push. Those bullish analysts were already pencilling in about $15.4b of revenue and $2.2b in earnings by 2029. This management overhaul could prompt those projections, and the more cautious ones, to shift again. Readers should compare both sets of expectations and decide which story feels closer to their own view.
Explore 5 other Aker BP fair value estimates, including one that suggests there could be as much as 84% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Aker BP research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Aker BP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aker BP's overall financial health at a glance.
Looking For More Investment Ideas Beyond Aker BP?
If the Aker BP story has sharpened your view on risk, balance sheets and project execution, use that same lens to scan a wider field. The Simply Wall St Screener lets you filter for the kind of financial profile you want, then compare ideas side by side before you commit any fresh capital.
- For investors who want quality at a sensible entry point, start with companies flagged as 179 high quality undervalued stocks and see which ones line up with your return and risk expectations.
- If resilience matters most to you, focus on businesses highlighted as 225 resilient stocks with low risk scores and check how their balance sheets and earnings profiles stack up against Aker BP.
- If you prefer to hunt for lesser known stories with solid fundamentals, filter for opportunities tagged as 620 high quality undiscovered gems and build a shortlist worth deeper research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com