
Our Pick Of The Best British Growth Stocks In October 2026
AI chip spending is grabbing headlines after Samsung projected a very large jump in quarterly profit, reminding investors how quickly new technology cycles can reward early believers. That kind of sudden momentum often lifts confidence in high growth stories more broadly. For UK growth hunters, this is a chance to focus on companies where both analysts and management see strong potential. This article highlights three such high conviction UK stocks.
The stocks covered below are just a sample from this High Growth High Conviction idea, and the full screen surfaced 2 more UK companies with similarly punchy growth stories that are not discussed in the article. To go straight to the full list and identify, compare, and analyze the highest conviction setups in one place, head into the High Growth High Conviction screener.
Beauty Tech Group (LSE:TBTG)
Beauty Tech Group focuses on premium at home beauty devices that fit the High Growth High Conviction theme, with CurrentBody Skin contributing about £147.8 million, ZIIP Beauty £14.6 million and Tria Laser £3 million in revenue. The business is valued at roughly £499.1 million.
Beauty Tech Group combines trailing profit growth of 271.3% and 5 year earnings growth of 90.1% a year with a focused play on at home devices that management and analysts both support. Investor interest now centres on how one currently unseen pressure may influence future pricing power.
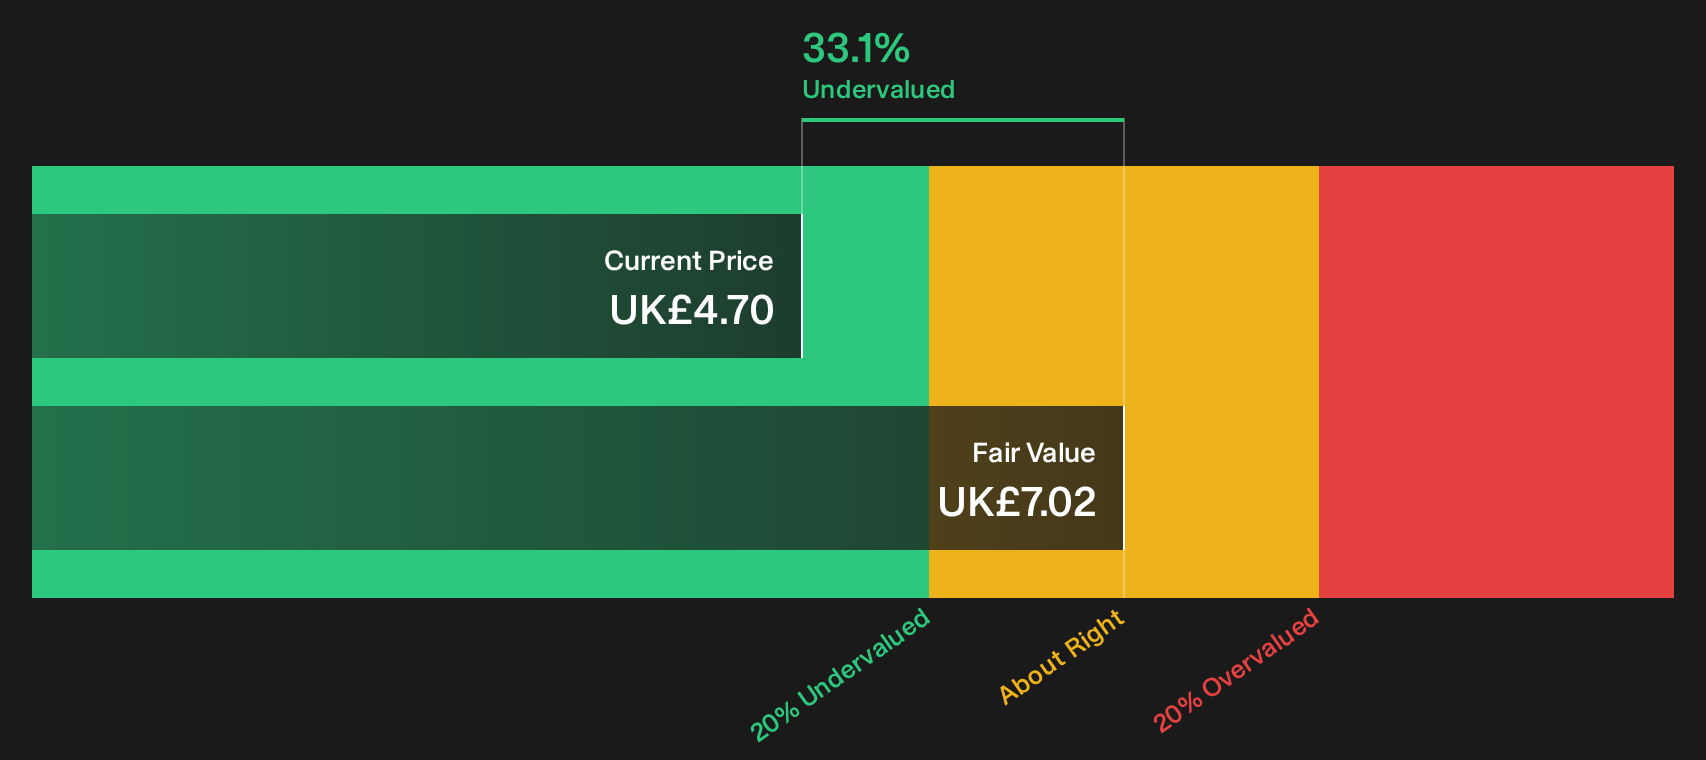
To see how that pressure shows up in the numbers, go straight to the DCF valuation analysis for Beauty Tech Group and judge whether Beauty Tech Group’s pricing power already looks fully baked in.
TEAM (AIM:TEAM)
TEAM plc runs investment management, advisory, and insurance broking operations from Jersey, with the high conviction investment and fund management arm generating about £1.7 million of the £13 million group total, alongside £8.5 million from International and £2.8 million from Advisory, on a market cap of roughly £18 million.
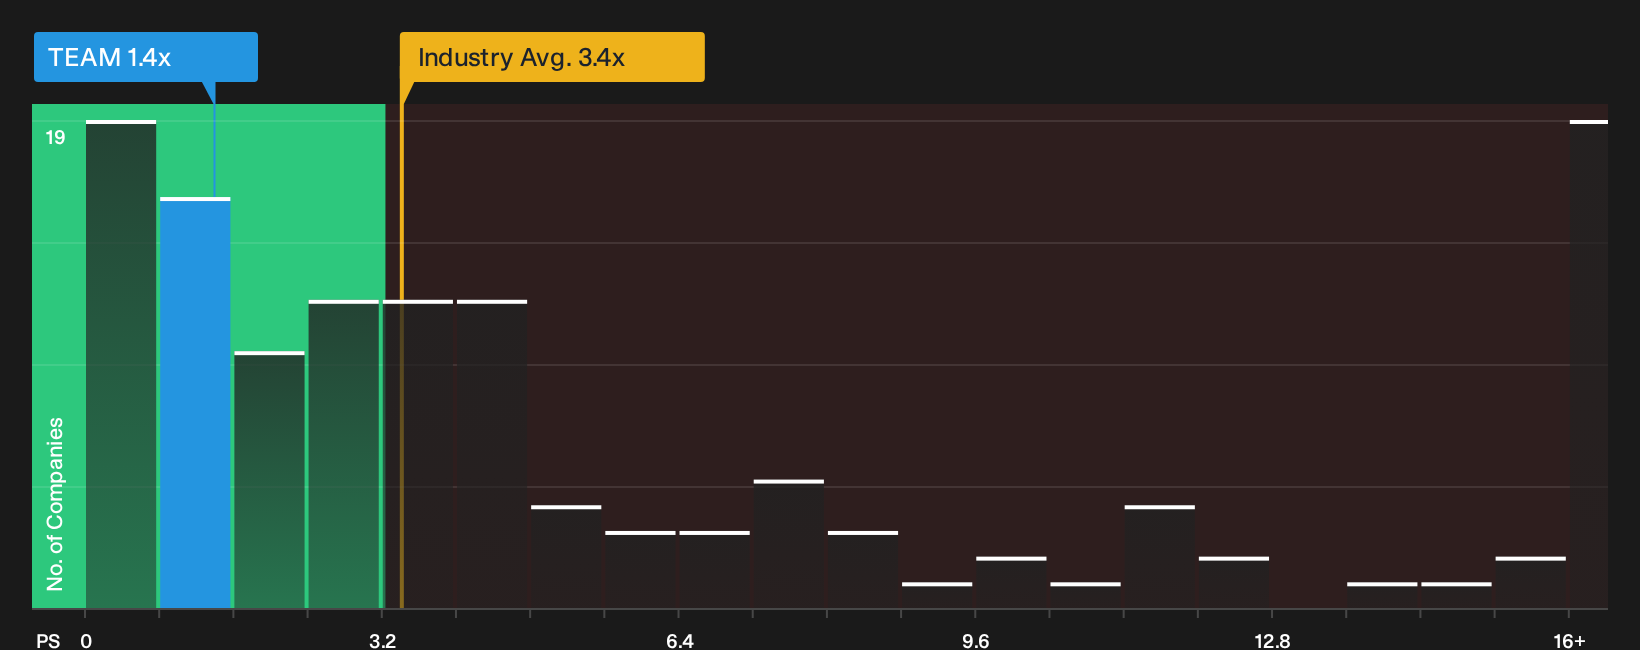
TEAM focuses on the High Growth High Conviction theme through its discretionary and model portfolios. According to available forecasts, earnings are expected to rise 85.28% a year and revenue 20.6% a year. A P/S of 1.4x compared with peers on 3.4x suggests potential for sentiment to change, depending on how one unresolved funding and dilution overhang develops.
That funding overhang is exactly what the 1 key reward and 1 important major warning sign unpacks, so you can see where enthusiasm and dilution risk might be pulling apart.
Motorpoint Group (LSE:MOTR)
Motorpoint Group runs an omnichannel dealership for nearly new cars in the UK, tying directly into the High Growth High Conviction theme through its online and physical retail of vehicles under six years old. Retail generated about £1.1b of the £1.3b total, with £137.8 million from Wholesale, on a market cap near £110.3 million.
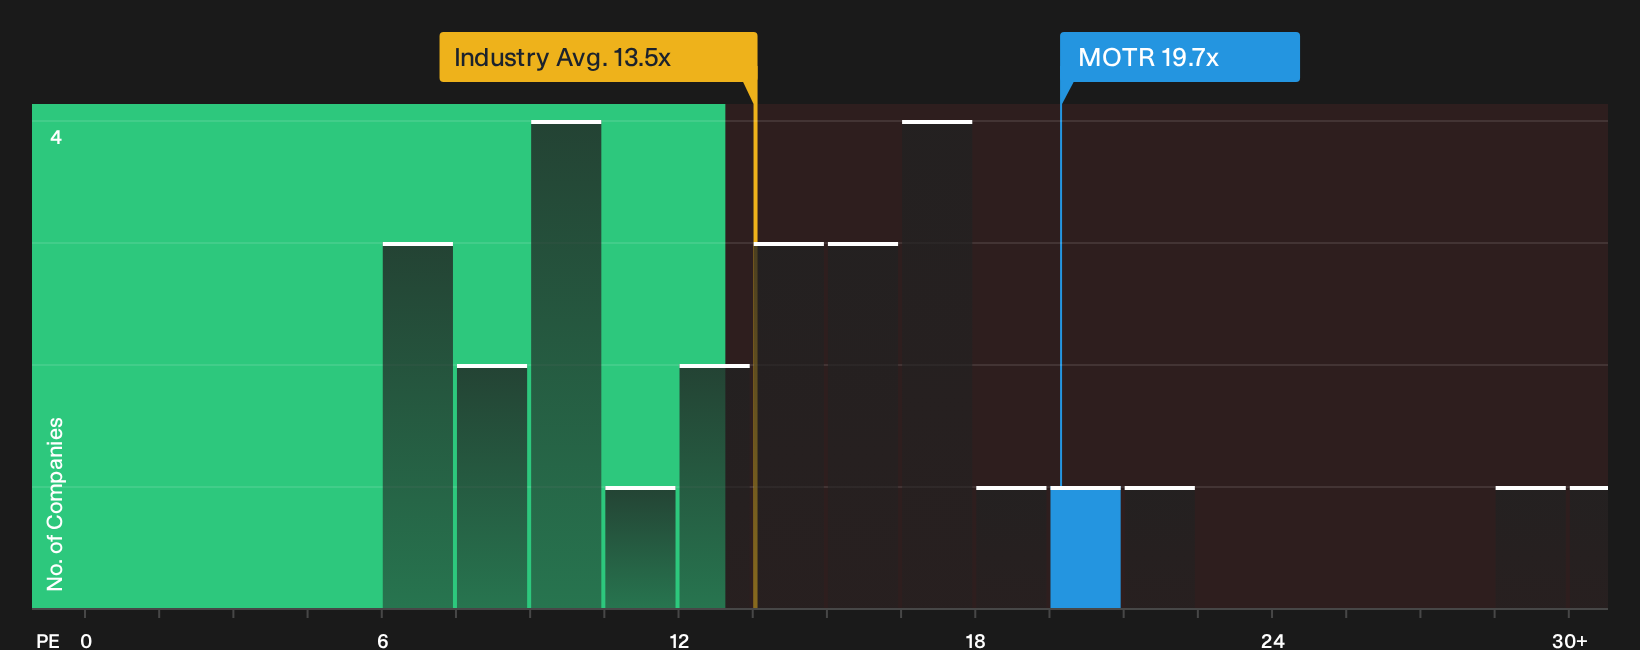
Motorpoint Group plugs into the High Growth High Conviction theme through its focus on nearly new vehicles. A 19.7x P/E against lower peer multiples means sentiment on this growth story leans heavily on what happens when one pressure on margins and funding costs shifts.
When that margin and funding pressure finally shifts, the analysis report for Motorpoint Group shows how Motorpoint Group’s earnings power and valuation story could realign fast.
Seeking Alternatives Before The Crowd?
Fresh momentum can move fast. Breakout potential often gets spotted early, then pricing flies once the crowd catches up. Look under the radar for now, and consider acting before sentiment shifts widely.
- Identify resilient cash generators before income-focused investors increase their interest by scanning the curated 4 dividend fortresses that aim to keep payouts flowing while prices are still dropping.
- Target resilient balance sheets and disciplined execution with a focused review of the list of solid balance sheet and fundamentals (9 results) while these quality operators are still priced for hesitation.
- Explore the next leg of AI-related momentum by running through the hand picked 91 AI infrastructure stocks and look for infrastructure plays before additional capital enters the sector.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com