
PACS Group (PACS) Enters Florida, But Does The Undervalued Narrative Still Hold?
PACS Group enters Florida with 32 facility transition
PACS Group (PACS) just stepped into Florida in a bigger way, taking over 32 skilled nursing facilities that Omega Healthcare Investors shifted from a prior operator effective 1 October 2026.
The move incorporates these properties into PACS Group’s existing master lease with Omega, adds new rental obligations tied to scheduled increases, and broadens the operator’s geographic reach in skilled nursing.
The Florida expansion lands while momentum in PACS Group’s shares has been building, with a 7 day share price return of 6.58% and a year to date share price return of 10.68% at a US$43.73 close.
Over the past year, the total shareholder return of about 2.3x suggests investors have rapidly re-rated the stock, and the recent uptick in share price performance indicates that the market is treating facility growth as a fresh catalyst rather than a source of added risk.
Scan other healthcare operators showing similar momentum and expansion traits to PACS Group by checking our curated list of solid balance sheet and fundamentals (25 results), which may highlight companies positioned to handle growth without over-stretching their finances.
PACS Group now has a bigger footprint, a higher rent bill, and a share price that has already moved. Does that create a more attractive entry point today, or favor investors who wait for a lower price?
Most Popular Narrative: 27% Undervalued
PACS Group's most followed narrative pegs fair value at $59.75, which sits well above the recent $43.73 close and frames the Florida deal as one more test of its expansion playbook.
Rising demand for post-acute and long-term care from an aging U.S. population, combined with PACS Group's expanding footprint of over 35,000 beds, creates room for continued top line growth as occupancy and patient volumes increase, supporting higher revenue and earnings.
See why 12 investors see PACS Group as 27% undervalued.
The fair value estimate is built using a 7.5% discount rate and assumes PACS Group reaches $7.2b of revenue and $461.5m of earnings by 2029, with the stock trading on a P/E multiple of 26.3x at that point. That set of expectations implies investors are being asked to pay today for a business that can grow earnings, lift margins from current levels, and sustain a valuation slightly richer than the broader US Healthcare industry.
Analysts who support this narrative highlight several operational swing factors, including the turnaround potential in recently acquired facilities, the impact of Medicaid and quality incentive frameworks in key states, and the ability of PACS Group's locally led model to move newer cohorts closer to the profitability profile of mature sites. On the other side of the ledger sit meaningful risks, such as execution strain from rapid portfolio growth, policy changes in large reimbursement markets, and any return of governance or internal control concerns following the earlier short seller episode.
For an investor weighing the Florida transition, the key question is whether those underlying assumptions still hold, given PACS Group now has a larger, more complex estate and a history of very rapid portfolio additions in 2024 and 2026. If integration runs smoothly and newer facilities move toward higher occupancy and better skilled mix, the narrative fair value of $59.75 may look grounded in the operating trajectory the business is already pursuing. If ramping cohorts stay stuck at lower margins or policy support softens in core states, the current gap between price and that fair value estimate could narrow for the wrong reasons.
Result: Fair Value of $59.75 (UNDERVALUED)
Still, the PACS Group story can change quickly if the integration of the large cohort of newer facilities drags on or if key Medicaid reimbursement frameworks shift unfavorably.
Find out about the key risks to this PACS Group narrative.
Another View: PACS Group Through The P/E Lens
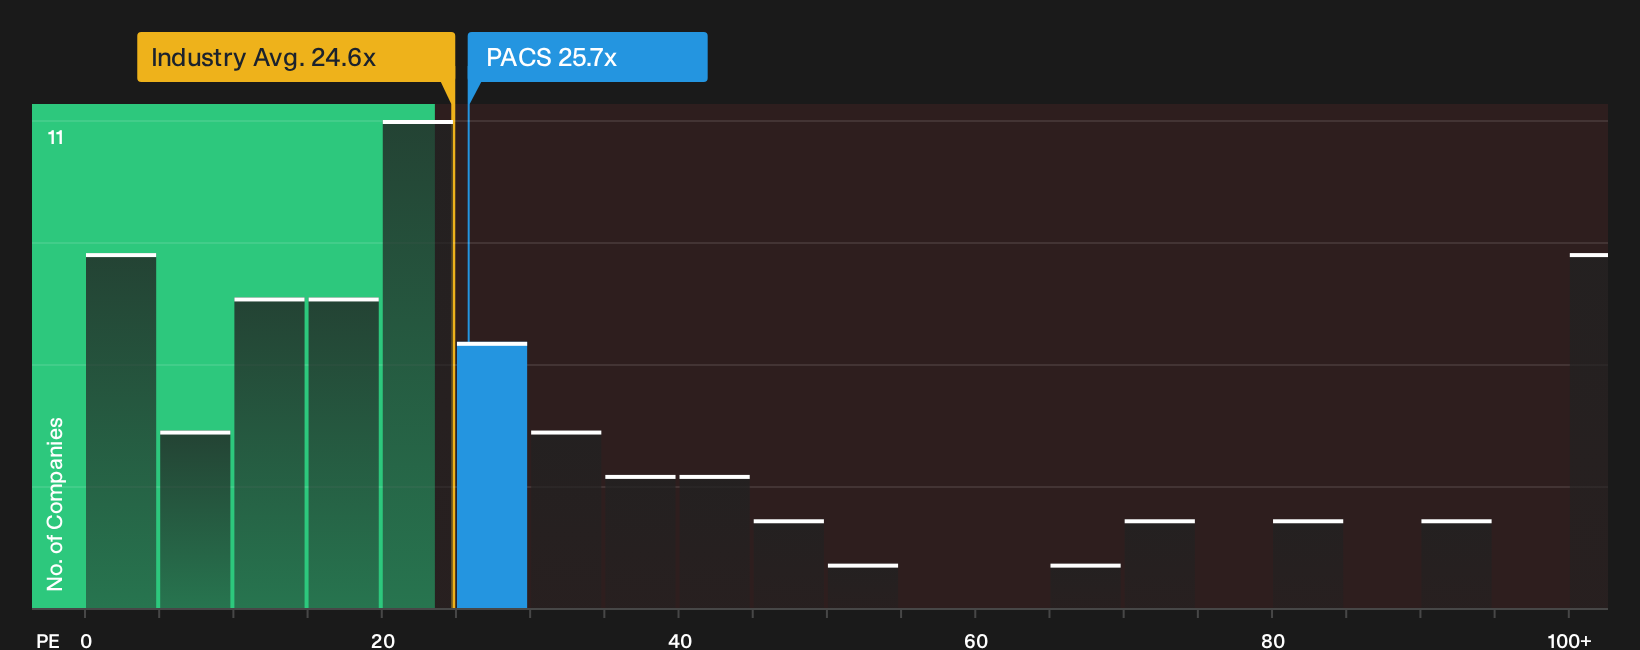
The DCF narrative points to upside for PACS Group, but the simple earnings multiple tells a different story. The stock trades on a P/E of 25.7x, which is richer than both the US Healthcare sector at 24.6x and its peer group on 19.2x, even though PACS only scores 2 out of 6 on value checks.
A fair ratio of 39.7x suggests the market could justify paying far more for each dollar of earnings if sentiment or assumptions shift. Yet today investors are already accepting a premium to the sector and peers. Is that premium enough, or too much, given the growth and risk profile you see?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mix of optimism and caution around PACS Group feels finely balanced, consider acting promptly and stress test it against your own expectations by checking the 3 key rewards and 1 important warning sign.
Looking for more PACS Group style investment ideas?
Do not stop your research with PACS Group. A broader watchlist can surface opportunities you will wish you had seen earlier.
- Target resilient businesses that aim to protect downside risk by scanning our focused 31 resilient stocks with low risk scores.
- Hunt for strong fundamentals at prices that look reasonable using the carefully filtered 20 high quality undiscovered gems.
- Zero in on balance sheets that appear built to handle shocks and growth by working through the curated list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com