
Permanent Billing Codes Might Change The Case For Investing In Medtronic Stock
- Medtronic reported that the American Medical Association approved new Category I CPT codes for its Altaviva tibial neuromodulation implant and Symplicity Spyral renal denervation system, with the permanent codes scheduled to take effect in January 2028.
- The move from temporary Category III to permanent Category I CPT codes signals that these Medtronic procedures meet AMA criteria for being well established, widely performed, and supported by substantial clinical evidence. This can inform how physicians and payers treat these therapies operationally.
- We will look at how Medtronic's investment narrative evolves as Altaviva and Symplicity Spyral gain permanent Category I CPT reimbursement footing.
Scan how Medtronic fits into a broader basket of device makers by lining it up against 32 healthcare AI stocks targeting big clinical problems with technology driven solutions.
Medtronic Investment Narrative Recap
To own Medtronic, you need to believe its mix of chronic disease therapies, connected surgical platforms and neuromodulation can justify steady mid single digit revenue gains and improving profitability over time. The AMA decision on Altaviva and Symplicity Spyral strengthens that longer term story, but the codes only take effect in 2028, so the near term demand picture barely shifts.
The more immediate swing factors still look familiar. Execution on higher growth cardiovascular and neuroscience franchises remains the key catalyst. Margin pressure from lower margin units, lingering structural heart softness and litigation costs around Covidien mesh products remain front of mind as the biggest operational risks.
The AMA upgrade of Altaviva and Symplicity Spyral to permanent Category I CPT codes is the announcement that most directly affects the current story. It reinforces that both procedures have broad clinical acceptance and evidence behind them, which can help physicians and payers treat them as part of routine care over time.
For you as an investor, this sits alongside the planned MiniMed diabetes separation, robotics platforms and renal denervation push as part of the same puzzle. The opportunity is a portfolio that leans more toward higher vitality therapies, while the execution test is whether Medtronic holds margins as mix shifts and underperforming areas such as structural heart are addressed.
Medtronic's current analyst narrative points to revenues of US$42.8b and earnings of US$7.1b by 2029, based on assumed yearly top line growth of 4.4% and an earnings increase of about US$1.9b from US$5.2b today.
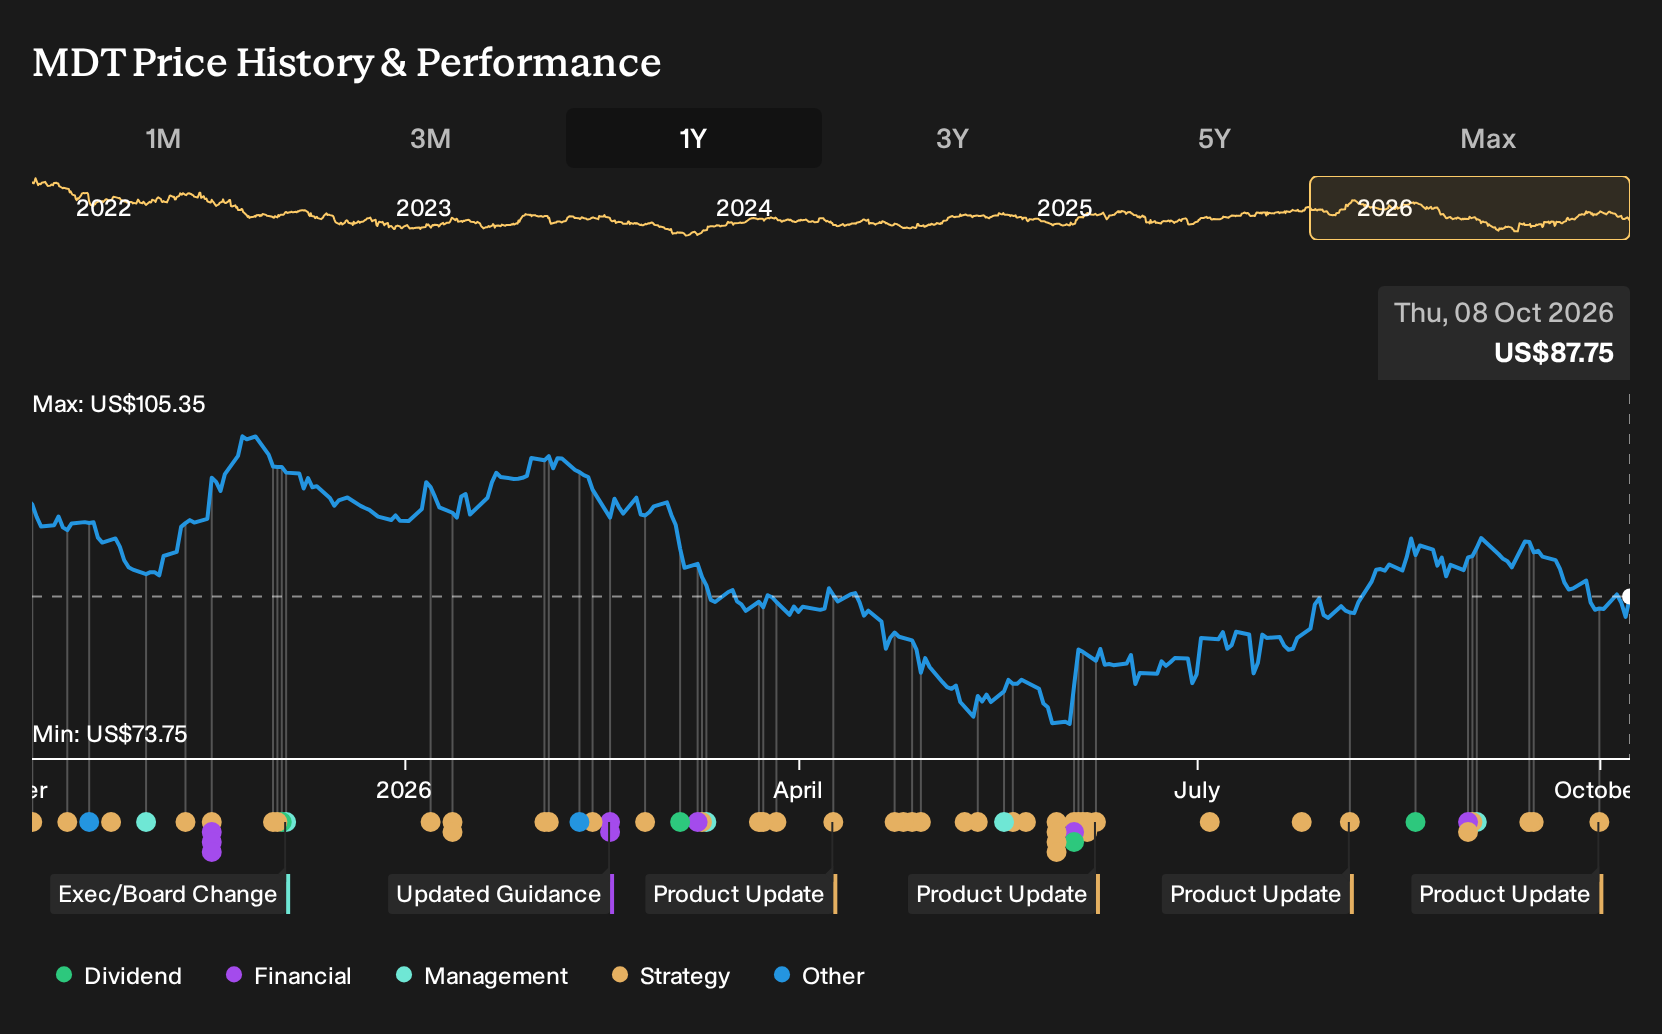
Uncover why Medtronic's fair value indicates a 19% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Symplicity Spyral as the swing factor. Before this AMA news, they were already penciling in US$44.1b of 2029 revenue and US$7.1b of earnings, much higher than bearish views. You can treat today’s CPT decision as a fresh data point that might push those narratives in new directions.
Explore 9 other Medtronic fair value estimates, including one that suggests as much as 31% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Medtronic research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Medtronic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Medtronic's overall financial health at a glance.
Looking For More Ideas Beyond Medtronic?
Once you have a view on Medtronic, it can help to compare it with other opportunities that match your risk tolerance, income needs, and time horizon. The Simply Wall St Screener lets you filter the market quickly so you spend more time assessing businesses and less time hunting for tickers.
- If you want potential income from dividends to play a bigger role in your plan, scan a curated set of companies with resilient payouts through the 8 dividend fortresses.
- For readers who care most about capital preservation and steadier business profiles, focus on a 31 resilient stocks with low risk scores that filters for stronger balance sheets and more stable fundamentals.
- Those looking for mispriced quality can sift through a 27 high quality undervalued stocks that highlights businesses combining solid cash generation with attractive valuations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com