
East West Bancorp (EWBC) Could Be 16% Undervalued Following Its 33% Dividend Lift
East West Bancorp (EWBC) has drawn fresh attention after a sizable 33.3% uplift in its annualized dividend, along with expectations for earnings growth in the coming fiscal year and a favorable research rating.
Recent trading suggests interest is building rather than fading. The share price return is up 9.73% year to date, and the 1 year total shareholder return of 23.4% sits alongside a very large 3 year total shareholder return, helped by dividends and price gains around East West Bancorp.
Scan how East West Bancorp’s dividend move compares with other income ideas by reviewing a curated mix of 8 dividend fortresses in the market right now.
After a sharp dividend reset and a strong total return record, East West Bancorp now poses a simple question to investors: Do you pay a higher price after this move, or wait for a more attractive entry point offering the same earnings and income profile?
Most Popular Narrative: 16% Undervalued
Measured against the narrative fair value of $150, East West Bancorp’s last close at $126.25 leaves a sizeable valuation gap that hinges on how its funding mix, credit discipline, and fee income story play out over the next few years.
Very strong capital levels and efficiency, with East West Bancorp generating mid to high teens return on tangible common equity on a tangible common equity ratio above 10% and maintaining a sub 40% efficiency ratio, give it room to keep funding organic growth initiatives and product expansion that can support future earnings.
See why 25 investors see East West Bancorp as 16% undervalued.
Result: Fair Value of $150 (UNDERVALUED)
Still, the East West Bancorp story depends on cheap, sticky deposits and relatively steady fee income, and pressure on either could quickly challenge that 16% undervalued thesis.
Find out about the key risks to this East West Bancorp narrative.
Another View on East West Bancorp’s Valuation
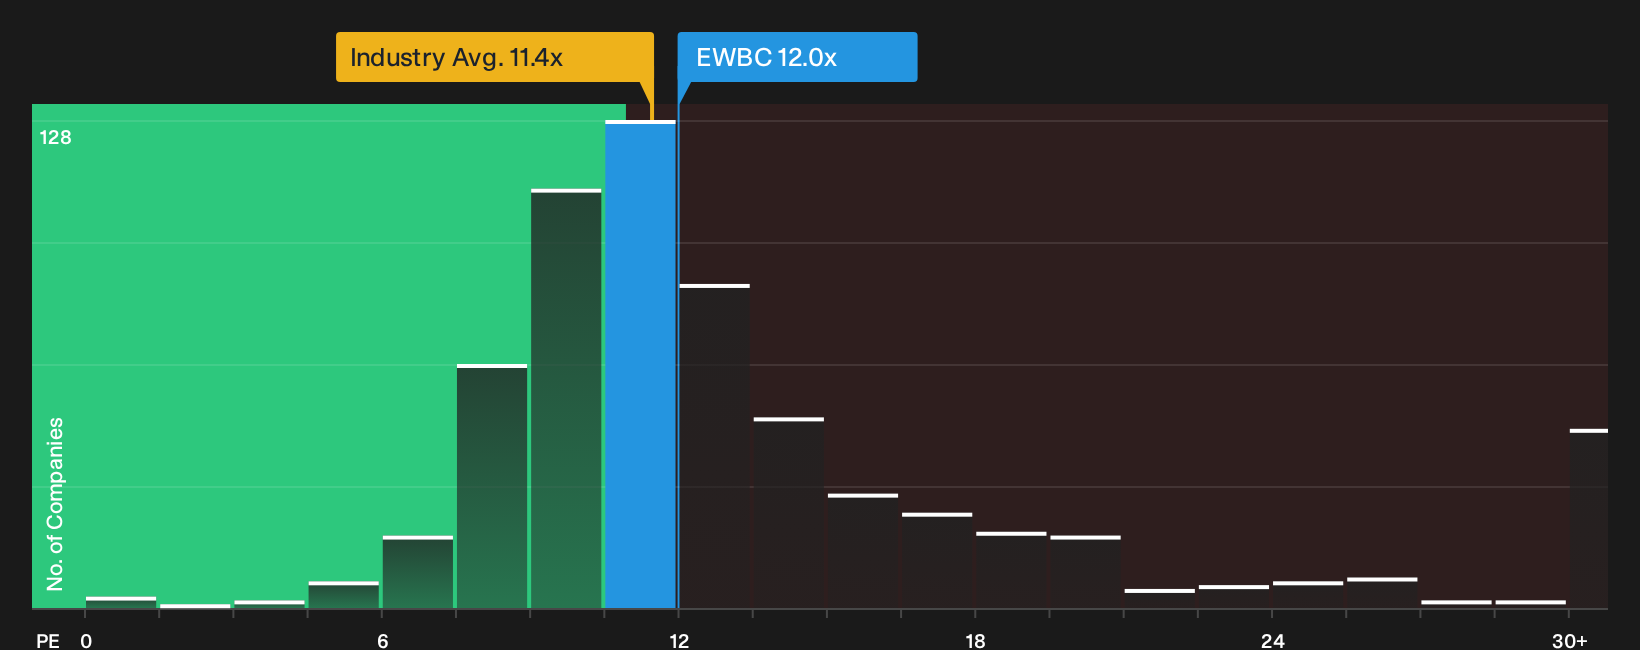
The first narrative leans on a fair value of $150, yet East West Bancorp currently trades on a P/E of about 12x. That is higher than the US Banks industry at 11.4x, while sitting just under a fair ratio of 12.2x and below peers on 13.4x. Does that mix of slight premium to the sector but discount to peers suggest mispricing, or a fair compromise on risk and reward for you?
See what the numbers say about this price in more detail by reviewing See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages or a clear signal for East West Bancorp? Act while the data is fresh and pressure test the balance of 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond East West Bancorp?
Do not stop with one opportunity. Broaden your watchlist using the Simply Wall Street Screener to spot fresh income, quality, and value ideas before others catch on.
- Target potential mispricing by scanning a curated pool of 27 high quality undervalued stocks that combine solid fundamentals with prices that may not fully reflect their financial profile.
- Prioritise resilience and sleep-better-at-night holdings by focusing on 31 resilient stocks with low risk scores that aim to keep balance sheets and volatility in tighter check.
- Hunt for under-the-radar stories by reviewing 20 high quality undiscovered gems that have sound metrics yet limited attention from broader market participants.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com