
49% Undervalued? NextVision Stabilized Systems (TASE:NXSN) Following Its $3.5 Million Order
NextVision Stabilized Systems (TASE:NXSN) just reported a fresh US$3.5 million order from an existing customer for its stabilized cameras and accessories, with staged payments and delivery expected by the end of Q1 2027.
Despite the fresh order, NextVision Stabilized Systems is trading at ₪193.8 after a 1-day share price return of 2.54%, with the stock down 19.92% over the past week and 19.38% over 90 days, even as the 1-year total shareholder return is 28.7% and the 3-year total shareholder return is approximately 7 times the original investment.
Scan how NextVision Stabilized Systems compares with other defense and robotics plays by reviewing our curated list of 88 robotics and automation stocks before the next round of contract news hits the market.
So the question for NextVision Stabilized Systems now is blunt: Does this pullback after a fresh US$3.5 million order already offer a fair entry, or does waiting for an even cheaper price make more sense?
Most Popular Narrative: 49% Undervalued
At a last close of ₪193.8 against a widely followed fair value estimate of ₪379.67, the current pullback in NextVision Stabilized Systems is being framed by the dominant narrative as a wide discount that leans heavily on long term demand for its stabilized camera payloads.
The high order backlog of about $2.089b, most of it tied to the next 12 months and some extending to 2027 to 2029, provides multi year visibility that can support planning, pricing discipline and utilization of fixed assets, which tends to be supportive for gross margins and net margins.
See why 3 investors see NextVision Stabilized Systems as 49% undervalued.
Result: Fair Value of ₪379.67 (UNDERVALUED)
Still, the bullish NextVision Stabilized Systems story hinges on continued defense spending and successful capacity expansion. Any policy shift or underused factories could quickly challenge that narrative.
Find out about the key risks to this NextVision Stabilized Systems narrative.
Another View: Valuing NextVision Stabilized Systems On Earnings
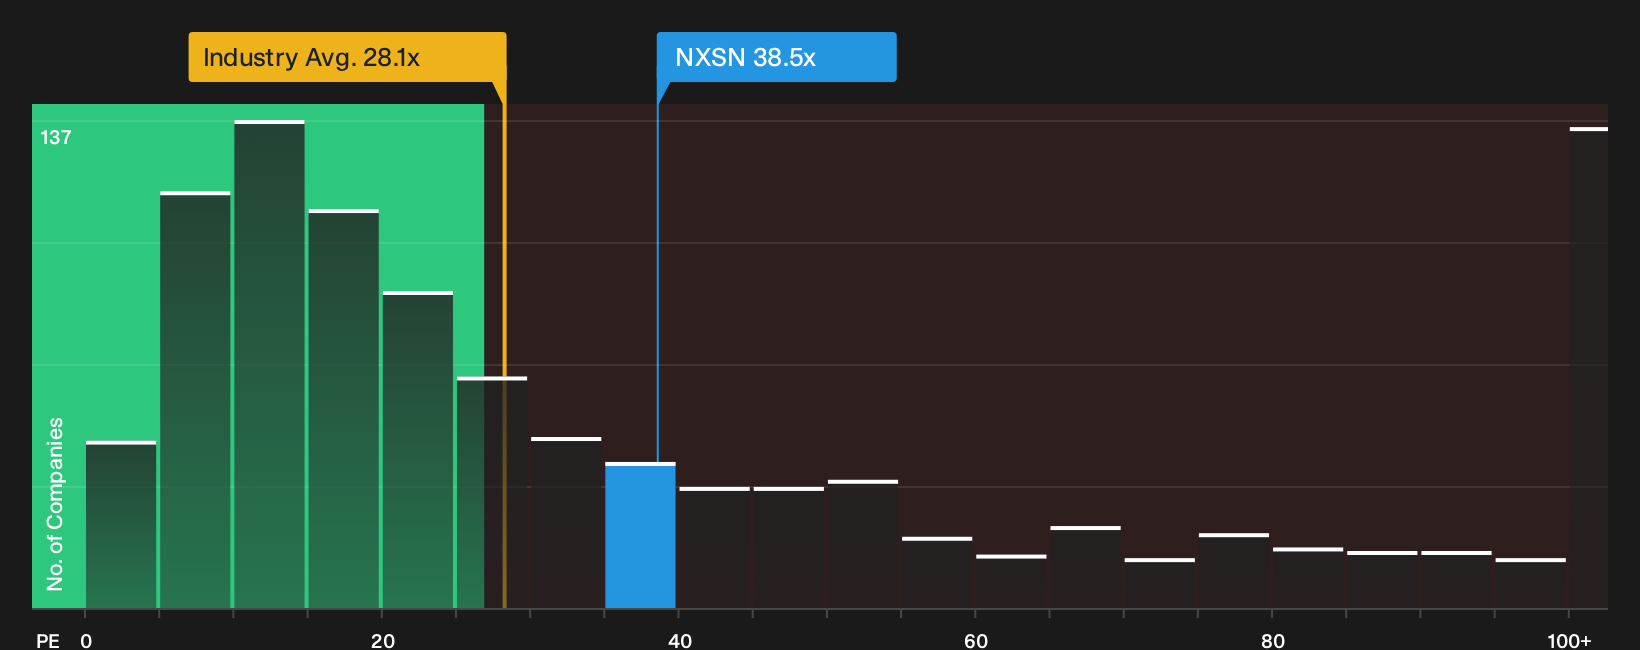
There is a catch. On earnings multiples, NextVision Stabilized Systems trades on a P/E of 38.5x, richer than both its peer group at 24.3x and the wider Asian Electronic sector at 28.1x. This pushes valuation risk in the opposite direction of the fair value narrative.
If the market gradually leans back toward those lower P/E anchors, how comfortable are you with paying a higher multiple today for that growth story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around NextVision Stabilized Systems is clearly split, and that kind of tension is often where the most interesting decisions sit for investors. If you want to move quickly and build your own view rather than lean entirely on the crowd, start with the balance of 3 key rewards and 2 important warning signs.
Looking for more ideas beyond NextVision Stabilized Systems?
If you stop at NextVision Stabilized Systems, you risk missing other mispriced stories and stronger balance sheets that could round out your portfolio.
- Target resilience with companies that pair healthy finances and staying power through our list of solid balance sheet and fundamentals (206 results).
- Hunt for quality at a discount by scanning the 179 high quality undervalued stocks that combine robust fundamentals with attractive pricing.
- Spot early stage potential by reviewing the 117 elite penny stocks with strong financials that still show solid underlying financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com