
3 Australian AI Stocks With Revenue Growth Up To 28%
AI chip demand is exploding, with Samsung reporting a very large profit jump as data centres race to secure hardware. That surge in spending filters through to smaller Australian companies building software, automation tools and data platforms that run on this new infrastructure. Missing this wave could mean missing the early compounding years. This article breaks down three AI-focused Australian small caps from our screener that are worth a closer look.
The three stocks below are just a sample, with the full AI small caps screen surfacing 8 more businesses with equally compelling narratives that are not covered here.
If you want to identify potential front runners early, head straight to the AI Small Caps screener to filter and analyze which AI small caps best fit your own highest conviction ideas.
Pureprofile (ASX:PPL)
Pureprofile is a data and insights business that helps brands run online research through its own platforms and services, including Datarubico, an AI-enabled tool that generates synthetic responses and social insights. It earns A$65 million from Data & Insights and has a market cap of about A$34 million.
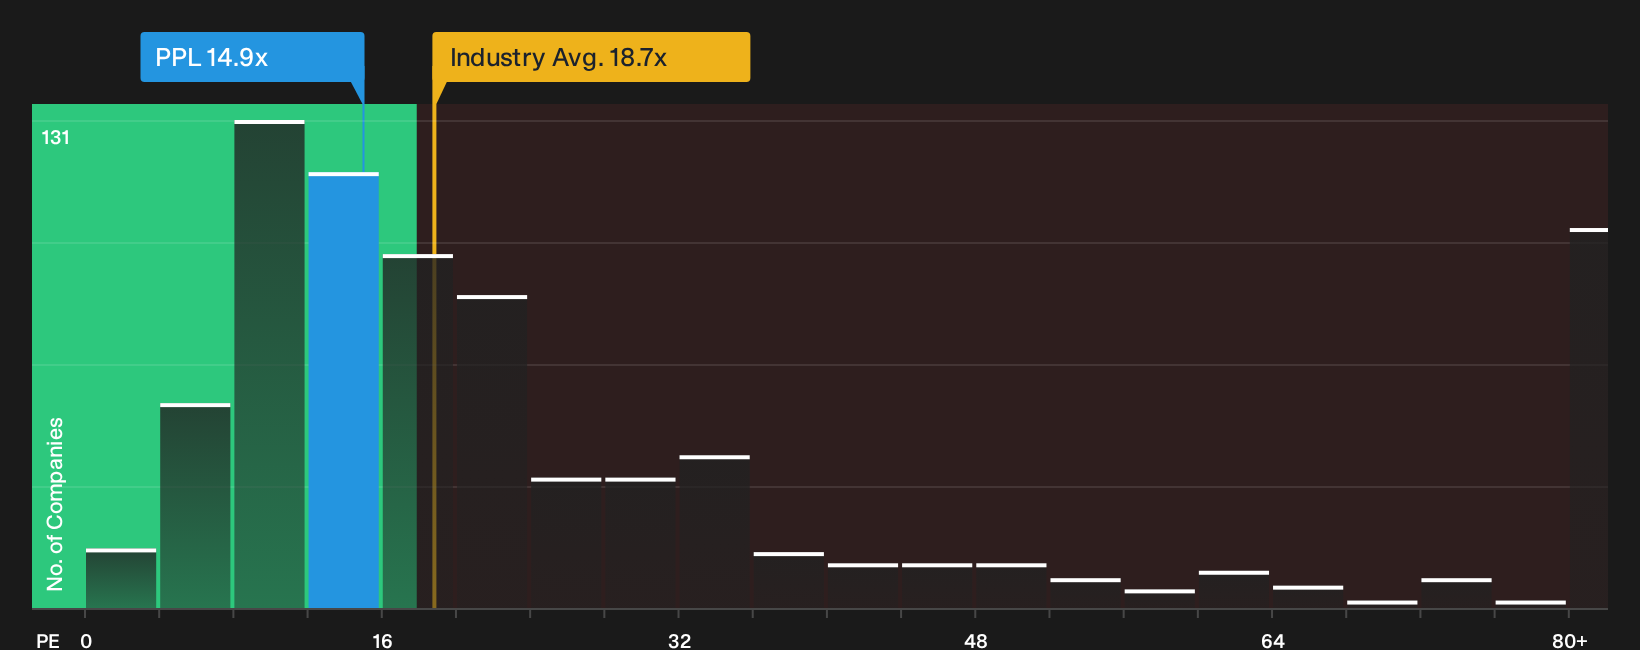
Pureprofile plugs directly into the AI Small Caps theme through Datarubico, where machine learning powers automated audience segmentation and synthetic survey responses for marketers. Revenue of A$65 million and net income of A$2.26 million indicate a commercial engine behind the AI pitch. Its P/E of 14.9x, compared with higher IT sector averages, shows how the market is currently valuing the business.
That valuation gap is the whole question, so weigh it against the DCF valuation analysis for Pureprofile to see what the market might be missing on the upside or the risk side.
Dicker Data (ASX:DDR)
Dicker Data is a wholesale IT distributor that supplies everything from Copilot+ PCs to data center hardware and cloud software, giving it a direct line into AI infrastructure spend. It generated A$2.57b from computer peripherals and has a market cap of about A$2.86b.
For the AI Small Caps theme, Dicker Data matters because it is one of the wholesalers feeding Copilot+ PCs, servers, storage and other gear into the real workloads that run machine learning in Australia and New Zealand, even if this AI line sits within a much broader distribution business.
"Expansion into AI infrastructure and solutions, including the delivery of Australia's first AI factory in partnership with Dell and further AI pipeline opportunities, aligns the company with enterprise digital transformation and creates potential upside for advanced solutions revenue, especially as AI adoption grows across Australia and New Zealand."
The key variable is how one quiet pressure on Dicker Data’s profitability shapes future appetite for funding AI driven hardware and software demand.
That profitability squeeze is only the start, with the full narrative for Dicker Data unpacking how Dicker Data’s AI exposure could accelerate while core distribution trends quietly shift beneath the surface.

Data#3 (ASX:DTL)
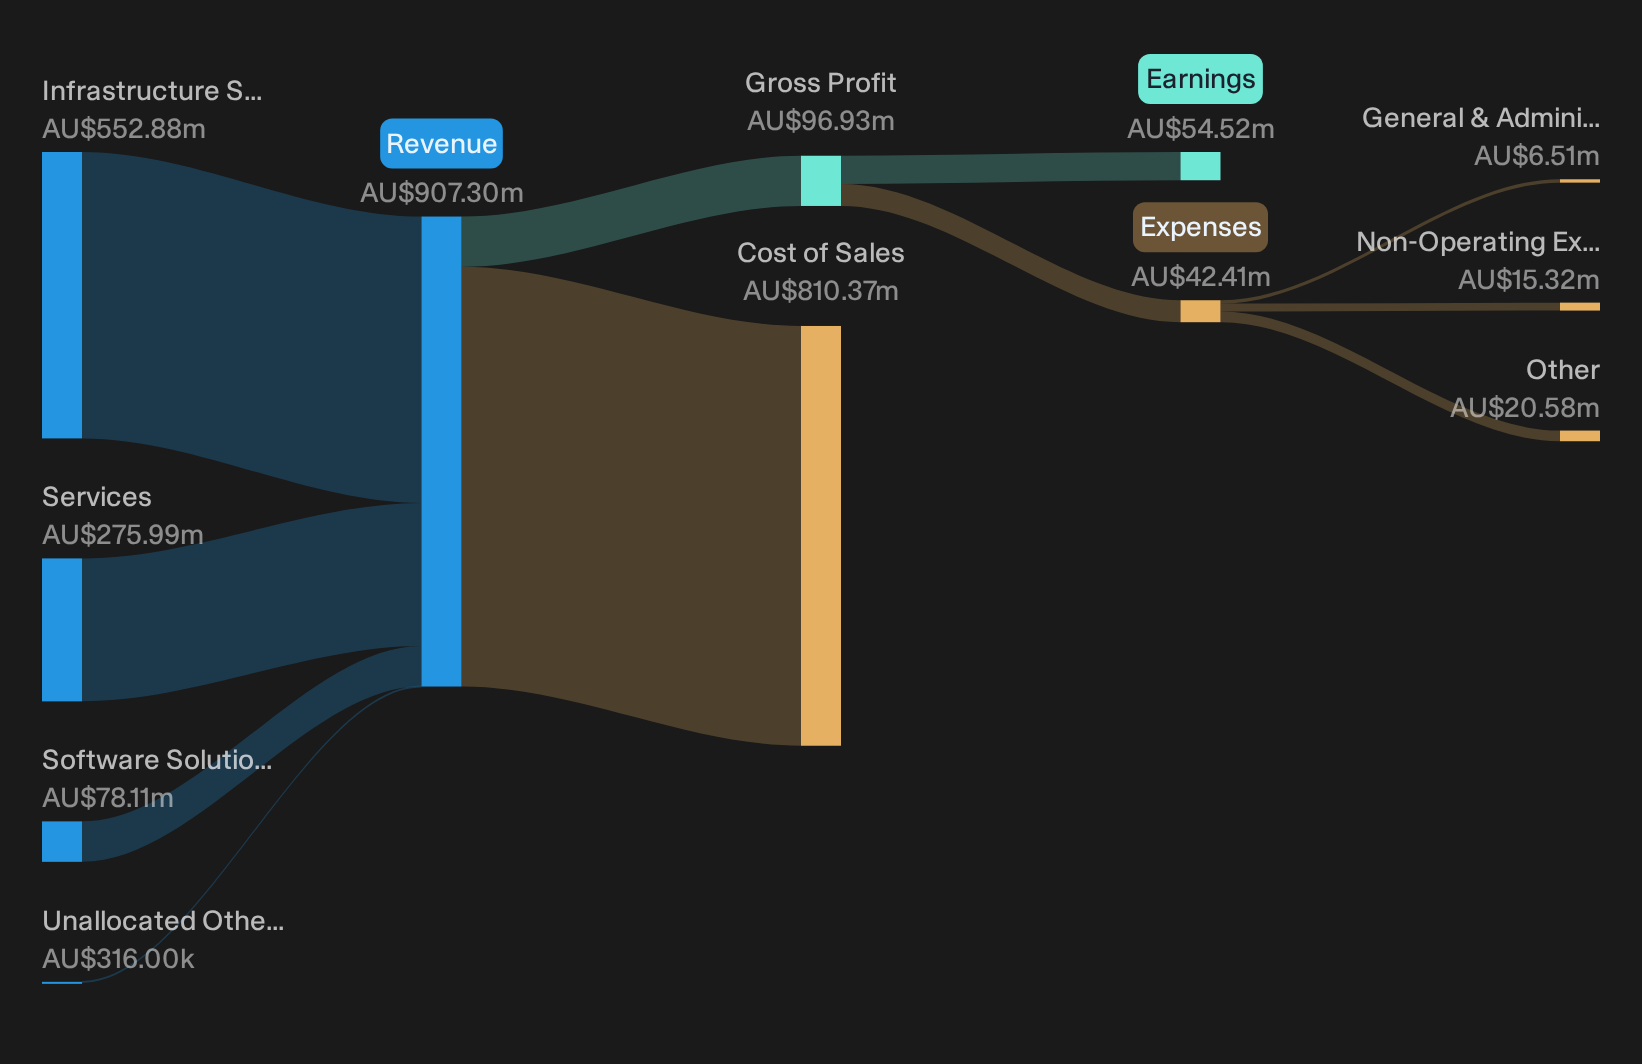
Data#3 is a Brisbane based IT solutions provider that helps enterprises move to cloud, secure their systems and roll out tools like Microsoft 365 Copilot and AI driven analytics, earning A$553 million from Infrastructure Solutions, A$276 million from Services and A$78 million from Software Solutions on an A$2.1b market cap.
Data#3 gives this AI Small Caps screen another angle, because its Copilot and AI services sit inside a much broader mix of cloud, security and hardware work that already runs at serious scale across Australian enterprises.
"The accelerating shift by customers to multiyear subscription and as-a-service models (evidenced by recurring revenue increasing to 69% and rapid expansion in Device-as-a-Service) positions Data#3 for higher, more stable, and predictable revenue and margin growth over time as the mix continues to improve."
What really moves the needle for Data#3 now is how one quiet pressure on partner economics ultimately feeds through to growth, pricing and profitability.
If that pressure point has your attention, read the full narrative for Data#3 to see how Data#3’s AI subscriptions could be accelerating or quietly masking emerging risks.
Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time momentum is obvious, early entry points can be gone and spreads can widen quickly. Review these focused shortlists while they may still be timely and decide whether any fit your strategy.
- Identify cash rich operators before a potential breakout by scanning the list of solid balance sheet and fundamentals (12 results) curated from companies combining stronger finances with underlying business resilience.
- Follow commodities momentum with a more systematic approach by using the curated 35 elite gold producer stocks that highlights producers with meaningful scale.
- Monitor structural infrastructure demand while it may still be less widely followed through the hand picked 43 power grid technology and infrastructure stocks built around grid technology and upgrade projects.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com