
Third Quarter Earnings Could Be A Big Moment For Stolt Nielsen Stock (OB:SNI)
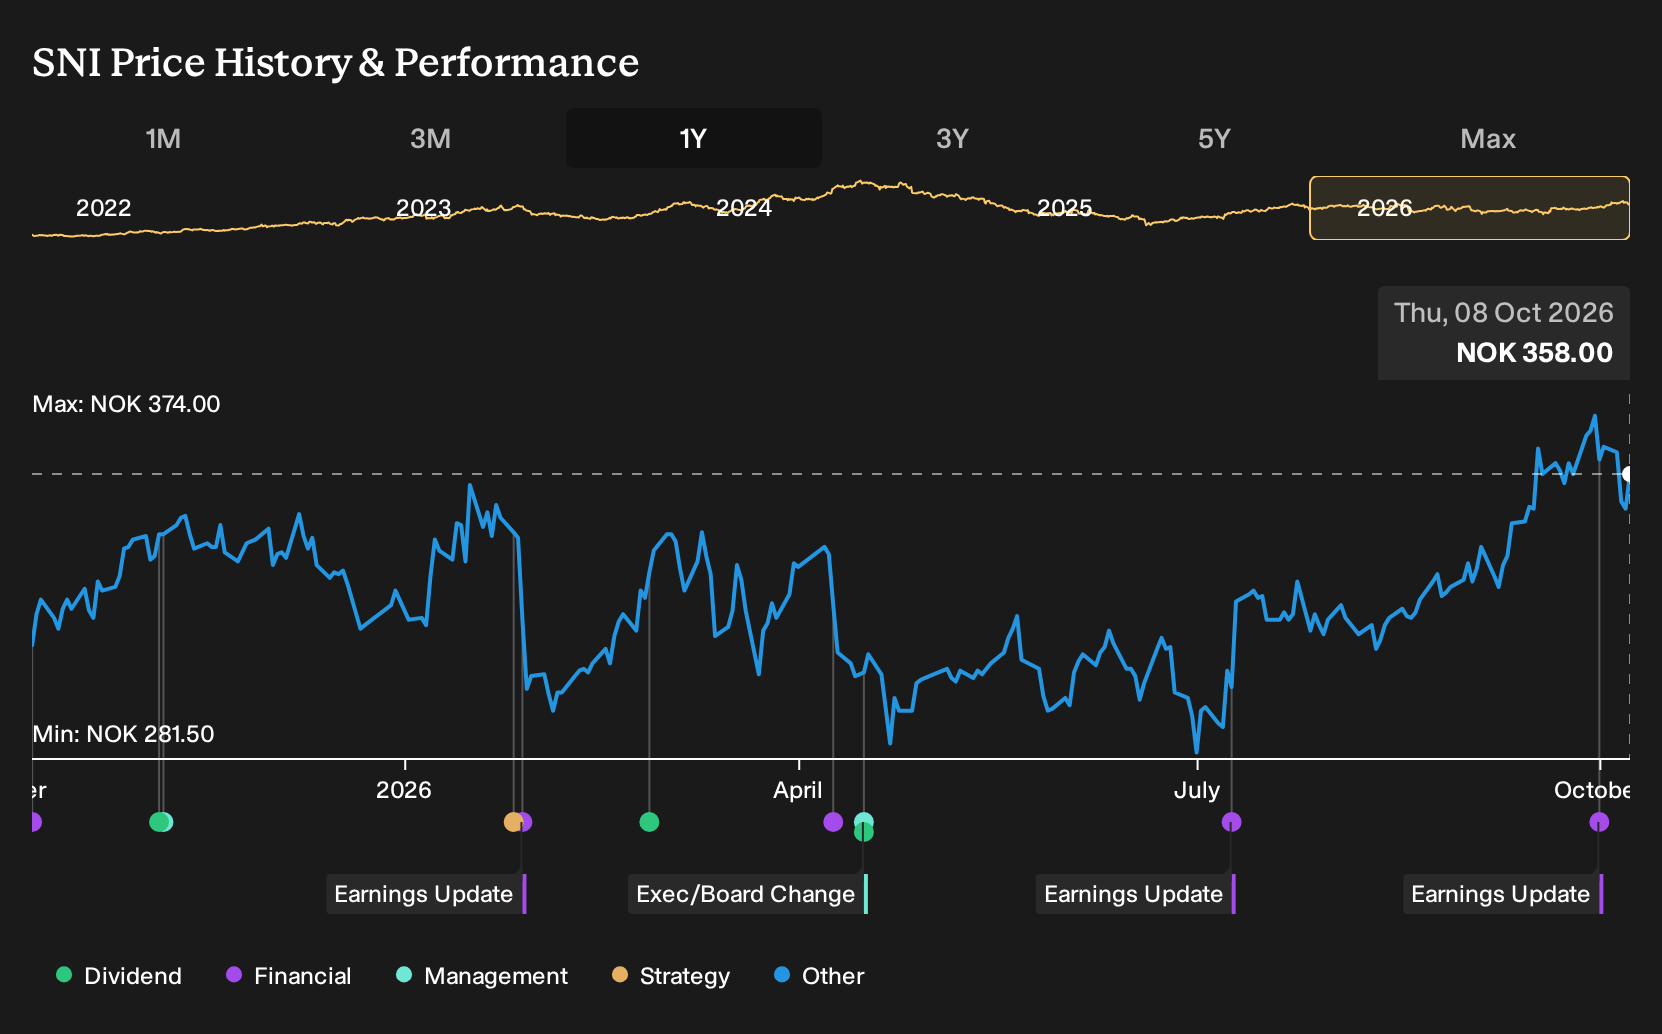
- Stolt-Nielsen reported third quarter 2026 sales of US$776.49 million and net income of US$84.43 million, with basic and diluted EPS from continuing operations at US$1.59, compared with US$1.20 a year earlier.
- Across the nine months to August 31, 2026, Stolt-Nielsen generated sales of US$2.24 billion and net income of US$183.53 million, so the stronger single quarter sits against a weaker year to date earnings base.
- We will now explore how Stolt-Nielsen's stronger third quarter EPS from continuing operations affects its investment narrative and risk balance.
Scan how Stolt-Nielsen's earnings shift compares with other potential opportunities by reviewing our hand picked list of 179 high quality undervalued stocks that combine quality fundamentals with compressed valuations.
Stolt-Nielsen Investment Narrative Recap
To own Stolt-Nielsen, you need to be comfortable with a cyclical shipping and logistics group that is using terminals, tank containers, gas and aquaculture to smooth out a volatile tanker cycle. The third quarter EPS of US$1.59 suggests the underlying operations can still throw off solid earnings, even with a softer nine month profit base.
The key near term swing factor remains how chemical tanker volumes and pricing hold up while tariffs, trade frictions and supply chain delays linger. The biggest risk right now is that weaker tanker utilization combines with higher interest costs, which could squeeze margins and limit flexibility if conditions tighten further.
The recent earnings update itself is the announcement that matters most here. Sales of US$776.49 million and net income of US$84.43 million for the quarter sit against nine month net income of US$183.53 million, so the stronger single period arrives after a weaker run earlier in the year.
For you as a shareholder prospect, that mix puts execution under the spotlight. Management is investing in terminals, tank containers and gas, while also carrying higher leverage and facing softer profit margins than last year. The latest quarter offers some reassurance on current trading, but the risk balance still hinges on how consistently Stolt-Nielsen can convert those assets into cash flow.
Stolt-Nielsen's narrative projects US$3.2b revenue and US$225.5 million earnings by 2029. This corresponds to 3.1% yearly revenue growth and an earnings decline of about US$17.5 million from US$243.0 million today.
Uncover how Stolt-Nielsen's fair value points to a 4% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Some analysts focus less on tariffs and more on earnings pressure if Stolt-Nielsen’s terminals and tank containers fall short of current utilization. The most bearish group was pencilling in only US$3.2b of 2029 revenue and US$167.7 million of earnings before this quarter. That is a much harsher script. Use it as a reference point and compare several views.
Explore 2 other Stolt-Nielsen fair value estimates, including one that suggests it could be worth just NOK 370.73.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Stolt-Nielsen research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Stolt-Nielsen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stolt-Nielsen's overall financial health at a glance.
Looking For More Investment Ideas Beyond Stolt-Nielsen?
If this Stolt-Nielsen update has sharpened your view on cyclical earnings and risk, you may wish to broaden your playbook by scanning other companies through the Simply Wall St Screener. You can compare balance sheet strength, dividends and valuation side by side and see which businesses best match your own return and risk preferences.
- If you care most about resilient businesses with fewer financial red flags, start with a 225 resilient stocks with low risk scores that already screen well on risk scores and balance sheet quality.
- If steady income is higher on your priority list, check out a 226 dividend fortresses that combine higher yields with underlying fundamentals you can actually live with.
- If you prefer to seek out underappreciated opportunities, focus on a 620 high quality undiscovered gems where solid cash generation and financial strength have not yet attracted broad attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com