
How Investors Are Reacting To Santos (ASX:STO) Project Earnings Test
- Santos has recently drawn investor attention as its earnings profile, low operating break even and major LNG projects like Barossa and Pikka are weighed against the capital intensity and risks that come with turning large energy developments into durable cash flows.
- The key issue is earnings durability, since Santos' premium P/E relative to peers relies on these projects converting into steady profits despite commodity and execution risks.
- The focus now turns to how Santos' investment narrative holds up when current earnings sustainability and project execution risks are examined more closely.
Scan beyond Santos to evaluate other energy producers facing similar project and valuation pressures using our hand picked 5 high quality undervalued stocks.
Santos Investment Narrative Recap
Santos appeals most if you think current projects can turn into long lived, low cost cash generation. The thesis leans on the low operating break even below A$35 per barrel; the LNG contract book that runs through 2029; and disciplined capital allocation as Barossa and Pikka move through heavy spend into production.
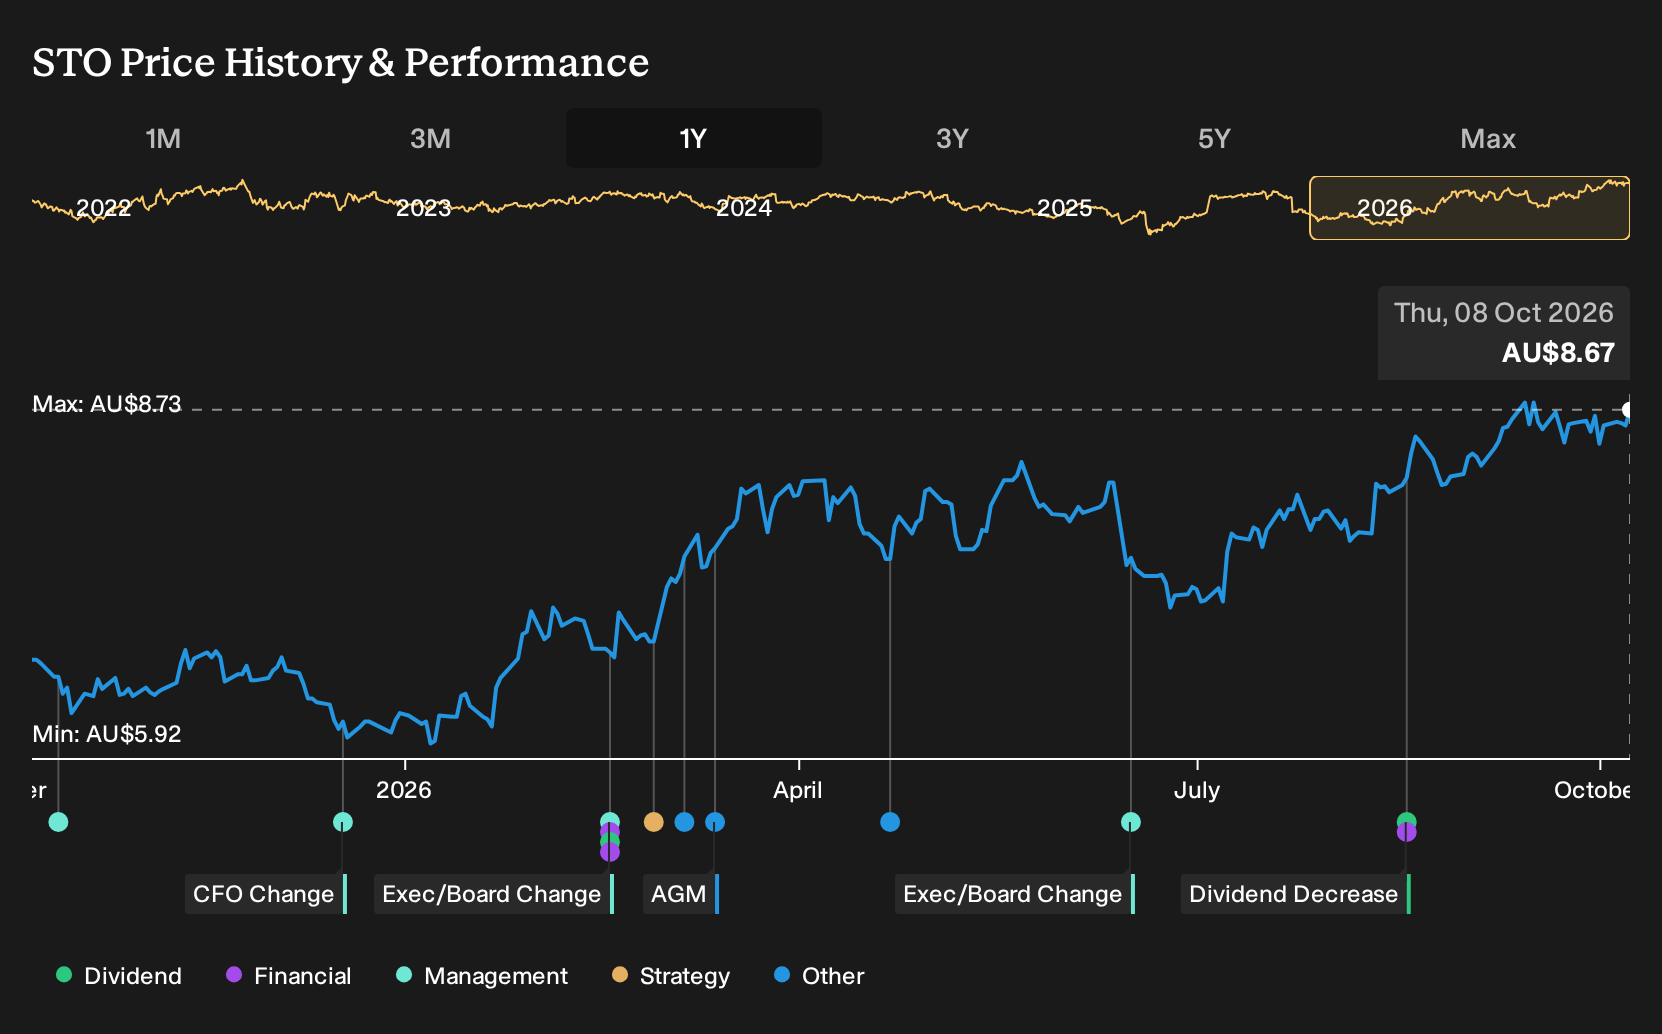
The recent share price strength does not change the near term swing factors. The main catalyst remains clean, on time ramp up of Barossa LNG and Pikka Phase 1. The key risk is that cost overruns, delays or softer commodity prices strain free cash flow while dividends are already not well covered by cash generation.
With no fresh company announcements, the relevant reference point is still Santos' emphasis on project delivery and cash returns around Barossa and Pikka. These projects sit on top of existing assets in Papua New Guinea, Western Australia and Northern Australia, so execution quality will drive how much incremental production actually hits the bottom line.
For catalysts, think in terms of milestones rather than headlines. Evidence of Barossa or Pikka hitting production targets; unit cost progress toward the sub A$7 per boe goal; or clearer disclosure on decommissioning and remediation provisioning would all feed directly into how sustainable current earnings look relative to the premium P/E multiple.
Santos' current earnings of $734.0 million are projected by analysts to reach $1.6 billion by 2029, with forecast revenue of $7.0 billion in the same year. This implies around 12.2% yearly revenue growth and an earnings increase of about $866.0 million from earnings today.
Uncover why Santos' fair value points to an 8% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
For a very different angle on Santos, focus on the risk that Barossa and Pikka deliver less earnings uplift than hoped. The most cautious analysts were working off around $6.5b of revenue and $1.2b of earnings by 2029 before this news. That is well below consensus, so views may shift as fresh information becomes available.
Explore 7 other Santos fair value estimates, including one that suggests as much as 11% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Santos research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Santos. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Santos' overall financial health at a glance.
Looking for more Santos investment ideas and peers?
If you want to pressure test your view on Santos against other opportunities, broaden your watchlist using the Simply Wall St Screener. Comparing similar businesses side by side helps you judge whether the risk, earnings profile and valuation you see here are compelling enough versus what else is available.
- For investors who care most about robust balance sheets and consistent fundamentals, start with a list of solid balance sheet and fundamentals (12 results) to see which businesses line up with that quality focus.
- If you want potential mispricing opportunities where quality meets a lower implied P/E, scan through a 5 high quality undervalued stocks that aims to pair financial strength with attractive pricing.
- Income focused readers who want cash returns front and center can review a 5 dividend fortresses built around higher yield payers that still meet key financial checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com