
Is American Express (AXP) Below Fair Value As Regulators Order A $350 Million Overhaul?
Regulatory fine puts American Express under the microscope
American Express (AXP) is in focus after multiple U.S. regulators ordered the business to overhaul its anti money laundering controls and imposed a US$350 million penalty tied to compliance breakdowns.
Recent market moves show that American Express has been under pressure, with the share price down 5.5% over the past month and 17.3% year to date, even though the 3 year total shareholder return of 110.7% and 5 year total shareholder return of 91% still point to a very strong longer run outcome. In the short term, the regulatory fine and compliance overhaul sit alongside steadier corporate news such as a US$0.95 quarterly dividend and new product launches in areas like corporate cashback cards and AI driven expense tools. Together, these developments help frame how investors reassess both risk and potential opportunity around the stock.
Compare how American Express stacks up on compliance, dividends, and earnings trends against a hand picked list of solid balance sheet and fundamentals (25 results) that may better fit your risk comfort.
American Express now carries a fresh regulatory scar and a share price that has already slipped this year. Do you lean into the weakness today, or wait for a clearer entry after the dust settles on valuation?
Most Popular Narrative: 30.6% Undervalued
According to John_Eric, the most followed narrative pegs American Express at a fair value of $444.11 against a last close of $308.10. This framing puts the current regulatory setback inside a bigger story about trust, capital returns, and how much uncertainty investors are willing to underwrite.
American Express has spent 176 years proving that trust is not a sentimental accessory added after the financial analysis. Trust is the productive asset. It is what allows the company to convert a customer's reputation into merchant fees, interest income, annual fees, and enormous purchasing volume.
The current AML matter presents a less cinematic but still important test. The business is performing well. Credit remains controlled. Berkshire has kept every share. My base-case valuation indicates a meaningful discount.
See why 5 investors see American Express as 31% undervalued.
Result: Fair Value of $444.11 (UNDERVALUED)
Still, the AML enforcement outcome and any tighter Category II capital rules could limit the potential upside for American Express if they reshape compliance costs or restrict future buybacks.
Find out about the key risks to this American Express narrative.
Another View on American Express valuation
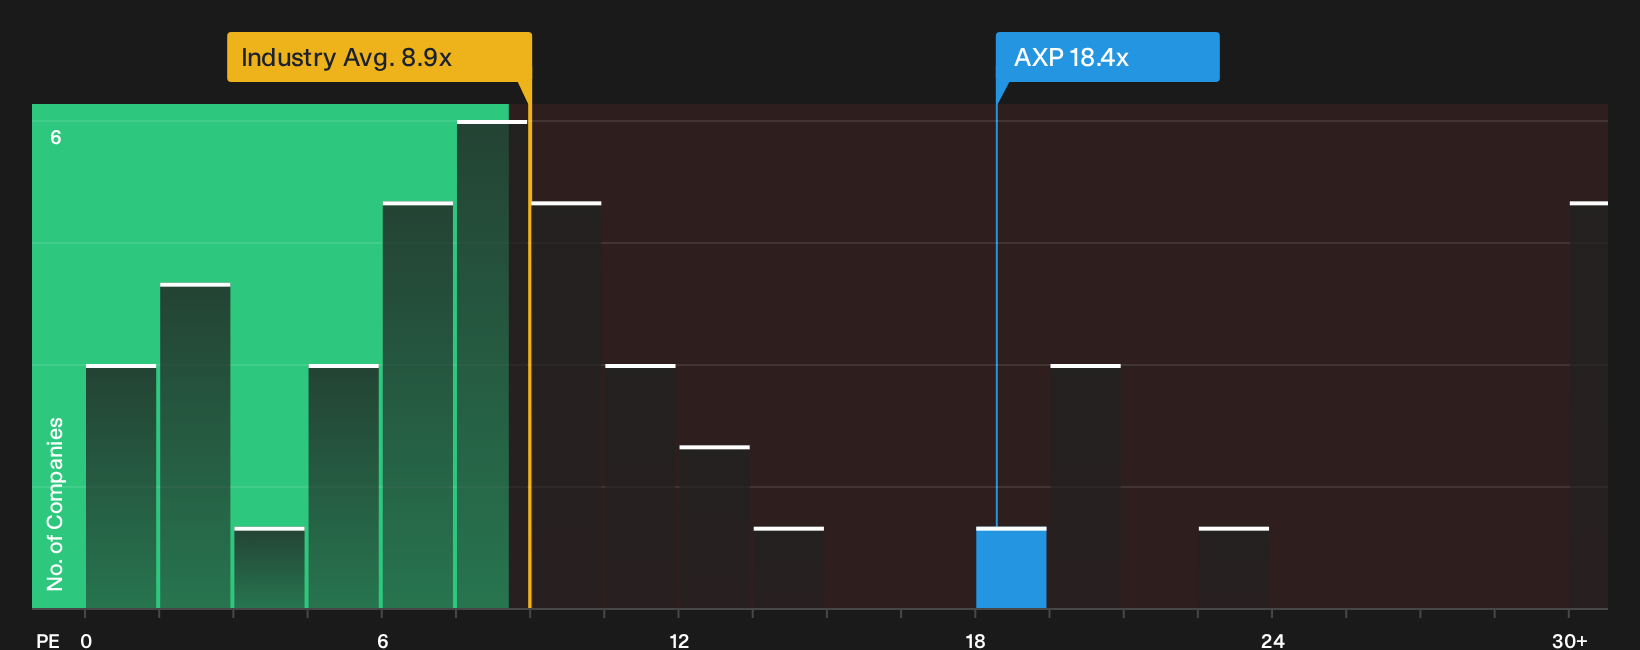
The first narrative leans on a detailed cash flow build for American Express. A simple P/E check tells a different story. The stock trades at 18.4x earnings versus a US Consumer Finance average of 8.9x and a peer average of 20.2x, while our fair ratio sits at 17.4x. That mix suggests less of a clear bargain and more of a discussion about how much quality investors may be willing to pay for.
See what the numbers indicate about this price in our valuation breakdown, and how it compares with similar companies and the fair ratio the market could move toward over time, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of mixed signals around American Express, yet the real edge comes from weighing them yourself and acting before sentiment fully settles. Begin with the 4 key rewards and 1 important warning sign.
Looking for more American Express alternatives?
If American Express has sharpened your focus on risk, capital return, and regulation, then broadening your watchlist now could shape your next strong decision.
- Target resilient cash generators with strong balance sheets by scanning a curated list of solid balance sheet and fundamentals (25 results) that keeps financial strength front and center.
- Hunt for mispriced opportunities with quality fundamentals using the focused 20 high quality undiscovered gems before wider attention chases the same stories.
- Prioritize steadier income by reviewing a hand picked 8 dividend fortresses that concentrates on companies offering higher yields with robust profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com