
Credit Quality Risks Could Be A Key Test For Frost Bankers Stock
- Cullen/Frost Bankers reported that over the past two years its annual revenue growth of 7.2% and EPS growth of 10.7% trailed the broader banking sector, and analysts now flag a projected 6.3% decline in tangible book value per share over the next 12 months tied to credit quality pressures.
- The combination of slower top and bottom line progress and expectations for tangible book value erosion puts Cullen/Frost Bankers’ credit risk management and capital resilience under the microscope for anyone tracking its Texas focused banking model.
- We will now examine how Cullen/Frost Bankers’ investment narrative could be affected by its slower growth profile and expected tangible book value pressure.
Compare Cullen/Frost Bankers’ slower growth and credit pressure with hand picked alternatives by scanning our 31 resilient stocks with low risk scores tool, which puts balance sheet resilience front and center.
Cullen/Frost Bankers Investment Narrative Recap
Cullen/Frost Bankers still asks you to believe in a Texas focused, relationship driven banking model that can keep adding households and business clients even as growth runs slower than many peers. The near term swing factor is credit. With a projected 6.3% decline in tangible book value per share tied to credit quality, loan performance and reserve decisions, these factors matter more than headline revenue.
The biggest risk right now is that credit stress in areas like Texas real estate or energy spreads and forces higher losses, which would pressure both capital and earnings power. Recent news on softer revenue and EPS growth does not fundamentally change that risk, but it sharpens attention on how much cushion Cullen/Frost Bankers really has if Texas specific pressure deepens.
The upcoming third quarter 2026 earnings release and conference call on 29 October is the most direct catalyst linked to this story. Management plans to walk through results and take analyst questions, which gives you a fresh read on how slower revenue growth, EPS underperformance and tangible book value pressure are feeding through the income statement and balance sheet.
For anyone tracking Cullen/Frost Bankers, this call is less about headline beats and more about the trajectory of credit costs, deposit competition and branch expansion spending. Clear disclosure on criticized loans, charge offs in Texas focused portfolios and any updates to the branch rollout or technology investment pace will help you judge whether current credit concerns are stabilising or still building.
Cullen/Frost Bankers’ current analyst narrative points to revenues of US$2.6b and earnings of US$716.4m by 2029, based on an assumed 5.1% yearly revenue growth rate and a move in profits from US$669.4m today to that 2029 consensus level, which represents an earnings increase of about US$47m from current earnings.
Uncover why Cullen/Frost Bankers' fair value indicates a 15% potential upside to its current price, which could narrow quickly.
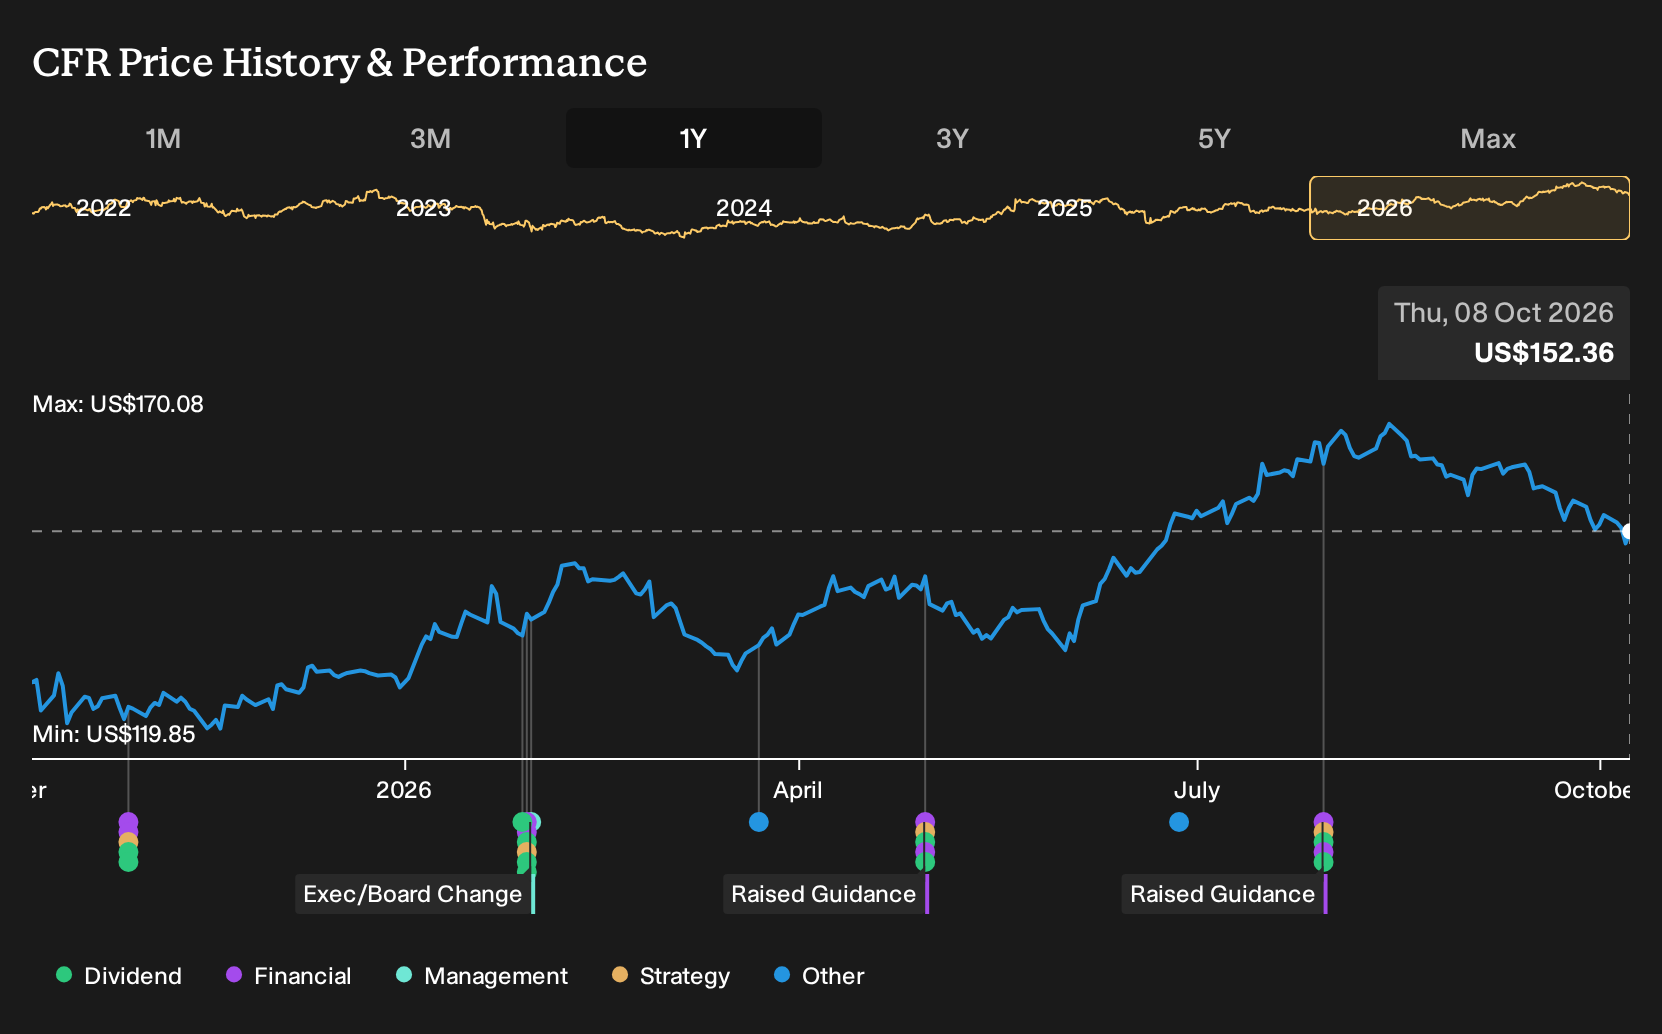
Exploring Other Perspectives
Fair value views on Cullen/Frost Bankers from the Simply Wall St Community stretch from about US$174.86 to an extreme US$101,835.18, across just 3 separate estimates. That spread shows how far opinions can drift before the October 29 earnings call updates credit cost trends, Texas exposure and branch spending. It may be useful to explore several viewpoints before forming your own stance.
Explore 2 other Cullen/Frost Bankers fair value estimates, including one that suggests as much as 66739% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Cullen/Frost Bankers research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Cullen/Frost Bankers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cullen/Frost Bankers' overall financial health at a glance.
Looking For More Investment Ideas Beyond Cullen/Frost Bankers?
If the Cullen/Frost Bankers story has raised fresh questions about credit risk, capital strength and long term compounding, it can help to compare that picture with other businesses that line up better with your own priorities on quality, value or income.
- For investors who want a margin of safety backed by both cash flows and balance sheet support, scan our 27 high quality undervalued stocks and see which companies combine quality fundamentals with a price that may not fully reflect them.
- If resilience matters more than anything, focus on defensive balance sheets and strong liquidity using the list of solid balance sheet and fundamentals (25 results) to filter for businesses that keep financial risk in check.
- For those building a portfolio around recurring income, use the 8 dividend fortresses to zero in on higher yielding payers where distributions are supported by underlying financials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com