
How Investors Are Reacting To UPS Holiday Delivery Upgrades
- United Parcel Service is entering the 2026 holiday season with expanded services including RFID-powered tracking, Protected Delivery PIN verification for eligible high-value shipments, broader pickup visibility, flexible last‑mile options and a new UPS Secure Commerce risk management suite.
- These security and data tools push UPS further toward tech-enabled logistics, aiming to reduce fraud, claims costs and service disruptions while supporting holiday peak demand for businesses and consumers.
- We will now look at how United Parcel Service's investment narrative is affected by the rollout of RFID tracking and Protected Delivery.
United Parcel Service Investment Narrative Recap
To own United Parcel Service, you need to believe the shift toward higher yielding SMB, B2B and healthcare shipments, plus automation, eventually outweighs flat long term revenue trends and weaker recent earnings. The key short term catalyst is clean execution through peak season, where RFID, Protected Delivery and expanded options are tested under real volume pressure.
The biggest near term risk remains that heavy network consolidation, labor friction and a high dividend payout strain service quality or cash generation. The latest holiday upgrades look operational rather than transformational, so they likely matter most as proof points on execution, not as a material change to the investment case on their own.
The launch of UPS Secure Commerce is the clearest link between the current holiday upgrades and the broader thesis. It packages InsureShield, Parcel Pro and CommerceShield into one data and risk platform, tying fraud prevention, loss mitigation and supply chain visibility directly into UPS’s existing automation and RFID rollout.
For you as a shareholder, Secure Commerce sits directly on the line between catalyst and risk. Better claims handling and risk intelligence may support margins and strengthen relationships with higher value shippers. At the same time, it adds another execution challenge on top of building closures, labor negotiations and already tight dividend coverage.
United Parcel Service's current narrative anchors on analysts expecting revenue to compound at about 3.4% per year, with earnings moving from US$4.6b today to a consensus forecast of US$7.2b by 2029. This implies an earnings increase of roughly US$2.6b on projected 2029 revenue of US$99.4b.
Uncover why United Parcel Service's fair value indicates a 23% potential upside to its current price that may not last much longer.
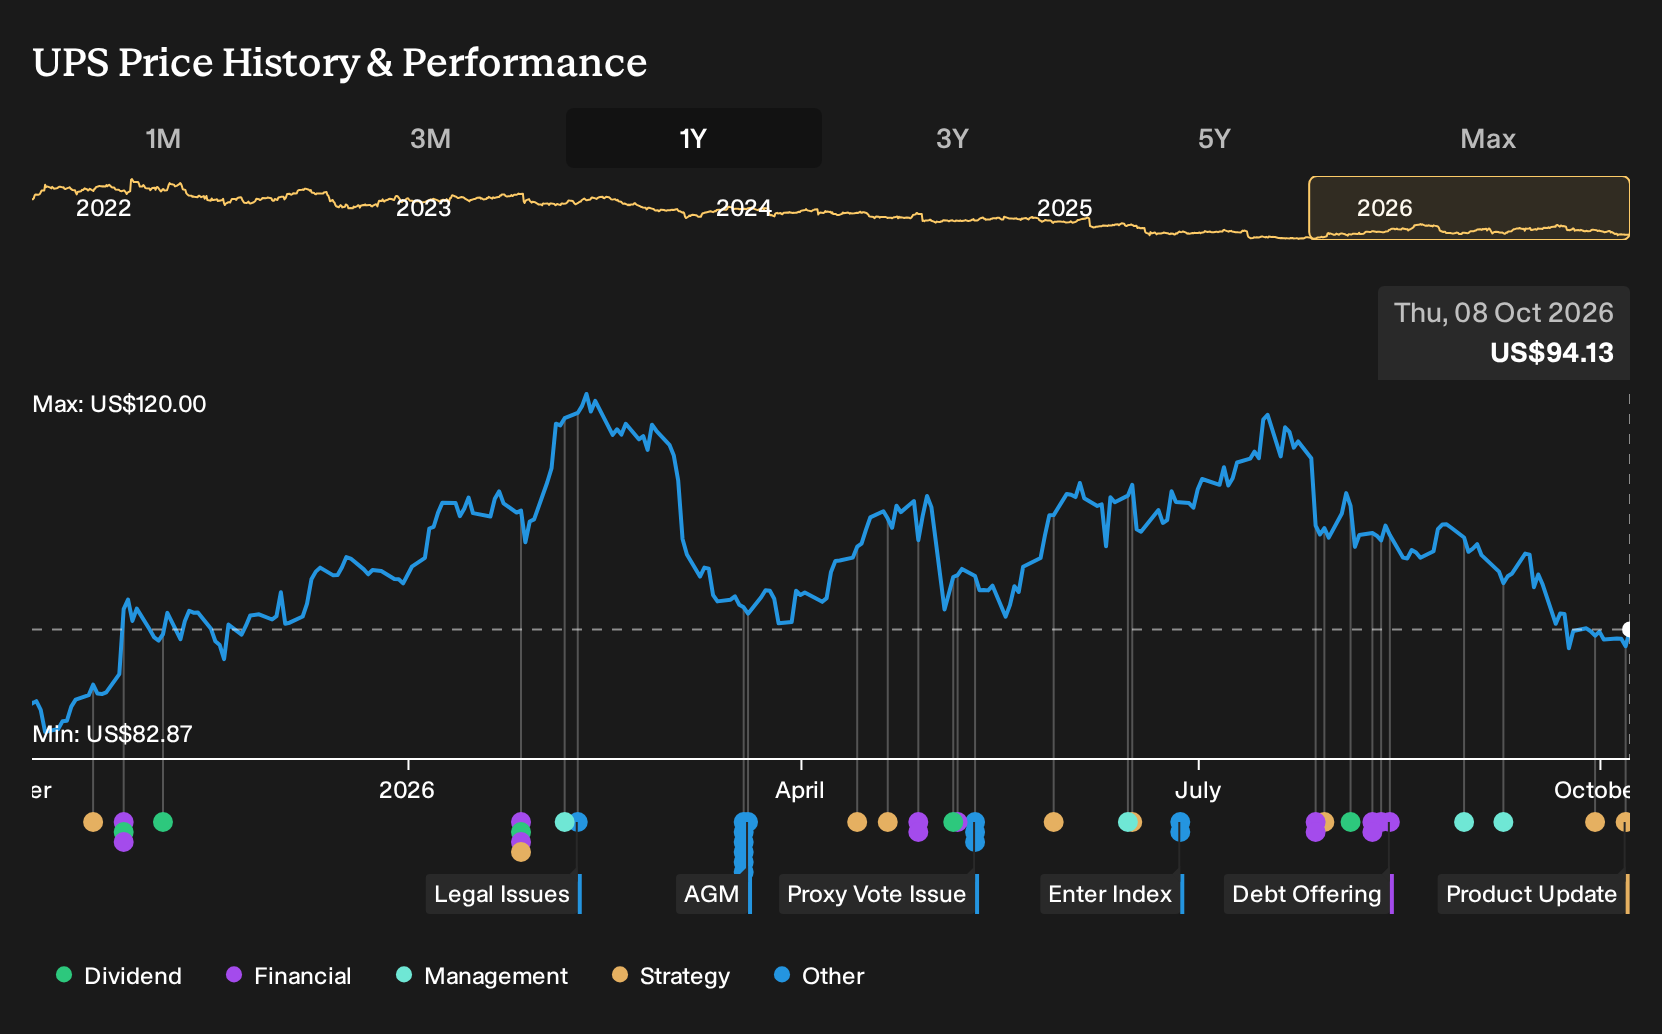
Exploring Other Perspectives
Some of the most optimistic analysts frame United Parcel Service around higher margin healthcare and digital services. They were pencilling in revenue of about US$105.5b and earnings of US$8.6b by 2029, compared with more cautious forecasts of US$99.4b and US$7.2b. RFID tracking and Protected Delivery could eventually push these narratives in new directions.
Explore 10 other United Parcel Service fair value estimates, including one that suggests there could be as much as 73% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so go with your instincts.
- A great starting point for your United Parcel Service research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for United Parcel Service. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Parcel Service's overall financial health at a glance.
Looking for more United Parcel Service style investment ideas?
If the United Parcel Service story has sharpened your thinking about quality, risk and payout, it can be useful to line it up against other opportunities using a consistent framework. The Simply Wall St Screener lets you do exactly that by filtering for balance sheet strength, income potential or underappreciated quality that fits the way you like to invest.
- If capital protection is high on your list, start with companies that screen well on resilience and financial stability by reviewing a 31 resilient stocks with low risk scores.
- For investors focused on income, it can help to compare United Parcel Service with other stocks offering substantial yields by scanning a range of 8 dividend fortresses.
- If you want to hunt for potential future compounders before they are widely followed, widen the lens to a curated set of 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com