
Eaton (ETN) Nears Earnings After Capacity Expansion, Is It Fully Priced?
Eaton (ETN) stepped into focus after a 3.09% share price decline to $431.33, as traders weighed upcoming earnings, recent executive moves, and new European manufacturing capacity.
Set against a share price of $424.51, Eaton’s recent 1-day share price decline of 1.58% and 7-day slide of 2.92% contrast with a 90-day share price return of 4.23% and a year-to-date share price gain of 29.70%. This suggests momentum has cooled in the short term while remaining positive over a longer window as investors absorb the Austria capacity expansion and the controller transition ahead of earnings.
Spot opportunities benefiting from similar electrification and industrial tailwinds by scanning our curated list of 43 power grid technology and infrastructure stocks.Eaton’s pullback after a strong year-to-date climb leaves a simple tension: Is most of the upside already reflected in the price, or does the recent cooling reset the entry point before earnings and expansion plans are fully priced in?
Most Popular Narrative: 18% Undervalued
The most followed Eaton narrative pegs fair value at about $517 per share, compared with the recent close at $424.51. This frames a wide gap that hinges on how investors view data center bottlenecks and electrification demand.
Eaton Corporation (NYSE: ETN) is one of the rare institutions that has managed to turn the physical constraints of heavy industry and metallurgy to its advantage. Its monopolistic position, benefiting from high material constraints (GOES), years-long delivery times, and in-cabinet thermal densities of 120 kW, along the Voltage Cascades from a 400,000-volt grid to 1 volt on a chip, has provided the company with an unsurpassable economic moat.
See why 14 investors see Eaton as 18% undervalued.
Result: Fair Value of $517 (UNDERVALUED)
Still, Eaton’s narrative can crack if transformer bottlenecks ease faster than expected, or if large AI customers slow data center and electrification spending.
Find out about the key risks to this Eaton narrative.
Another View On Eaton’s Valuation
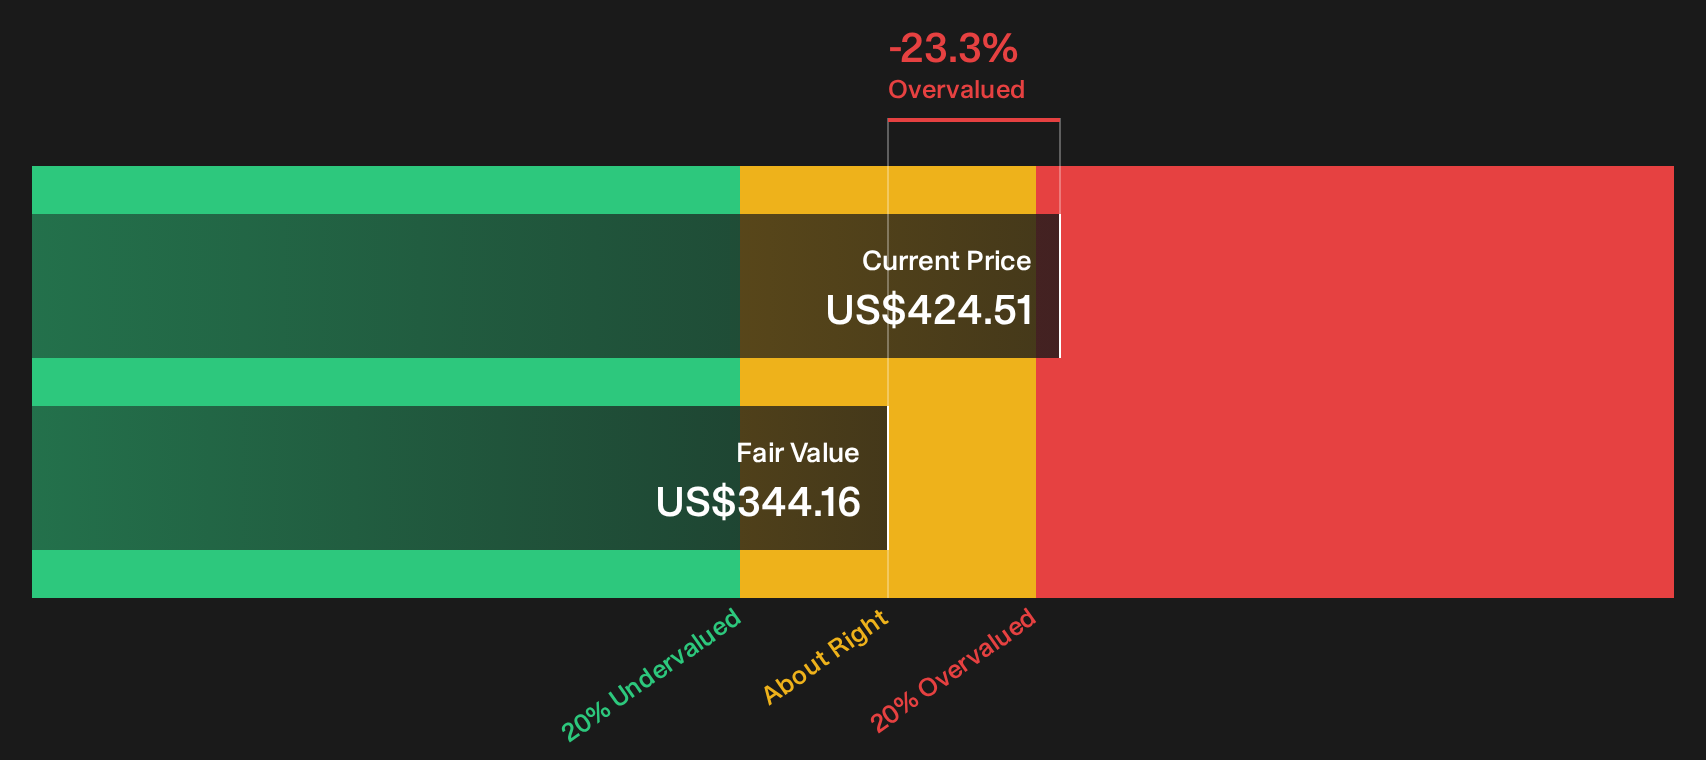
The popular fair value narrative puts Eaton around $517 per share, but our DCF model lands much lower at about $344.16. That implies Eaton looks expensive on a cash flow basis, which raises a simple question for investors: Is the story-rich thesis or the cash flow math closer to reality?
For anyone who wants to see how those assumptions play out line by line, it is worth going through the SWS DCF model in detail, starting with Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this Eaton story feels divided between optimism and caution, use that split as your cue to review the data yourself and move quickly to form a view based on 1 key reward and 1 important warning sign.
Looking for more Eaton investment ideas?
If Eaton has sharpened your focus on where capital can work harder, do not stop here. Use the Simply Wall Street Screener today and keep your opportunity set wide.
- Spot potential mispricings early by scanning a curated 27 high quality undervalued stocks that filters for quality alongside compelling price tags.
- Build a sturdier portfolio by focusing on companies with strong finances using our targeted list of solid balance sheet and fundamentals (25 results).
- Get ahead of the crowd by reviewing a handpicked 20 high quality undiscovered gems that many investors have not yet paid attention to.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com