
Fuchs (XTRA:FPE3) Extends Mercedes Benz Tie Up But Is The Valuation Already Fair?
Partnership Extension With Mercedes-Benz Sets The Stage
Fuchs (XTRA:FPE3) is back in focus after extending its long running partnership with Mercedes-Benz Group AG, a move that keeps its lubrication solutions embedded in the carmaker's global service network.
Recent trading shows momentum building, with a 1-day share price return of 1.06% and a 7-day move of 3.58% around the Mercedes-Benz contract extension, contributing to a 14.90% year-to-date share price return and a 17.82% 1-year total shareholder return.
Compare how Fuchs stacks up against other high quality compounders by checking the carefully filtered 620 high quality undiscovered gems in similar niche industrial and materials businesses.
The Mercedes-Benz renewal has helped Fuchs shares push higher, and the stock now trades closer to analyst targets. Does the current valuation still leave enough potential upside to justify taking equity risk from here?
Preferred P/E of 16.9x for Fuchs: Is It Justified?
Fuchs currently trades on a P/E of 16.9x, only a touch above the European chemicals average of 16.8x. This puts the stock roughly in line with broader sector pricing even after the Mercedes-Benz contract boost.
The P/E multiple compares the share price with earnings per share and gives you a quick sense of how much investors are paying for each unit of profit. For a mature lubricants specialist like Fuchs, which serves automotive and industrial customers across Europe, the Americas and Asia Pacific, earnings capacity and consistency often matter more than rapid top line expansion when investors consider what feels like a reasonable P/E.
On that score, the group has a few things working in its favor. Earnings grew 16.8% over the past year compared with a 4.8% per year pace over five years, profit margins improved to 9% from 8.2%, and analysts expect earnings to keep rising at 3.87% per year. The trade off is that both revenue and profit are expected to grow slower than the wider German market, which can justify only a modest premium to peers rather than a large one.
Relative to the sector, the current 16.9x P/E looks slightly expensive compared with the 16.2x level suggested as a fair ratio. This indicates that the market is paying somewhat above what historical patterns might support and may move closer to that lower reference point over time.
Explore the SWS fair ratio for Fuchs.
Result: Price-to-Earnings of 16.9x (ABOUT RIGHT)
Still, the Fuchs story can be knocked off course if large automotive partners rethink their lubricant sourcing, or if sector wide chemicals valuations compress from current levels.
Find out about the key risks to this Fuchs narrative.
Another View On Fuchs Using Cash Flows
The P/E suggests that Fuchs appears to be fairly priced against the sector, yet the SWS DCF model points a different way. On that framework, the shares trade at €43.96 compared with an estimated future cash flow value of €67.25. This implies the market might be pricing in more risk than the cash flow analysis suggests. Which lens do you rely on when hard cash and headline multiples differ?
For investors who want to see how that cash flow estimate is built step by step, the SWS DCF model is unpacked in detail here, including all the key assumptions behind the gap between price and value. Look into how the SWS DCF model arrives at its fair value.
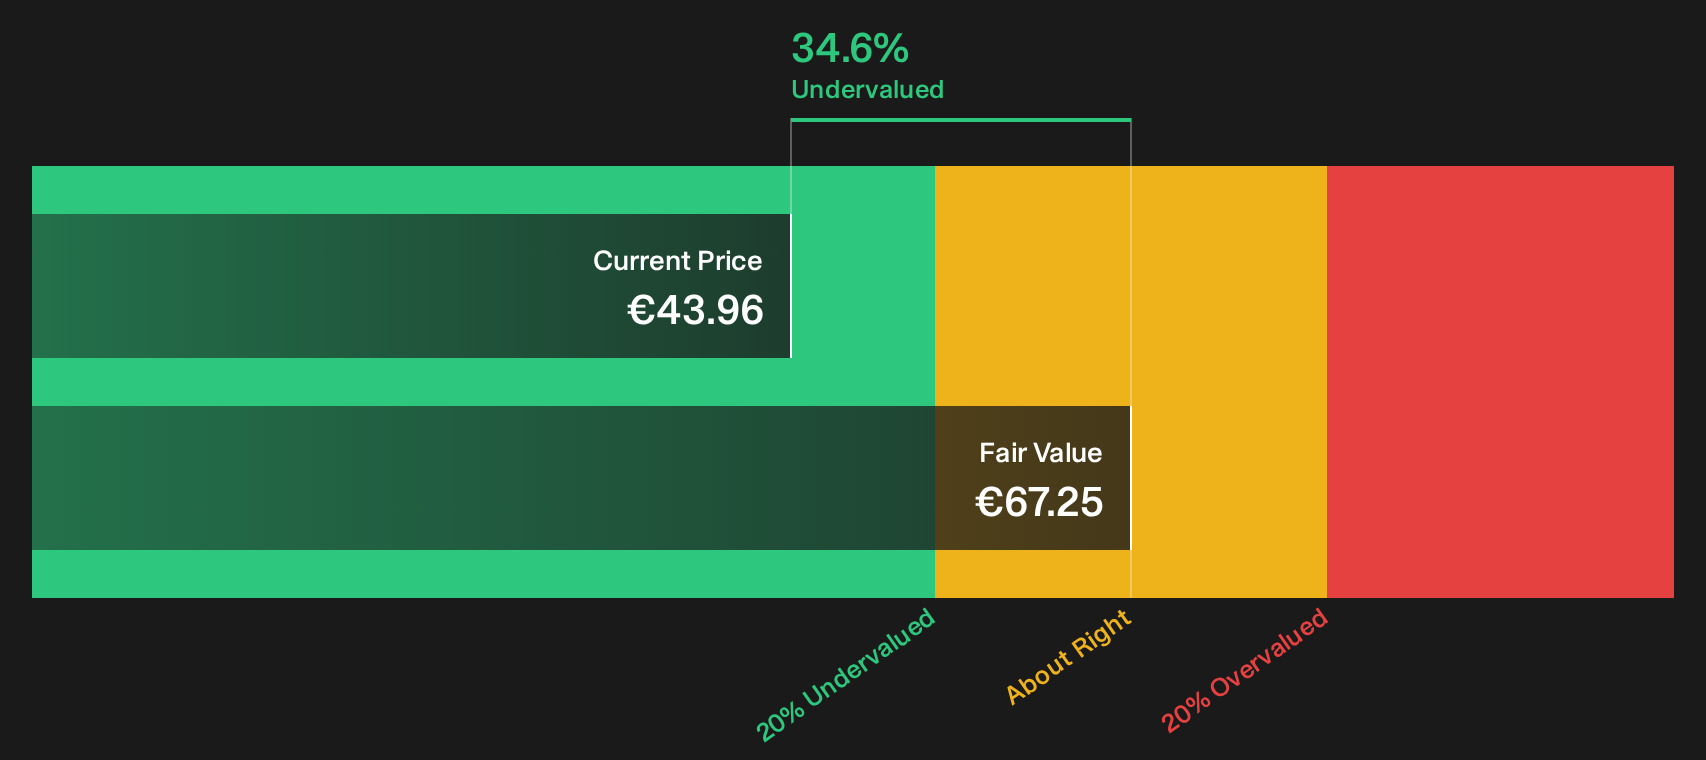
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fuchs for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of fair value signals and optimistic assumptions on Fuchs leaves you unsure, check the underlying data now and pressure test the upside story for yourself with the 4 key rewards
Looking for more investment ideas beyond Fuchs?
If Fuchs has sharpened your interest in high quality businesses, do not stop here. Broader opportunity often sits just outside the stocks you already know.
- Explore potentially resilient businesses by reviewing companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (206 results).
- Look for value opportunities by scanning the 179 high quality undervalued stocks that combine quality fundamentals with pricing that may look appealing.
- Maintain an income focus by checking out a curated set of higher yield opportunities in the 225 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com