
Fervo Energy (FRVO) Stock May Look Fully Priced Despite Cape Station Milestone
Fervo Energy has had a rough start as a listed utility, with the share price sliding while attention has shifted to its enhanced geothermal milestone at Cape Station in Utah. With the stock near US$13.80, the live question for investors is whether that market value lines up with what Fervo’s balance sheet currently supports through its book value.
- The share price is down 62.2% year to date, which puts extra focus on whether the current market value is still tracking the company’s underlying net assets.
- The first utility-scale enhanced geothermal power from Cape Station shows Fervo can bring complex projects to grid connection, which may shape how investors think about the capital intensity and long-term returns that sit behind its stated equity value.
- The analysts covering Fervo Energy have run their own numbers. See what analysts think Fervo Energy's shares could be worth.
The issue now is whether today’s stock price can be reconciled with Fervo Energy’s book value when compared with the broader industry average.
If you are weighing Fervo Energy against other utility and infrastructure ideas tied to the same broad theme of powering data and AI growth, it can help to compare it with companies in 91 AI infrastructure stocks.
Is Fervo Energy Getting Expensive on Book Value?
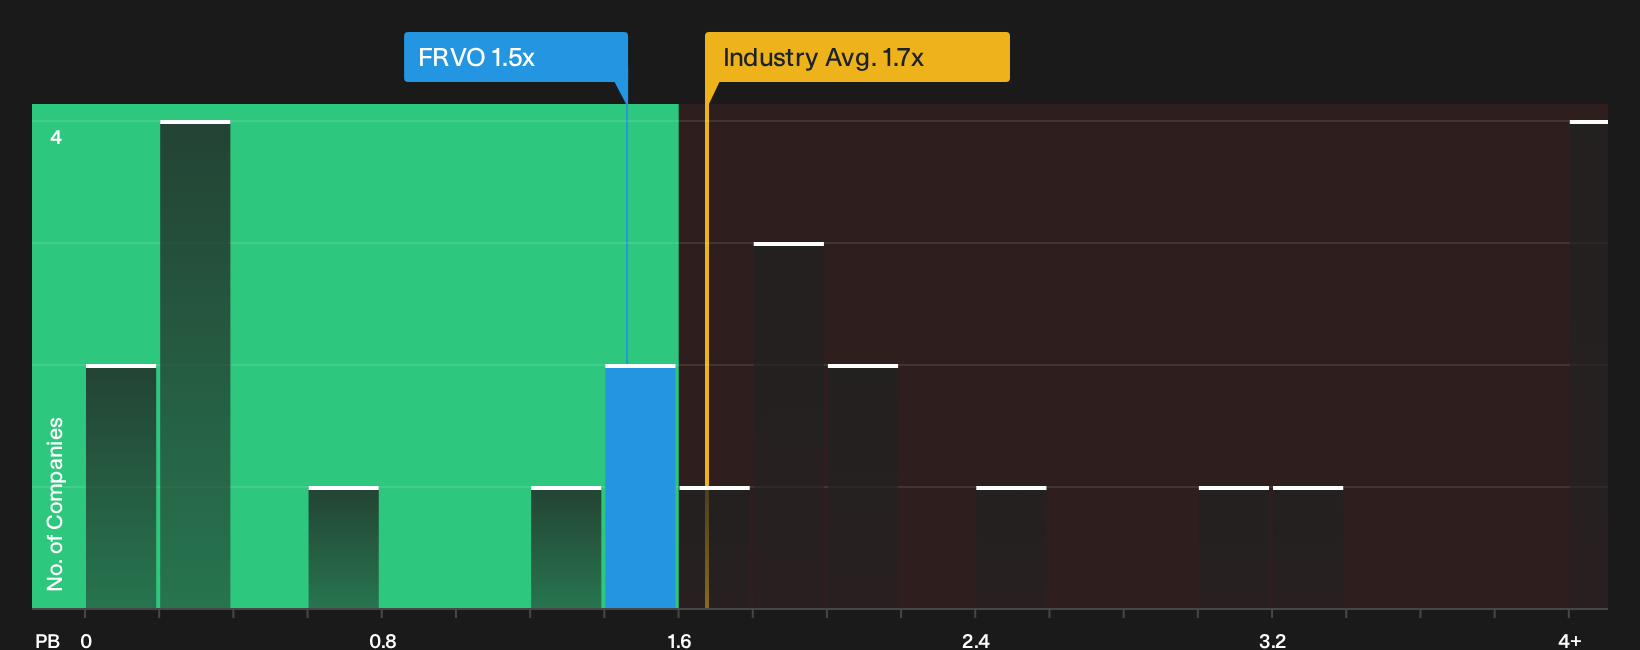
P/B fits Fervo Energy because the group is still heavily shaped by its project assets and equity base rather than mature earnings. On that yardstick, Fervo trades at about 1.5x book value, close to the renewable energy peer average near 1.6x and modestly above the broader sector’s 1.1x figure.
Despite the progress at Cape Station giving the story more profile, that 1.5x P/B still leaves the stock screening slightly overvalued relative to the typical renewable utility on this metric. For a long term holder, the key question is whether the quality, risk profile and funding needs of Fervo’s geothermal projects justify paying a premium over the sector’s asset base. Explore the numbers behind Fervo Energy's P/B valuation.
The Fervo Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where that P/B puzzle for Fervo Energy leaves off by spelling out which assumptions on future growth, profitability and earnings would need to hold for the current share price to look either stretched or conservative. Each scenario links a fair value estimate to a specific path for Fervo Energy's catalysts and risks, so you can track over time which version of the story is actually unfolding on the Community page.
One of the top community narratives on Fervo Energy: 65% undervalued
"Large, long duration power purchase agreements totaling 658 megawatts and US$7.2b in contracted revenue, alongside a 3 gigawatt framework agreement with Google…"
Discover why this Narrative puts Fervo Energy at 65% undervalued.
Fervo Energy’s valuation still leaves one powerful variable unresolved
Before you stop at the numbers, it is worth asking who is actually steering Fervo Energy and how their pay packets align with the outcomes you care about. See who runs Fervo Energy and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com