
Is UniFirst (UNF) A Bargain As NASCAR Buzz Meets A Rich P/E?
UniFirst (UNF) is back in the NASCAR spotlight as the primary sponsor of Chase Elliott’s No. 9 Chevy at a key Charlotte Motor Speedway Chase race, putting its brand squarely in front of motorsports fans.
Recent trading has been choppy for UniFirst, with the share price down 5.8% over the past month and 4.5% over 90 days, even as year to date share price return sits at 34.1% and the 1 year total shareholder return is 62.0%. This suggests that longer term momentum has been much stronger than the latest pullback.
Scan the grid for UniFirst style compounders by checking out our hand picked 20 high quality undiscovered gems that have strong fundamentals but far less attention than a NASCAR primary sponsor.
After a 34.1% year to date run and a recent pullback, UniFirst now trades only modestly below analyst targets. Is the risk reward still tilted toward buyers, or has most of the upside already been used?
Most Popular Narrative: 7.3% Undervalued
At a last close of $259.60 versus a most-followed fair value of $280, UniFirst is framed as modestly discounted, with that gap explained by long term efficiency and margin assumptions rather than short term trading swings.
Ongoing ERP implementation, including core finance now and supply chain and procurement modules through 2027, is expected to support better inventory sharing and sourcing. This targets lower merchandise and supply chain costs and improved net margins.
See why 0 investors see UniFirst as 7% undervalued.
Result: Fair Value of $280 (UNDERVALUED)
Still, UniFirst’s thesis depends heavily on a complex ERP rollout and increased spending on sales and service, which could keep margins and cash flow under strain if the benefits arrive slowly.
Find out about the key risks to this UniFirst narrative.
Another View: UniFirst Looks Expensive On Earnings
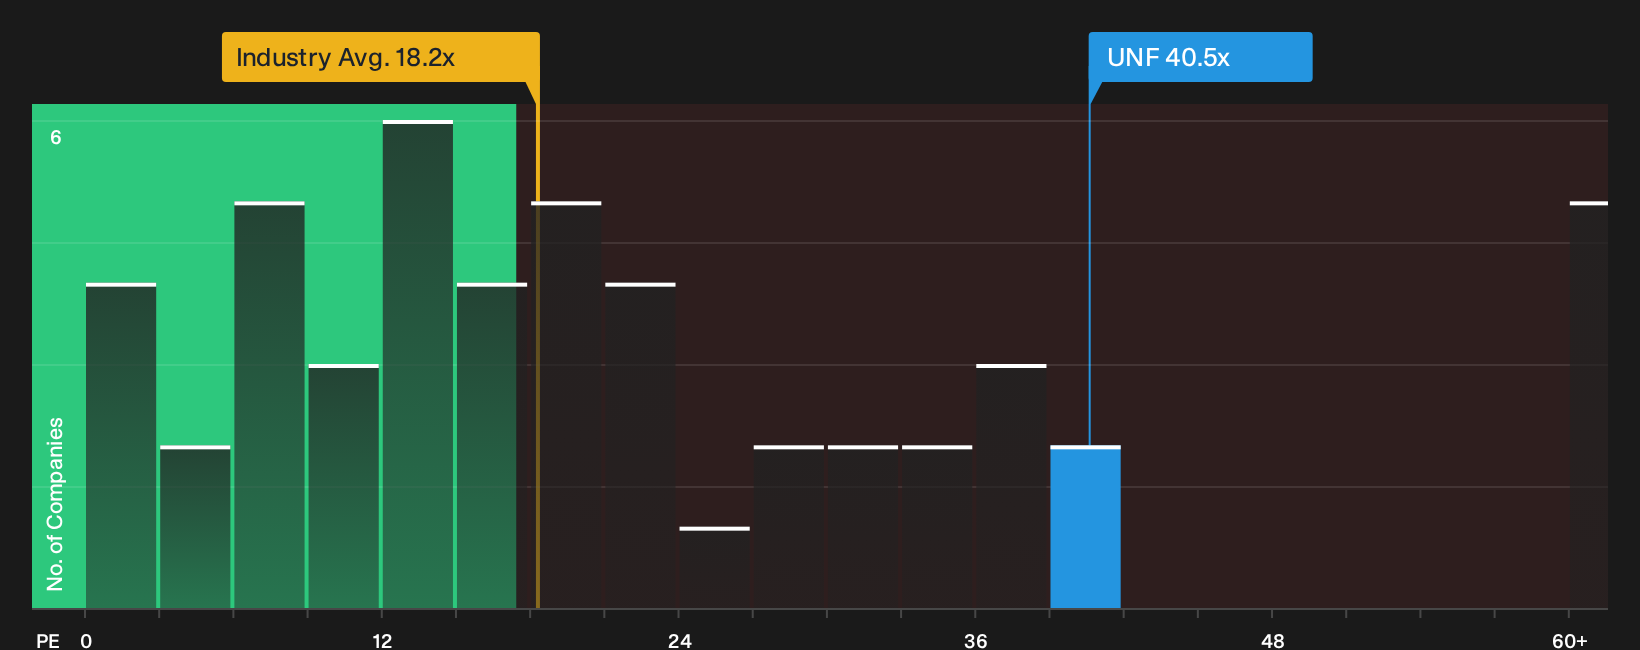
The story changes when UniFirst is viewed through its P/E. The stock trades at 40.5x earnings, while the US Commercial Services group is at 18.2x, peers average 26x, and the fair ratio sits at 21.3x. That is a wide premium. Is the market paying too much for this quality?
See what the numbers say about this price, find out in our valuation breakdown.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Debate around UniFirst is clearly split between optimism on execution and concern about valuation, so move fast and test the data against your own expectations. To see what has investors upbeat on potential rewards, run through the 1 key reward.
Looking for more UniFirst style investment ideas?
If UniFirst has your attention, do not stop here. Use focused screeners to surface other opportunities that match your risk, income, and quality preferences.
- Target potential mispricing and hunt for quality companies trading below their implied value by scanning our curated 27 high quality undervalued stocks.
- Strengthen your income stream and focus on consistency by zeroing in on proven payers through a hand picked set of 8 dividend fortresses.
- Dial down volatility and prioritize resilience by filtering for businesses with steadier profiles using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com