
Should Value Rating Upgrade Require Action From UMB Financial Stock Investors?
- UMB Financial is drawing fresh attention after value screens flagged its current P/B of 1.35, P/S of 2.24, and P/CF of 15.76, alongside a Zacks Rank #2 rating and an A grade for Value.
- The combination of recent earnings estimate revisions, oversold technical signals, and an upcoming third quarter 2026 earnings release has put the bank’s underlying operating performance and capital deployment plans under closer scrutiny.
- This analysis examines how UMB Financial's value rating and earnings estimate revisions intersect with the existing investment narrative on efficiency and growth.
UMB Financial Investment Narrative Recap
For UMB Financial, the core belief as a shareholder is that the business can keep pairing disciplined banking with fee based services like fund administration, corporate trust and institutional custody. That mix needs to support steady loan activity, funding of growth and a reliable dividend, even as temporary purchase accounting accretion gradually steps down.
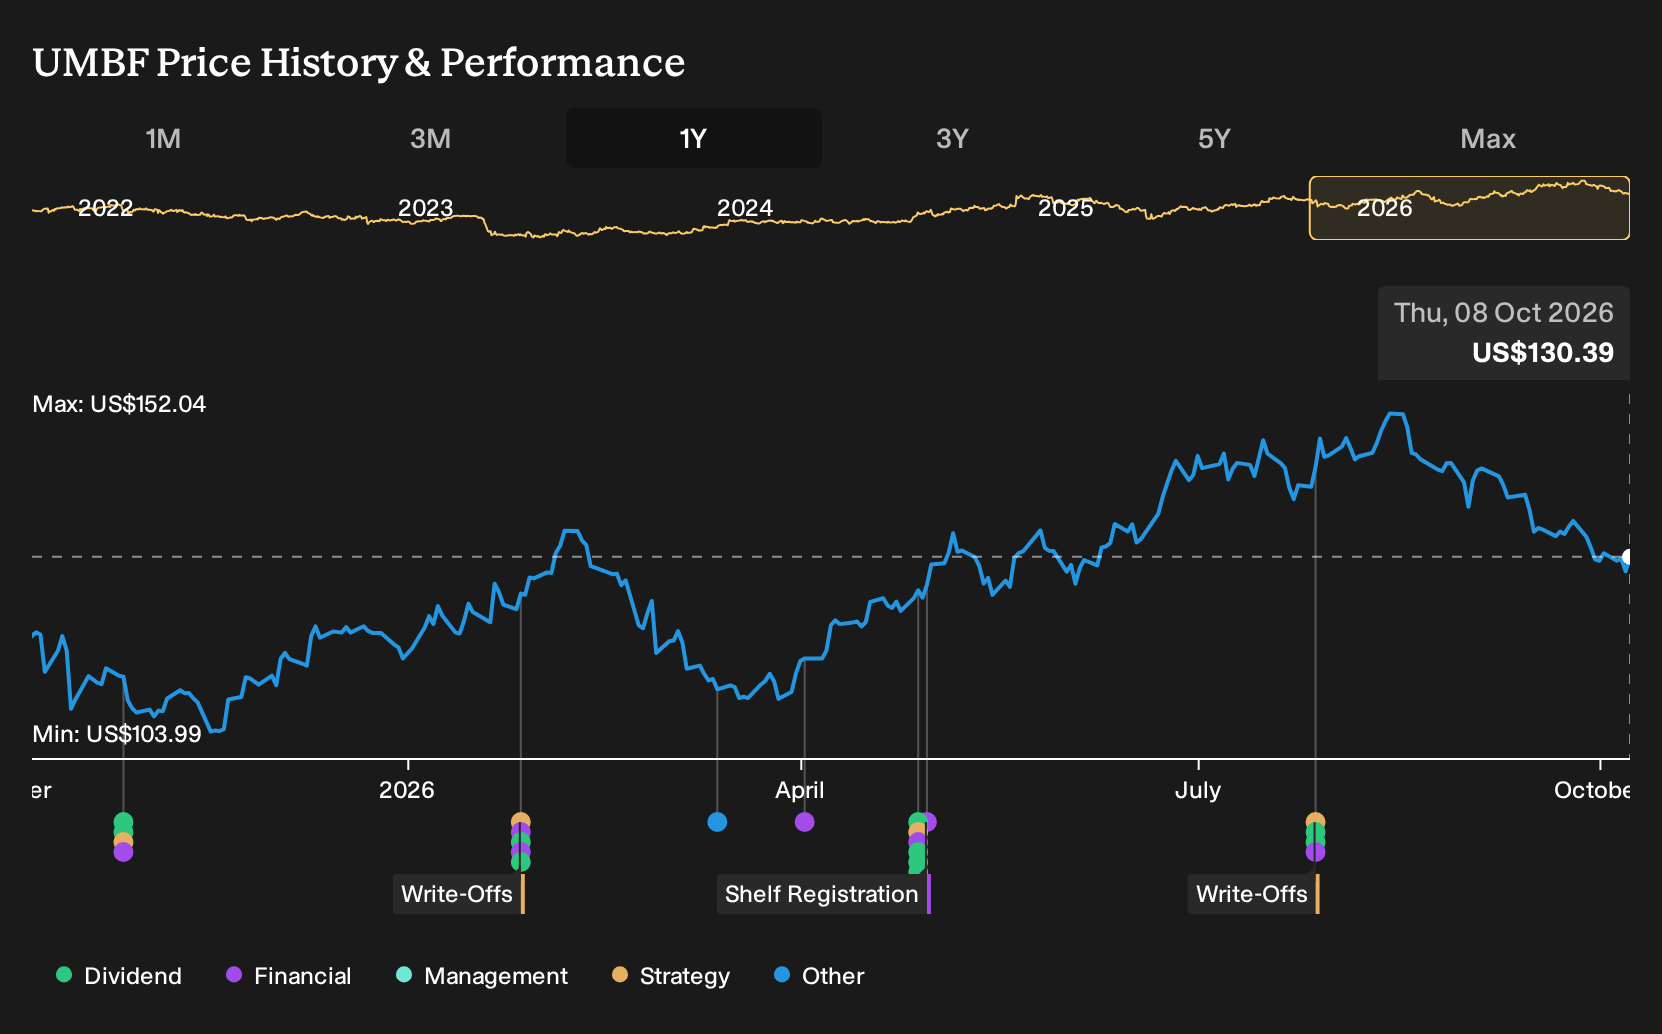
The recent pullback and oversold signals only really matter if they hint at deeper pressure on organic loan demand, fee volumes or asset quality in the next few quarters. The most immediate swing factor is execution on organic growth as accretion fades. The main operational risk is any slowdown or volatility in institutional fee flows.
The upcoming third quarter 2026 earnings release and investor call on 27 and 28 October is the key near term check in on this story. That update should clarify how much of UMB Financial’s recent net interest income still depends on purchase accounting accretion and how management is pacing capital deployment while funding loan pipelines.
This event also matters for the institutional banking narrative. With more than US$600b of assets under administration and custody feeding fee revenue, investors will be watching closely for commentary on client activity, pricing and retention. Any signs of softer flows or pressure on fees would cut against the value case more than the recent share price pullback itself.
What UMB Financial's Consensus Forecasts Are Pricing In
UMB Financial's analyst narrative points to revenues of US$3.5b and earnings of US$1.2b by 2029. That outlook assumes yearly revenue growth of 7.9% and an earnings increase of about US$283m from US$917.3m today.
Uncover why UMB Financial's fair value indicates a 28% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$166.56 and US$230.20, which points to a wide band of outcomes around UMB Financial. That spread meets real business questions. Purchase accounting accretion will taper, so investors may need to weigh loan momentum and fee durability before relying on any single view.
Explore another UMB Financial fair value estimate, including an estimate that suggests as much as 77% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A useful starting point for your UMB Financial research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for UMB Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review UMB Financial's overall financial profile at a glance.
Looking For More Investment Ideas Beyond UMB Financial?
If the UMB Financial story has you thinking about how to balance value, income and resilience, it can help to line it up against a wider field of opportunities using the Simply Wall St Screener.
- For investors hunting for mispriced quality, compare UMB Financial with a broader bench of candidates by reviewing the 27 high quality undervalued stocks that share strong fundamentals with room for sentiment to catch up.
- If capital preservation and steadier profiles are the priority, focus on companies that aim to keep risk in check by scanning the 31 resilient stocks with low risk scores and see which businesses fit your comfort zone.
- When the goal is to pair solid operations with cleaner balance sheets, widen your watchlist using the list of solid balance sheet and fundamentals (25 results) and spot firms that keep leverage in tighter control.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com