
Are Catastrophe Losses Altering The Investment Case For Intact Financial Stock (TSX:IFC)?
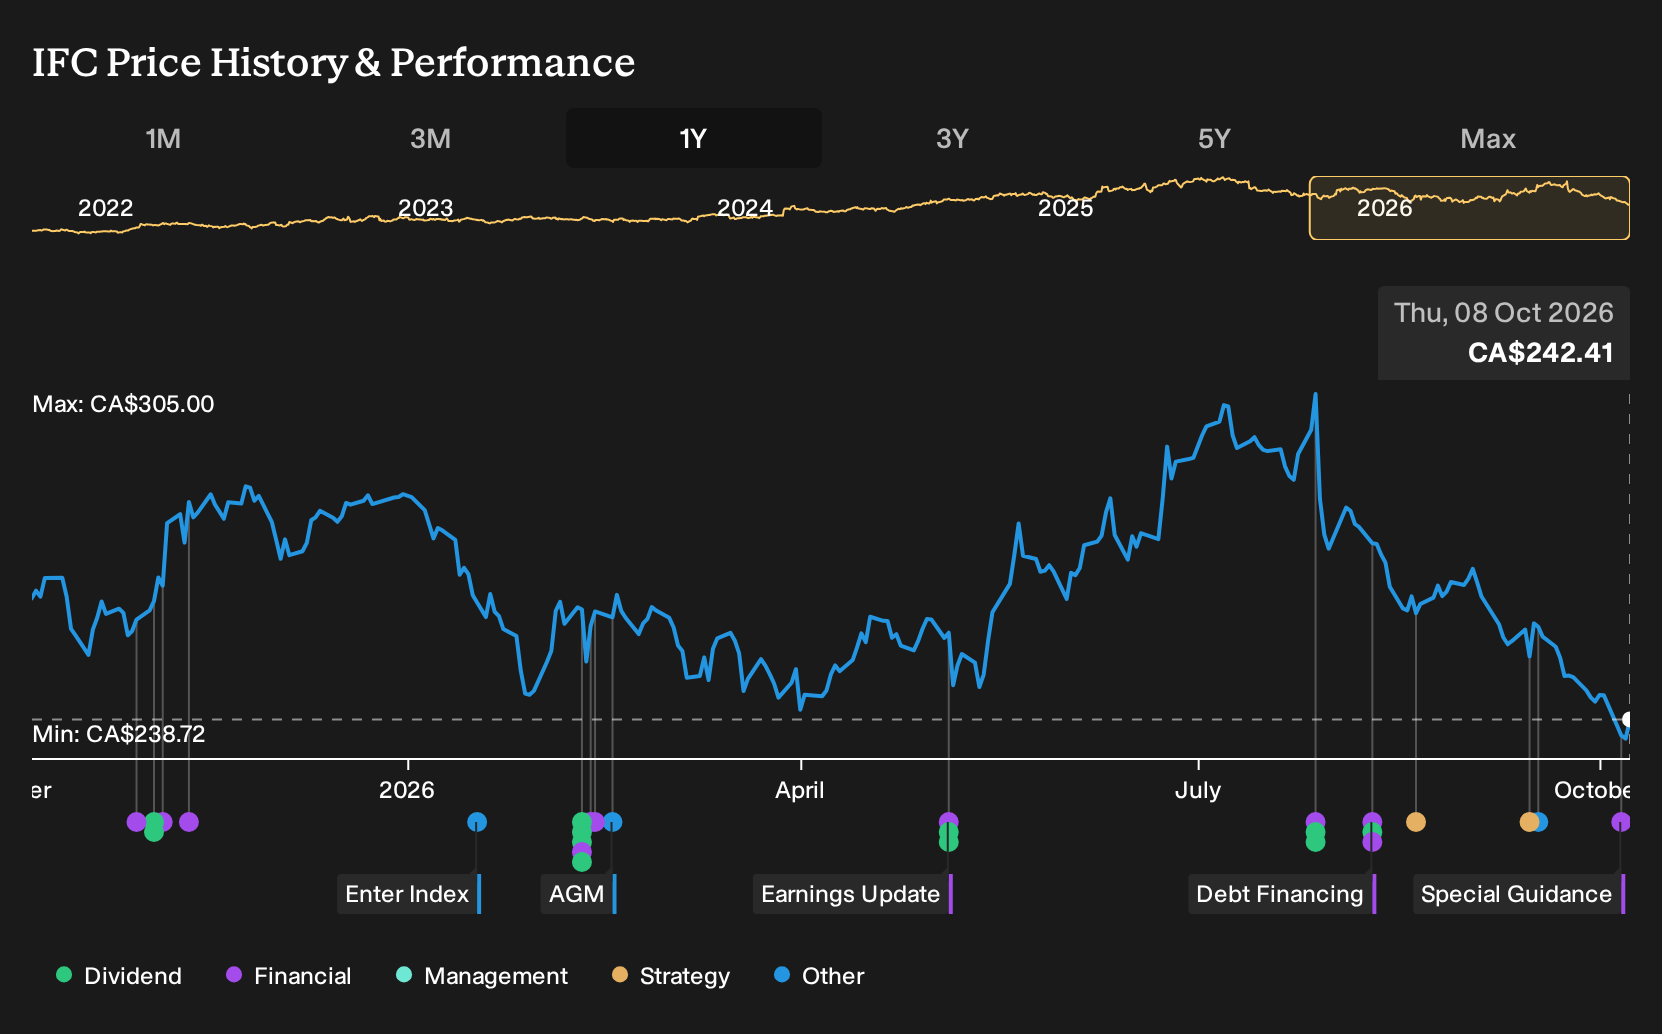
- Intact Financial reported estimated catastrophe losses of about $660 million pre tax for Q3 2026, net of reinsurance, with storms and wildfires affecting personal property and commercial lines in Canada.
- The company is pairing this heavy catastrophe burden with a prevention push, including its national Keep it Intact program and Jiffy app partnership, aimed at reducing future weather related claims through homeowner preparedness.
- We will now assess how Intact Financial's investment narrative is affected by these sizable catastrophe losses and related weather risk.
Intact Financial Investment Narrative Recap
To own Intact Financial, you need to be comfortable with a property and casualty insurer that leans on pricing discipline, prevention programs and diversification across Canada, the U.S. and UK&I, while accepting periodic weather heavy quarters. The Q3 2026 guidance for about CA$660 million of catastrophe losses puts short term pressure on underwriting results but does not automatically change that broader thesis.
The near term swing factor is how quickly management can reflect this higher catastrophe load in pricing, terms and risk selection, especially in personal property and commercial Canada. The biggest operational risk remains a pattern of elevated weather events that keeps catastrophe losses above guidance. That would challenge margins and any effort to stabilise earnings that analysts already expect to soften.
The winter preparedness push, including the Keep it Intact program and Jiffy app partnership, is the announcement that ties most directly to the recent catastrophe update. Intact Financial is linking customer education, maintenance tools and easier access to contractors to the same weather trends that drove the CA$660 million in estimated Q3 catastrophe costs.
For you as a shareholder, the interest is straightforward. If prevention efforts help reduce claim frequency or severity over time, that could support the underwriting side of the story. That story already includes technology, data and international expansion as catalysts. The risk is that prevention uptake or measurable impact on losses is slower than hoped, while severe weather and competitive pressures in commercial lines and UK&I keep underwriting conditions tight.
Intact Financial's current analyst narrative points to revenue of CA$24.1b and earnings of CA$2.8b by 2029, based on an assumed yearly revenue decline of 2.9%, with consensus calling for earnings to fall by CA$0.5b from CA$3.3b today.
Uncover why Intact Financial's fair value indicates a 32% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community currently offers 2 fair value views on Intact Financial, ranging from CA$320.54 to CA$444.17 per share, which shows how far apart private investors can be. Set that against rising catastrophe losses and climate risk, and you get a clear reason to test several alternative viewpoints.
Explore another Intact Financial fair value estimate, including one that suggests it could be worth just CA$320.54!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Intact Financial research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Intact Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Intact Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Intact Financial?
Once the Intact Financial story is clear in your mind, it often helps to compare it with other opportunities that share some of the same risk and reward patterns. The Simply Wall St Screener can help you quickly filter for different types of businesses that might fit your approach to weather risk, income needs or balance sheet strength.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (7 results) that can handle shocks without leaning too heavily on leverage.
- If value is your main focus, check out a 7 high quality undervalued stocks that combine quality fundamentals with prices that sit below fair value estimates.
- Income centred investors can concentrate on consistency and yield by reviewing a 3 dividend fortresses that may suit a longer term, cash flow focused approach.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com