
Bloom Energy (BE) Stock May Be 25% Undervalued As Fuel Cell Project Timing Clouds The Story
Bloom Energy has delivered a very large 3 year share price gain, which puts a sharp spotlight on a basic question for investors who care about fundamentals. Do the cash flows this business can produce really line up with where the stock now trades?
- The share price has climbed about 23x over the past 3 years, so a lot now rests on whether the cash the business can generate supports that kind of move.
- Recent headlines around the Philadelphia 76ers jersey patch deal and the large Oracle fuel cell project highlight how brand reach and project timing can influence expectations for future cash generation and the pace at which those inflows arrive.
- What if you looked at Bloom Energy through its sales instead? See why Bloom Energy's 25.8x P/S tells a different valuation story.
The issue now is whether Bloom Energy's current market value can be explained by the cash flows investors expect it to produce in the years ahead.
Alongside Bloom Energy's rapid share price move and headline deals, some investors may want a wider watchlist built on similar themes of energy, infrastructure and cash generation potential, using the 43 power grid technology and infrastructure stocks.
Does Bloom Energy Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on the cash Bloom Energy can return to shareholders over time. Latest twelve month free cash flow sits at about $619 million, and the projections assume that this figure grows rather than shrinks over the next decade, with forecast yearly cash flows moving into the multi billion dollar range by the early 2030s.
Those rising cash flow estimates make the DCF outcome meaningfully higher than the current share price of $272.82. The large Oracle fuel cell project facing timing risk helps explain why the market might still hesitate to fully reflect those projected cash flows in the price, even with that DCF gap in place. Find out what Bloom Energy could be worth using our Discounted Cash Flow (DCF) estimate.
The Bloom Energy Narrative: What Would Justify Today's Price?
Bloom Energy's valuation question positions Simply Wall St Narratives as the bridge between the current share price and the cash flow assumptions that might justify something higher or lower. Narratives spell out the implied paths for growth, profitability and earnings that could support very different outcomes from here. Rather than leaning on a single multiple or model result, each one lays out its own set of inputs so you can compare those expectations with the actual numbers as they arrive, all housed on Simply Wall St's Community page.
Community views on Bloom Energy are split between a long runway for its technology and concern that competition and capital needs still bite hard.
Bull case: 29% undervalued
"The Bloom Energy story is still early days. Wall Street cannot seem to comprehend that so many areas for their growth are largely untapped…"
Discover why this Narrative puts Bloom Energy at 29% undervalued.
Bear case: 103% overvalued
"Bloom's business remains capital intensive, with continued need for large scale manufacturing expansion funded through convertible debt or future equity…"
Explore why this Narrative puts Bloom Energy at 103% overvalued.
One more unanswered question on Bloom Energy
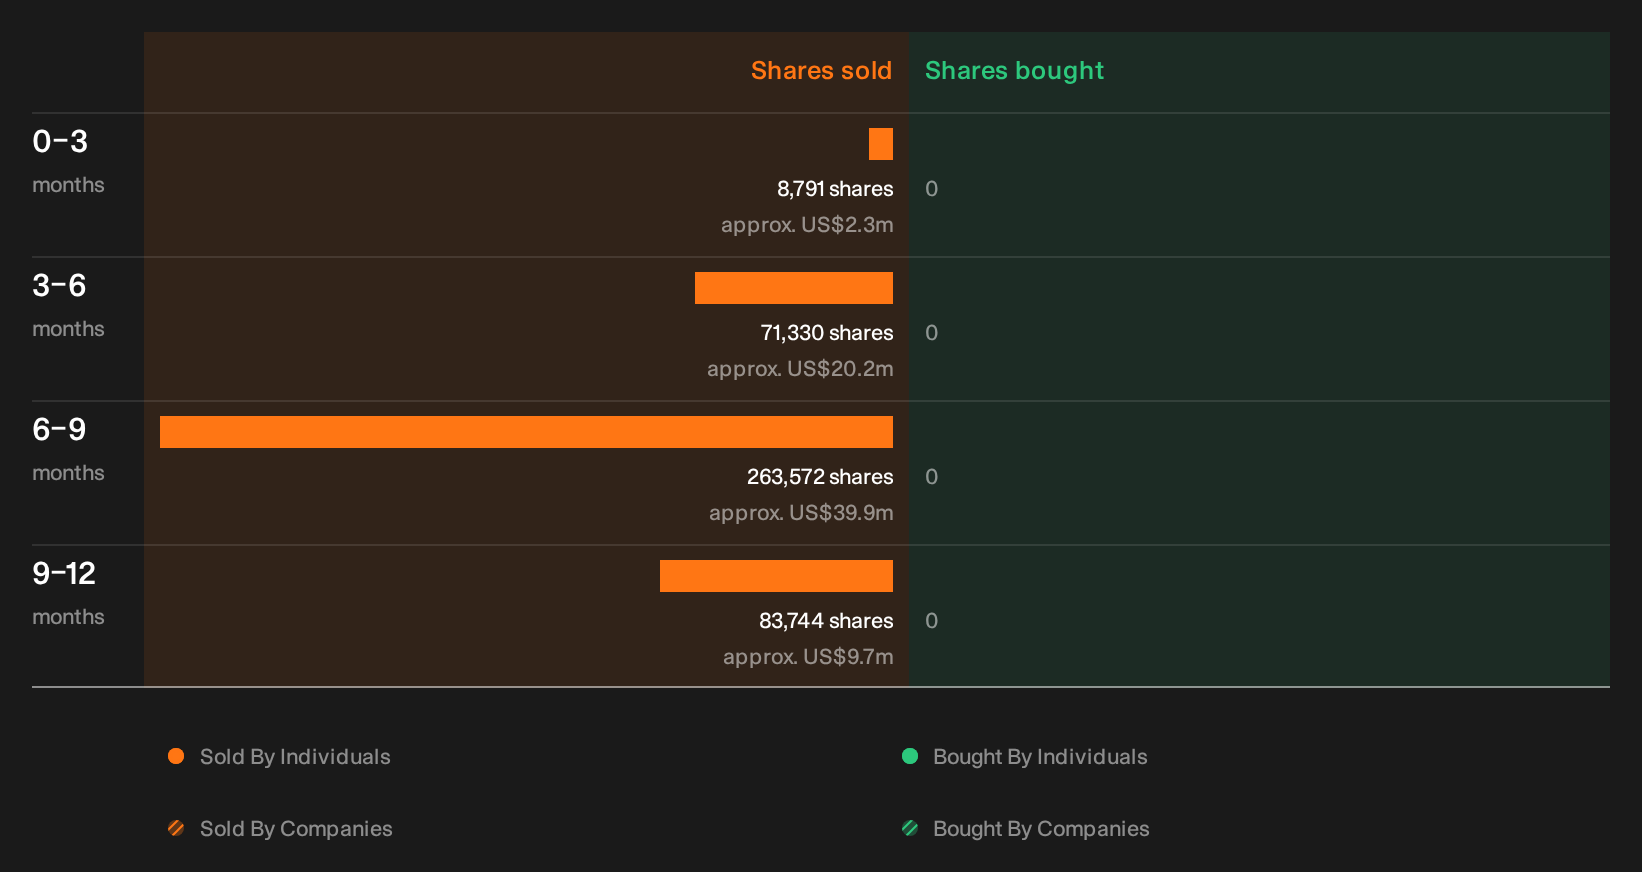
There is one angle on Bloom Energy that the valuation work does not cover, which is the pattern of recent insider share sales and what those transactions might signal to you as a shareholder. See the recent insider selling flagged for Bloom Energy.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com