
China Everbright Environment Group (SEHK:257) Pulls Back As Investors Ask If Value Is Finally Opening Up
Recent Share Performance and Business Scale
China Everbright Environment Group (SEHK:257) has seen mixed share performance recently, with the price up about 2% over the past day but down roughly 9% over the past month and 2% over the past 3 months.
The stock last closed at HK$4.58, giving the environmental services provider a market value of about HK$28.1b. That size reflects a broad portfolio across waste-to-energy, water treatment, and greentech operations.
Over the past year, the total return is about 3.5%, while the year-to-date performance is down roughly 5%. The longer 3-year and 5-year total return figures are positive, which may interest investors comparing China Everbright Environment Group to other Hong Kong listed infrastructure and utility-like businesses.
The group reported revenue of HK$27,397.898m and net income of HK$4,149.648m, with annual revenue growth of about 2.3% and net income growth around 3.9%. Those figures give readers a sense of the current earnings base behind the share price moves.
In the short term, the share price has slipped over recent weeks, while the longer term total shareholder return has remained positive. This indicates that momentum for China Everbright Environment Group has been fading rather than building.
The recent 1 month share price return of about 9% lower, together with a modestly positive 1 year total shareholder return of about 3.5%, suggests investors are reassessing near term risks even though the longer record remains ahead of where it started.
Compare China Everbright Environment Group with a curated list of solid balance sheet and fundamentals (206 results) that could appeal to investors who are interested in utility-like cash flows and environmental infrastructure exposure.
Given China Everbright Environment Group’s recent pullback but still positive multi year return record, the real tension is simple: Do you step in after this cooling period, or hold out for an even cheaper entry before the valuation work starts?
Preferred Price-to-Earnings of 6.8x: Is it justified for China Everbright Environment Group?
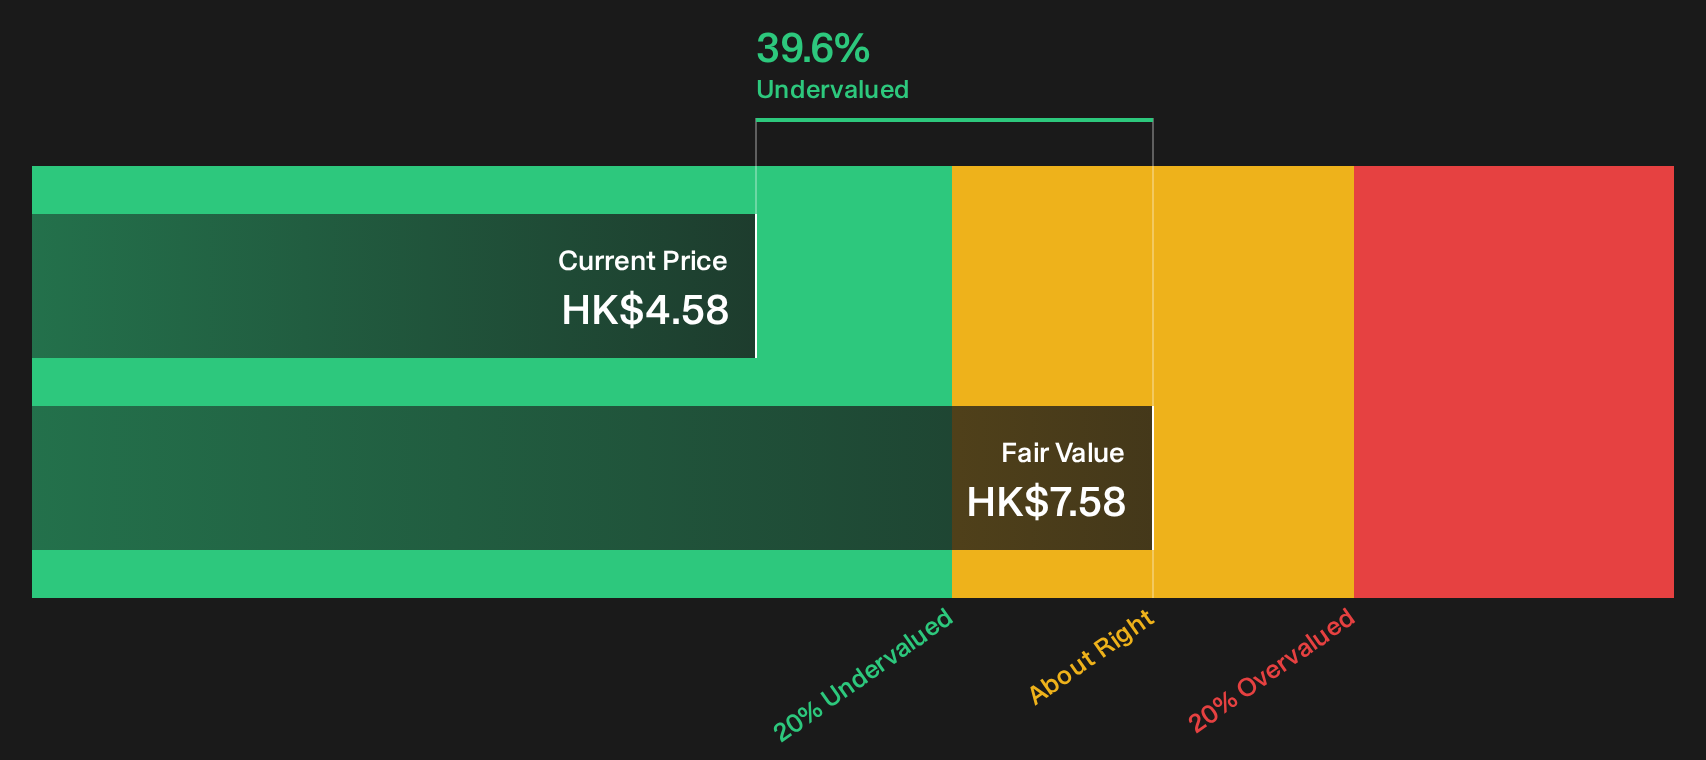
China Everbright Environment Group trades on a P/E of 6.8x, which is paired with an internal fair value estimate suggesting the shares are trading at a 39.6% discount to HK$7.58 based on the SWS DCF model. The last close sits at HK$4.58.
The P/E ratio compares what investors are paying for each dollar of current earnings. For a capital intensive environmental services operator like China Everbright Environment Group, this metric helps you see how the market is weighing a steady earnings base against relatively moderate forecast growth.
A 6.8x P/E is materially lower than both the internal fair P/E estimate of 8x and the peer average of 18.6x. That combination suggests the market is pricing the stock well below the level its earnings profile could justify if sentiment moved closer to that fair ratio. The fact that earnings grew 32.6% over the past year, with net profit margin at 15.1% compared with 10.8% a year ago, adds further context to that gap.
Compared with the wider Hong Kong Commercial Services group, where the average P/E sits around 10x, China Everbright Environment Group trades on a meaningfully lower multiple. The stock is also at a discount to the peer subset on 18.6x, reinforcing the idea that investors are applying a sizeable valuation gap to the current profit stream, even though internal fair value work points to a higher P/E level that the market could move toward.
Explore the SWS fair ratio for China Everbright Environment Group.
Result: Price-to-Earnings of 6.8x (UNDERVALUED)
Still, China Everbright Environment Group faces pressure if recent share price weakness continues, or if its capital intensive projects experience delayed cash flows or policy setbacks.
Find out about the key risks to this China Everbright Environment Group narrative.
Another View on China Everbright Environment Group’s Value
Price hints at value, but cash flows tell a different story. The SWS DCF model estimates China Everbright Environment Group’s future cash flow value at HK$7.58 per share, compared with the current HK$4.58. That gap points to an undervalued stock. The key question is how much trust you place in long range forecasts.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Everbright Environment Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on China Everbright Environment Group can make the story feel messy, which is exactly why checking the underlying data yourself matters. Act while the numbers and narrative are fresh in mind, and weigh both sides of the thesis with the help of 5 key rewards and 2 important warning signs
Looking for more investment ideas beyond China Everbright Environment Group?
If China Everbright Environment Group has sharpened your focus on value and resilience, do not stop here. The next move you make across the market could matter more than this single decision.
- Target sturdier portfolios by scanning a 225 resilient stocks with low risk scores that filters for resilience when conditions turn harder.
- Seek stronger income potential through a 224 dividend fortresses that highlights companies pairing higher yields with solid fundamentals.
- Hunt for future leaders using a 619 high quality undiscovered gems that surfaces under followed businesses before wider attention arrives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com