
Does Trade Secret Lawsuit Change The Bull Case For Beam Therapeutics Stock?
- Beam Therapeutics has filed a lawsuit claiming a former employee and rival firm YolTech misused trade secrets tied to its alpha-1 antitrypsin deficiency base-editing program and breached contractual obligations. The filing seeks injunctions, compensation, and damages.
- The dispute centers on ownership and control of core base-editing know-how, which is closely connected to Beam Therapeutics' efforts to commercialize precision genetic medicines in liver disease.
- We will look at how Beam Therapeutics' investment narrative is affected by the alleged trade secret misuse tied to its AATD program.
Scan beyond Beam Therapeutics and evaluate other gene editing and biotech players that are under legal, regulatory, or competitive pressure using our curated list of 31 resilient stocks with low risk scores.
Beam Therapeutics Investment Narrative Recap
For a shareholder to stick with Beam Therapeutics, the core belief is that its base editing platform in hematology and liver disease can turn current R&D into future therapies with real commercial value. The lawsuit over alleged alpha 1 antitrypsin deficiency secrets looks more like an attempt to protect that toolkit than a near term hit to operations.
For now, the nearest operational swing factors still sit in the clinic and on the cash runway. BEAM 101 safety and busulfan conditioning risks, plus the need to keep funding early stage trials, remain the biggest near term variables. The YolTech case does not change those core pressures in a material way yet.
With no fresh clinical data or partnership announcements tied directly to the lawsuit, the most relevant reference point is still Beam Therapeutics' stated focus on two franchises: hematology and liver genetic disease. BEAM 101 for sickle cell and BEAM 302 for alpha 1 antitrypsin deficiency remain central to that plan and frame how serious the firm is about defending its IP.
For catalysts, investors are still watching progress in the BEACON trial, advancement of BEAM 302 and the ESCAPE platform more than any courtroom timetable. The legal action adds an extra execution risk around IP, but the main swing factors for the Beam Therapeutics story continue to be trial outcomes, safety data and the ability to fund ongoing work.
Beam Therapeutics' current narrative points to forecast revenues of US$207.3 million and expected earnings of US$39.3 million by 2029. That path assumes revenue grows at roughly 8.1% per year and earnings move from a loss of US$66.0 million today to a profit of US$39.3 million, a swing of about US$105.3 million.
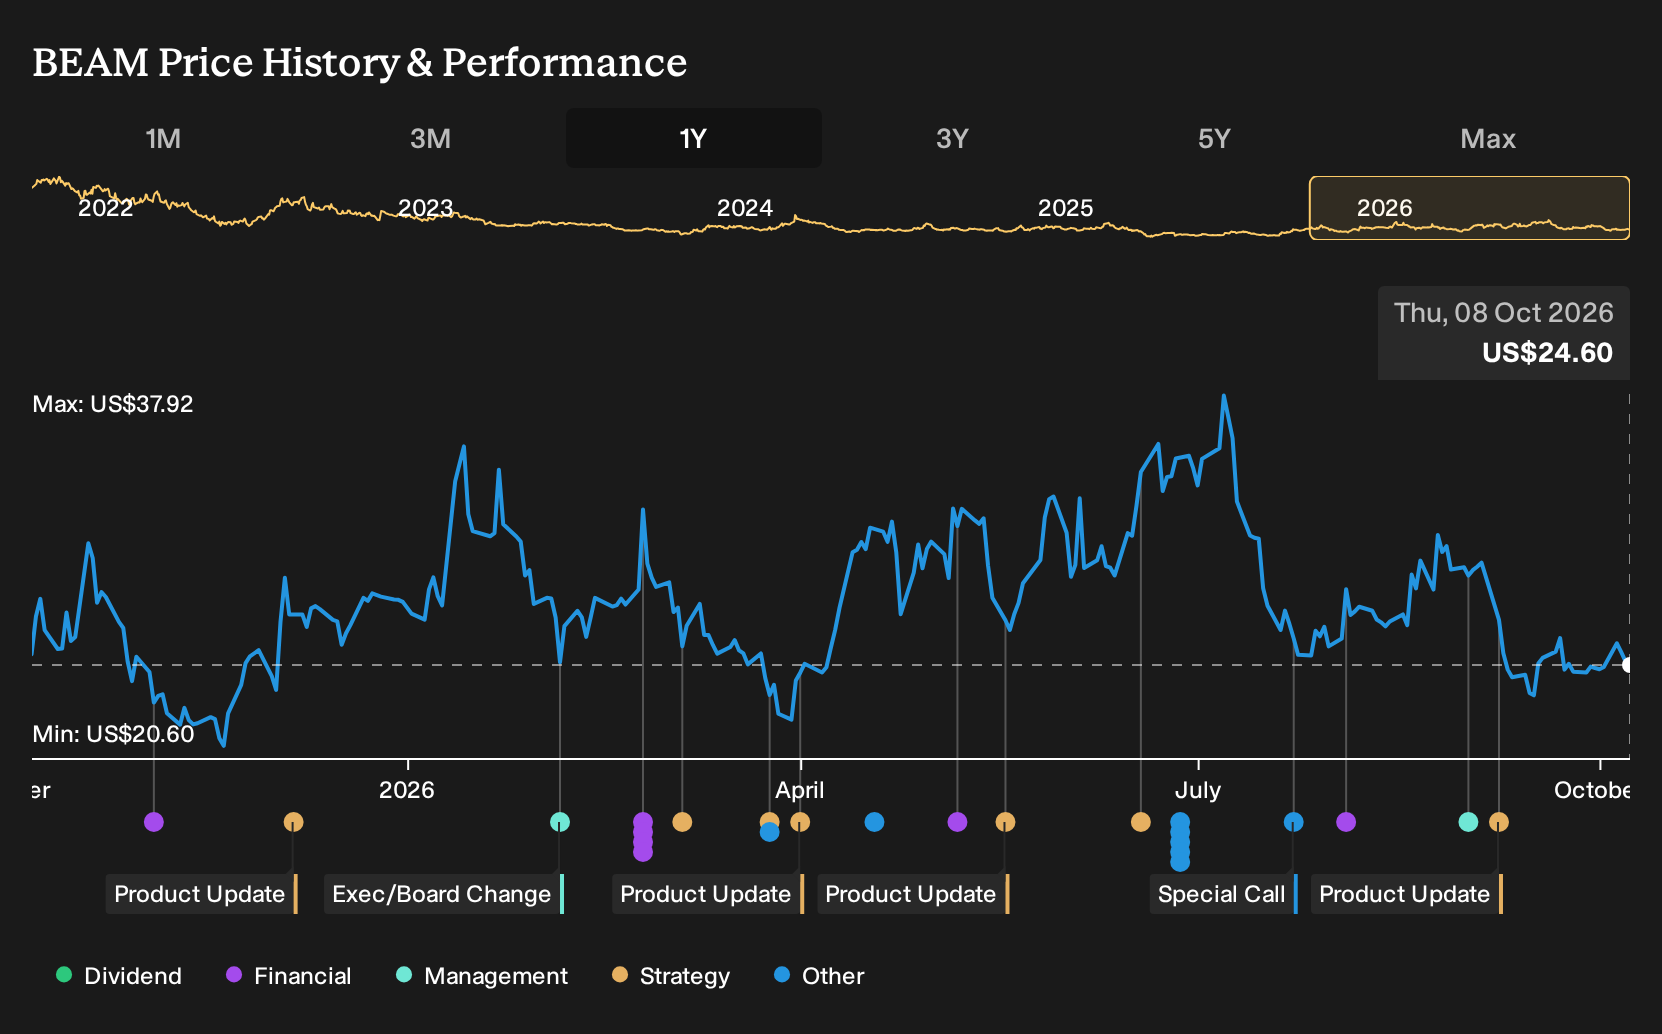
Uncover why Beam Therapeutics' fair value indicates a 108% potential upside to its current price. This gap could close faster than you expect.
Exploring Other Perspectives
One alternate view on Beam Therapeutics leans hard into commercial risk. The most pessimistic analysts already assumed revenue of just US$34.5 million and earnings of US$6.5 million by 2029, with a very high implied P/E of 508.4x. You can see how opinions differ widely, and this lawsuit could push those stories to shift again.
Explore 5 other Beam Therapeutics fair value estimates, including one that suggests as much as 49% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Beam Therapeutics research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Beam Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Beam Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Beam Therapeutics?
If the Beam Therapeutics story has you thinking about position sizing, risk and where to put fresh capital to work, it can help to compare it with other opportunities that better match your own comfort level. The Simply Wall St Screener lets you filter the market quickly so you can focus on companies that line up with your income needs, risk tolerance and time horizon.
- If capital protection and balance sheet strength sit at the top of your checklist, start with this curated list of solid balance sheet and fundamentals (25 results) that can help you focus on businesses with stronger financial footing.
- For investors hunting for mispriced opportunities, you can scan a targeted universe of potential bargains through our hand picked 26 high quality undervalued stocks and see which ones deserve a closer look.
- If you want cash returns in your portfolio today rather than only potential gains down the road, use the income focused 8 dividend fortresses to find companies offering higher yields with an emphasis on resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com