
Is Standex International (SXI) Still Below Fair Value As Grid Expansion Plans Build?
Standex International (SXI) has drawn fresh attention after its recent share move, with the stock closing at US$281.06. Investors now appear focused on how current results align with its broader multi segment industrial profile.
Recent trading paints a mixed picture for Standex International, with the share price slipping 2.49% in the last session and easing 10.94% over 90 days. The stock has still shown a 3.47% 1 month share price return and a 24.99% year to date share price gain, while long term momentum remains intact with a 1 year total shareholder return of 28.37% and a 5 year total shareholder return of 176.50%.
Scan how Standex International compares with other industrials showing strong price trends and fundamentals in our curated 26 high quality undervalued stocks.
So is Standex International’s sharp run this year a clear indication of a stronger multi segment business, or just a sentiment swing that pushed the price too far? The valuation numbers start to answer that.
Most Popular Narrative: 16.9% Undervalued
Against the last close at $281.06, the most followed narrative places Standex International’s fair value at $338.40, implying material upside based on its grid and aerospace ambitions and the earnings power tied to them.
The multi region grid capacity program spanning India, Texas, Mexico, and a new Croatia facility, which is planned to add incremental annual capacity of roughly US$40 million from productivity and automation, about US$75 million from Croatia, about US$25 million from Mexico, more than US$60 million from Texas, and around US$90 million to US$95 million from India, provides a clear path for higher future grid revenues and operating leverage.
See why 1 investors see Standex International as 17% undervalued.
Result: Fair Value of $338.40 (UNDERVALUED)
Still, the Standex International story could change quickly if organic growth in Electronics and Aerospace & Defense slows, or if new grid investments earn weaker returns.
Find out about the key risks to this Standex International narrative.
Another View: Standex International On Earnings Multiples
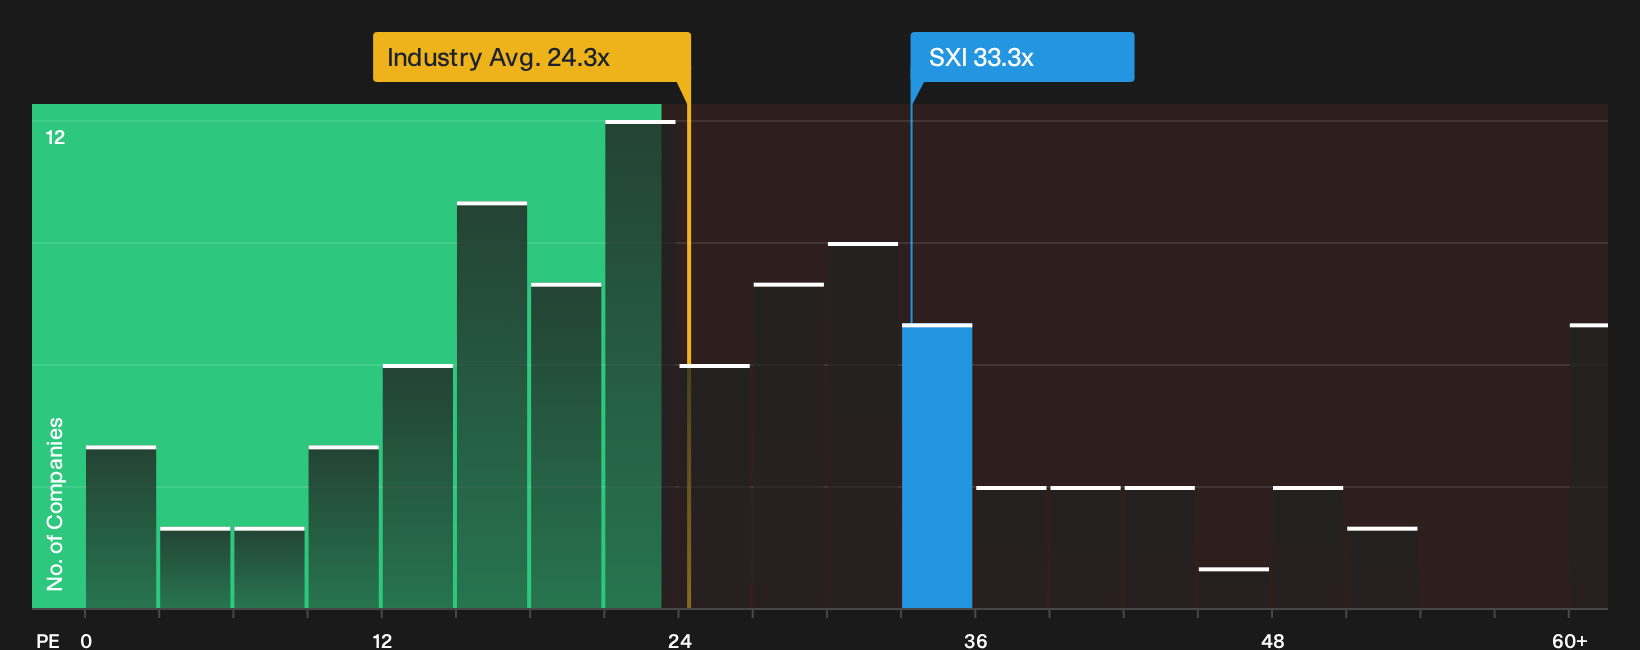
The narrative fair value of $338.40 presents Standex International as undervalued. The earnings multiple tells a tougher story. At a P/E of 33.3x, the stock trades well above both its peer average of 20.5x and the US Machinery industry at 25x, and even above an estimated fair ratio of 22.4x. This points to meaningful valuation risk if sentiment cools. So which lens do you trust more when expectations are this rich?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Standex International’s valuation and expectations make this a judgment call, so move quickly to review the underlying data and weigh both the downside flags and upside drivers highlighted in the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Standex International?
If Standex International has your attention, do not stop here. Use the screener to spot other opportunities before they move out of reach.
- Target dependable income by reviewing companies that show up in the 8 dividend fortresses and focus on robust yields with staying power.
- Hunt for quality at a sensible price through the 26 high quality undervalued stocks and spot businesses where fundamentals and valuation still line up.
- Prioritize resilience by scanning the 31 resilient stocks with low risk scores and concentrate your research on companies with sturdier risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com