
Did Bobbi Brown Leadership Change Just Shift Estée Lauder Stock's Investment Narrative?
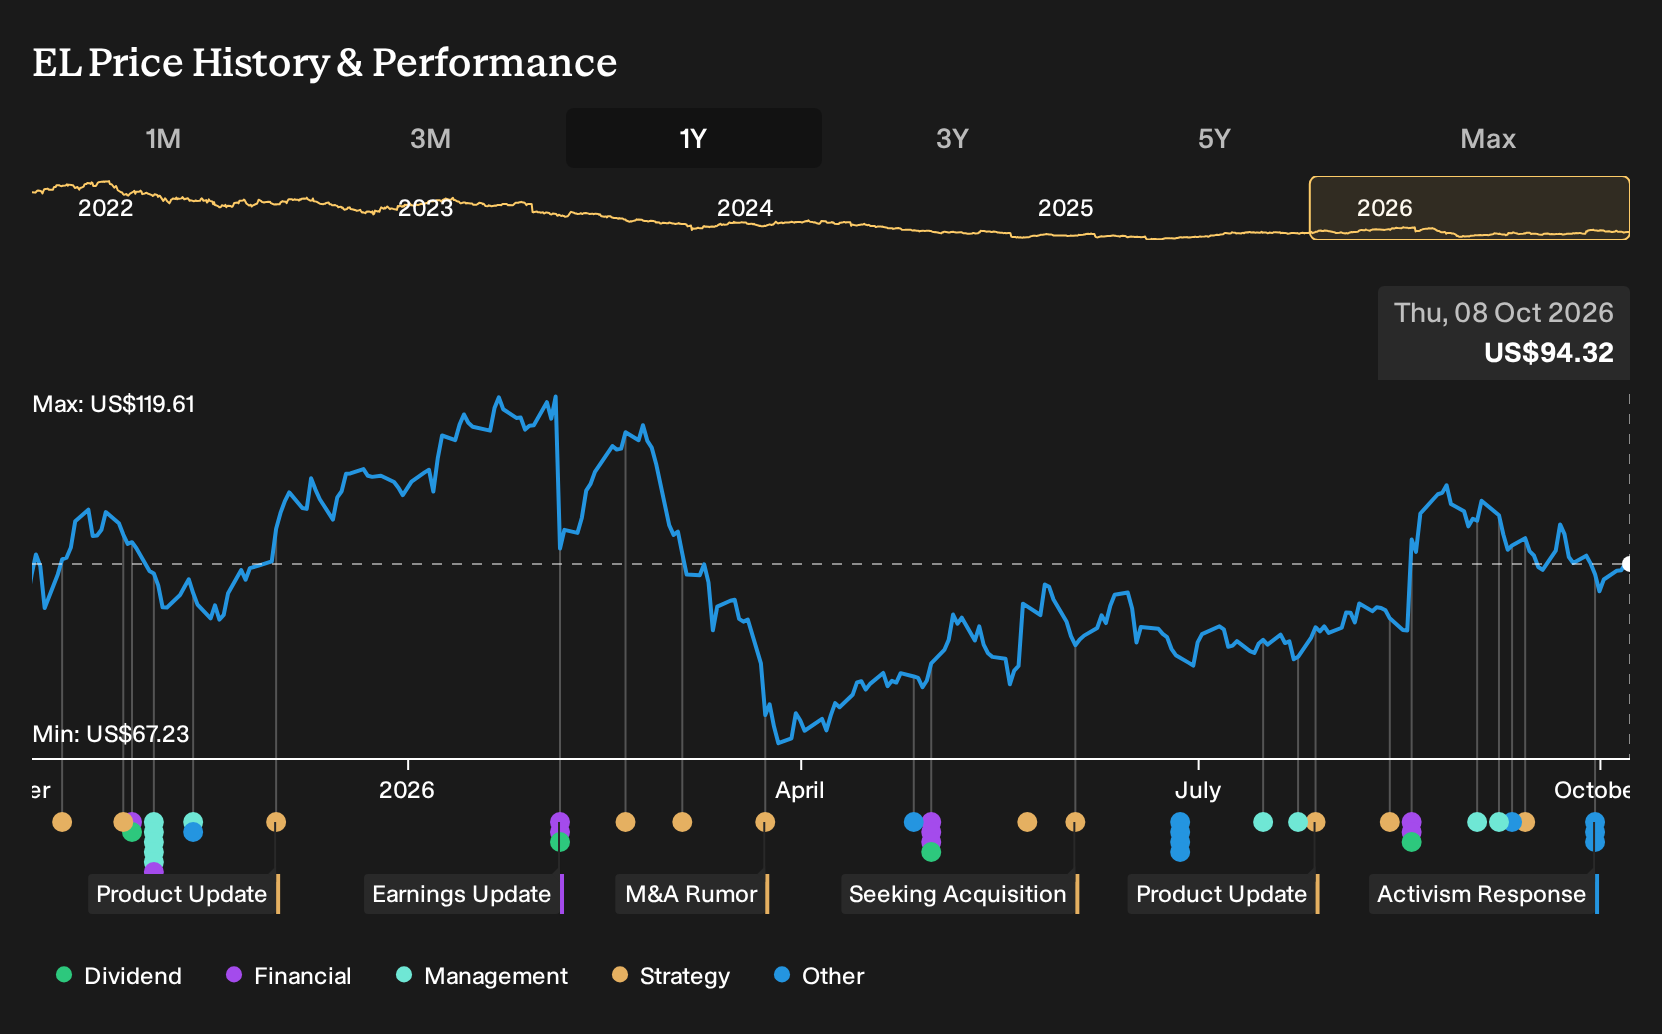
- On September 30, 2026, Estée Lauder Companies reported that Gaétane Baudry will become Senior Vice President and Global General Manager of Bobbi Brown, tasked with steering brand strategy, product pipeline, and digital expansion worldwide.
- This leadership shift places Bobbi Brown at the center of Estée Lauder Companies efforts to enhance execution, refine marketing spend, and support its broader recovery plan.
- This article examines how Estée Lauder Companies investment narrative is affected by Gaétane Baudry taking charge of Bobbi Brown's global direction.
Estée Lauder Companies Investment Narrative Recap
To own Estée Lauder Companies, you need to believe that the Profit Recovery and Growth Plan, the One ELC model, and the channel reset can keep lifting profitability without weakening brands like Bobbi Brown or La Mer. The key near term swing factor remains execution on cost cuts and productivity, alongside managing high debt and a dividend that is not well covered by current earnings.
The new proxy fight around plastic packaging reporting does not materially change that operating story in the short run. It does introduce another governance thread alongside the existing investigation into officers and directors, which could add distraction at a time when management focus on restructuring and travel retail stability already matters a lot.
The most relevant development here is the September 30 filing urging investors to vote against the Green Century proposal on plastic packaging disclosure. This is where operational priorities and sustainability expectations intersect. The proposal asks Estée Lauder Companies to quantify plastic use and assess whether efforts to reduce environmental and health impacts can be scaled up.
For you as a shareholder, the question is not who is right in the vote. It is whether ESG expectations might push the business toward packaging changes, reporting costs or product reformulation that touch margins or capital spending. Any extra complexity would land on top of margin recovery efforts, AI investments and ongoing restructuring, so progress on those catalysts becomes even more execution sensitive.
Estée Lauder Companies' consensus narrative points to revenues of US$17.1b and earnings of US$1.5b by 2029, based on analysts modelling 4.4% yearly revenue growth and an earnings increase of about US$1.3b from current earnings of US$182.0m.
Discover why Estée Lauder Companies' fair value signals a 13% potential upside from its current price, a gap that could close quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Estée Lauder Companies cash generation as the key catalyst. They were modelling revenues of about US$17.8b and earnings near US$1.7b by 2029, which is far above the baseline. You should expect those views on cash and profit potential to evolve as the plastic packaging vote and leadership changes play out.
Explore 5 other Estée Lauder Companies fair value estimates, including one that suggests as much as 55% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Estée Lauder Companies research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Estée Lauder Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Estée Lauder Companies' overall financial health at a glance.
Looking for more investment ideas beyond Estée Lauder Companies?
Once you have a view on Estée Lauder Companies, it often helps to compare that thesis with other businesses that have different risk, income, or balance sheet profiles. The Simply Wall St Screener can help you quickly surface possibilities that match what you care about most.
- If you want potential income along with your capital at risk, review steady high yielders through 8 dividend fortresses that may suit a more income focused approach.
- If preserving capital is your priority in a choppy market, scan for companies with stronger financial resilience using the 31 resilient stocks with low risk scores and see which profiles feel more comfortable.
- If you prefer to hunt for under followed ideas, compare Estée Lauder Companies with 20 high quality undiscovered gems that pair solid fundamentals with lighter analyst coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com