
How Investors Are Reacting To Novartis (SWX:NOVN) First FDA Skin Approval
- Novartis received U.S. FDA approval for Rhapsido (remibrutinib) as the first oral treatment for adults with symptomatic dermographism that is not controlled by H1 antihistamines, extending the drug’s role beyond chronic spontaneous urticaria.
- The same molecule now spans chronic hives and late stage multiple sclerosis programs, which concentrates R&D spend into a single BTK inhibitor platform across immunology and neurology.
- We will now look at how Novartis' broader remibrutinib franchise in symptomatic dermographism could reshape the long term investment narrative.
Novartis Investment Narrative Recap
For a shareholder in Novartis, the core belief is that its late stage pipeline and priority brands can offset pressure from loss of exclusivity, tougher pricing in Europe and China, and rising competition in immunology and oncology. The remibrutinib franchise now touches chronic hives and multiple sclerosis, but the SD approval itself does not radically change the near term earnings picture.
The key short term catalyst is how remibrutinib Phase III MS data are received and translated into regulatory filings and eventual usage alongside Kesimpta. The biggest risk remains pipeline underperformance or pricing pushback that weakens returns on this R&D spend, especially with high debt levels already flagged as a concern.
The most relevant recent announcement is the Phase III REMODEL 1 and 2 results in relapsing multiple sclerosis, where remibrutinib showed clinically meaningful relapse rate reduction and delay in disability progression versus teriflunomide. For anyone watching Novartis, this positions the BTK inhibitor as more than a niche allergy product and ties directly into the MS data showcase at MSToronto2026.
Operationally, that MS readout, plus 46 abstracts from the broader portfolio, gives Novartis a near term proof point on pipeline depth and execution in neuroscience. It also concentrates risk. If regulators or clinicians respond cautiously to BTK safety or efficacy, that would weigh on one of the clearer future growth drivers linked to the current remibrutinib news.
Novartis' current analyst story lines up around revenues of $66.9b and earnings of $18.4b by 2029. That profile assumes revenue growth of 5.7% per year and an earnings increase of about $5.6b from $12.8b today to the forecast consensus level.
Uncover why Novartis' fair value indicates a 7% potential upside to its current price before the window for that discount narrows.
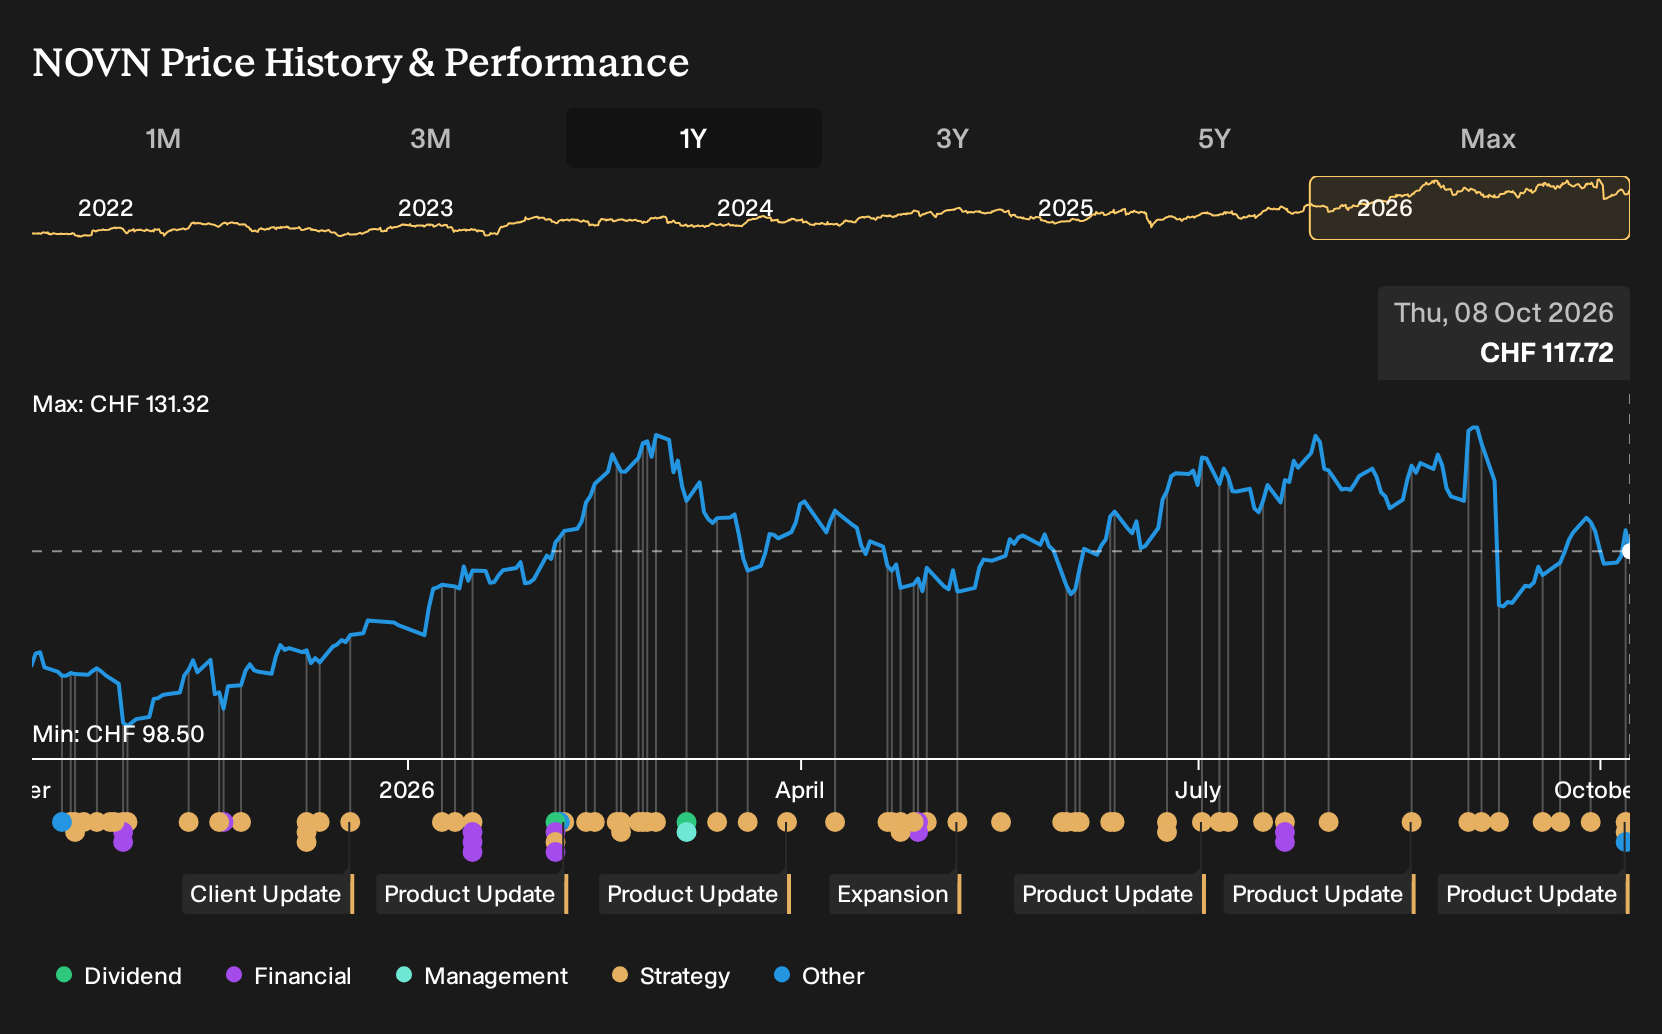
Exploring Other Perspectives
Some of the most optimistic analysts see remibrutinib itself as the key swing factor for Novartis. They were already pencilling in about $74.3b of revenue and $21.7b of earnings by 2029, compared with the $66.9b and $18.4b consensus. You can treat the new SD approval as a fresh test of which narrative starts to look more realistic.
Explore 3 other Novartis fair value estimates, including one that suggests as much as 180% potential upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Novartis research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Novartis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Novartis' overall financial health at a glance.
Looking for more ideas beyond Novartis?
Once you have a view on Novartis, it can help to compare that thesis with other opportunities that fit different goals. The Simply Wall St Screener lets you quickly filter for companies that match the mix of quality, income and risk that suits you.
- If capital preservation is front of mind, start with a basket of companies filtered for resilience and lower risk and see which ones make the cut in the 225 resilient stocks with low risk scores.
- For investors who want quality at a sensible entry point, you can scan a curated set of attractively priced businesses with solid fundamentals using the 182 high quality undervalued stocks.
- If balance sheet strength is non negotiable for you, focus on companies screened for robust finances and durable fundamentals via the list of solid balance sheet and fundamentals (206 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com