
CoreWeave (CRWV) Dropped, So What Is Driving Attention Now?
CoreWeave (CRWV) is pushing deeper into Asia after agreeing to deploy 240 MW of AI data center capacity at AdaniConneX’s Taloja campus in Navi Mumbai, with room to eventually double that footprint.
For investors trying to place this India move in context, CoreWeave’s share price has softened in the very short term, with a 1-day share price return of a 3.57% decline to US$88.45. However, the year-to-date share price return of 11.51% contrasts sharply with a 1-year total shareholder return that is down 36.81%. This suggests recent momentum has picked up, but long-term holders are still nursing sizeable paper losses as the market weighs rapid expansion, rising financing commitments and a busy run of product and partnership announcements such as Forge, the Partner Network and new customer wins.
Compare CoreWeave’s India push with other AI infrastructure plays by scanning our hand picked list of 92 AI infrastructure stocks that are also racing to secure capacity and long-term contracts.
CoreWeave now shows a significantly lower 1-year return but a double-digit gain year to date along with a newly announced multibillion India build. Is most of the easy upside already behind the stock, or is it not yet fully priced in?
Most Popular Narrative: 26% Overvalued
CoreWeave last closed at $88.45, while the most followed valuation narrative pegs fair value at $70. That gap frames the India expansion as a higher stakes move, because critics see a lot of optimism embedded in the current price.
There is a concerning "Capex Treadmill" here. Every dollar of operational cash flow must be recycled immediately into the next generation of NVDA GPUs and optical networking to remain competitive. For long-term holders, this creates a scenario where GAAP profits may exist, but distributable cash flow remains elusive as the company is forced to constantly outrun hardware aging.
See why 51 investors see CoreWeave as 26% overvalued.
Result: Fair Value of $70 (OVERVALUED)
Still, CoreWeave’s narrative could be challenged if its revenue growth of 40.89% stalls, or if the business continues to report a net loss of US$1,928.0 million.
Find out about the key risks to this CoreWeave narrative.
Another View On CoreWeave’s Valuation
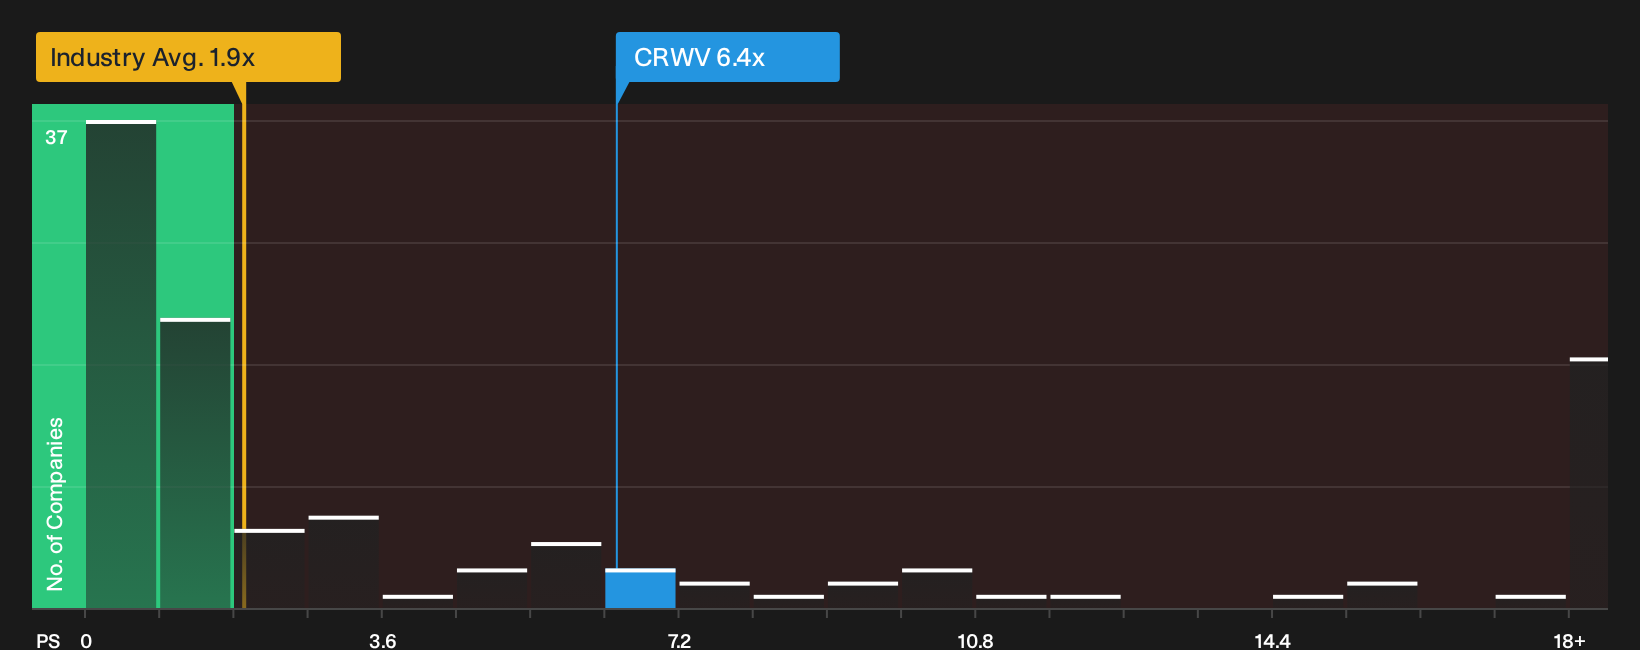
The earlier narrative concluded CoreWeave looks overvalued at $88.45 against a fair value of $70. Yet on simple P/S, the picture shifts. CRWV trades on 6.4x sales compared with peers at 11.5x and a fair ratio of 23.5x, which implies very different valuation risk. Is the crowd or the ratio more likely to be wrong?
That gap between current P/S, industry levels and the higher fair ratio points to a market that either sees serious long term risks or has not fully re-rated the stock. Investors need to decide which interpretation fits their own thesis before acting. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted about CoreWeave after all of that, and wondering how much risk and reward is really on the table. Move quickly and stress test the thesis against 1 key reward and 2 important warning signs.
Looking for more CoreWeave sized investment ideas?
If CoreWeave has sharpened your thinking, do not stop here. Use focused screeners to surface fresh opportunities before the crowd catches on.
- Target potential mispricing by scanning a curated 29 high quality undervalued stocks that combine strong fundamentals with more modest expectations baked into their prices.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (25 results) so you can focus on companies with financial footing that supports long term compounding.
- Hunt for under followed potential with a 20 high quality undiscovered gems and give yourself a better shot at spotting tomorrow’s stories while they are still off most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com