
How Investors May Respond To Seven & i Holdings Stock As Profit Falls
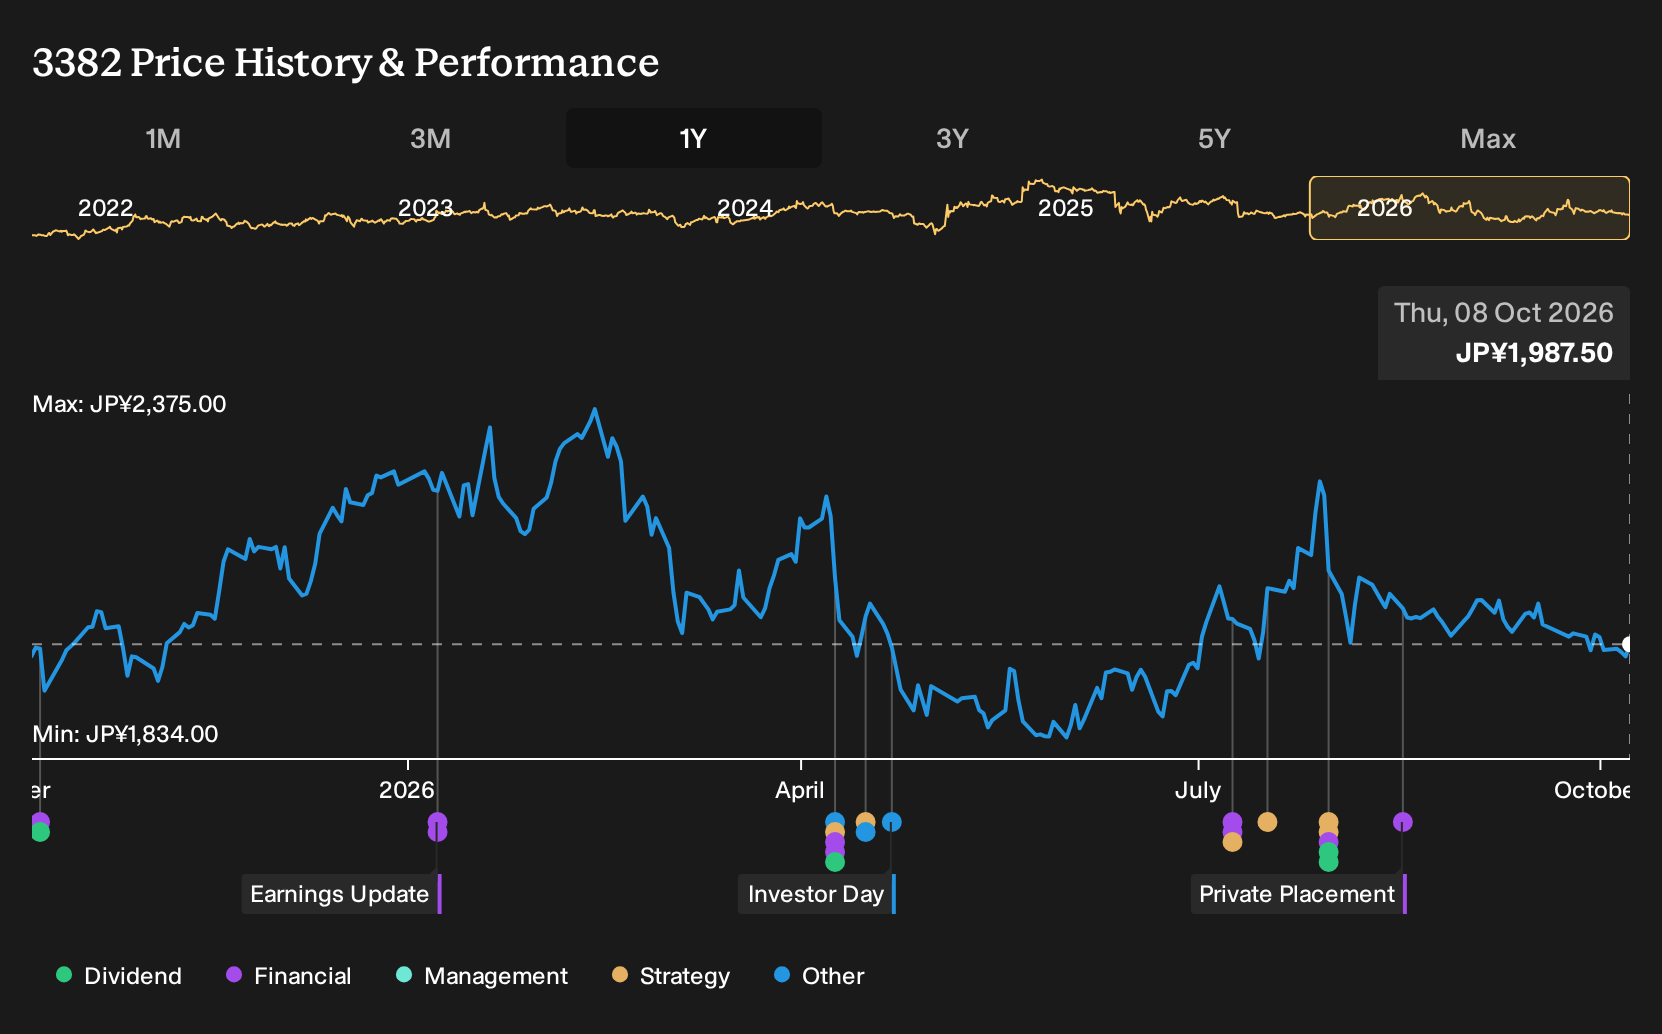
- Seven & i Holdings reported a 12% fall in second quarter net profit as domestic convenience store earnings weakened, while overseas operations and a higher interim dividend of JPY 30.00 per share contrasted with last year's JPY 25.00.
- The full year guidance for the period to February 2027, including expected revenues from operations of JPY 10,430,000 million and basic EPS of JPY 120.90, now sits alongside the closure of all 31 7 Eleven stores in India as the group rethinks its approach to that market.
- We will now assess how Seven & i Holdings' weaker domestic convenience earnings could reshape its investment narrative for long term investors.
Scan how Seven & i Holdings fits into the broader hunt for resilient cash generators by comparing it with our curated list of 14 high quality undervalued stocks.
Seven & i Holdings Investment Narrative Recap
To own Seven & i Holdings, you need to be comfortable with a thesis that the convenience platform can keep generating steady cash from a very large, mature store base while digital tools and fresh food keep shoppers engaged. The recent 12% drop in quarterly net profit and weaker Japanese convenience earnings put that idea under pressure in the near term.
The key short term swing factor is whether domestic traffic and profitability stabilise while overseas units, particularly North America, keep pulling their weight. The biggest risk is that rising SG&A and execution on reform in both Japan and abroad lag, which would make margin improvement slower and more fragile than hoped.
The new full year guidance is the clearest recent signal for investors. Seven & i Holdings now expects revenues from operations of JPY 10,430,000 million, operating profit of JPY 425,000 million and profit attributable to owners of parent of JPY 278,000 million, with basic EPS of JPY 120.90 for the year to February 2027.
That outlook sits alongside a higher interim dividend of JPY 30.00 per share, up from JPY 25.00. This underscores the importance of cash generation while structural reforms play out. For you, the guidance frames both the opportunity and the risk. Delivery against these operational targets and cost control will likely matter more than any near term narrative around the closed Indian stores.
Analysts expect Seven & i Holdings to generate ¥10,301.5b in revenue and ¥284.6b in earnings by 2029, based on an assumed 6.4% yearly increase in revenue and an earnings decline of ¥19.7b from ¥304.3b today to the 2029 consensus level.
Uncover why Seven & i Holdings' fair value indicates a 14% potential upside to its current price. This discount could close faster than many investors expect.
Exploring Other Perspectives
One contrasting angle on Seven & i Holdings puts slow digital adoption and heavier domestic reliance at the center of the risk. The most cautious analysts were pencilling in revenue of about ¥9,467.7b and earnings of roughly ¥230.2b by 2029, well below consensus. Those forecasts came before this dividend increase and updated guidance, so treat them as moving parts and explore where you agree or disagree.
Explore 2 other Seven & i Holdings fair value estimates, including one that suggests it could be worth just ¥2257.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and approach decisions independently.
- A great starting point for your Seven & i Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Seven & i Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Seven & i Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Seven & i Holdings?
If the Seven & i Holdings story has sharpened your thinking about quality, income and risk, it can help to compare it with businesses that share some of those traits. Use the Simply Wall St Screener to surface a wider watchlist that fits your own criteria instead of relying on headline ideas.
- If you want companies that combine robust cash generation with what looks like a discount, start with our collection of 14 high quality undervalued stocks.
- If resilience matters more than excitement for your portfolio, check out a 22 resilient stocks with low risk scores that score well on balance sheet strength and volatility.
- If your focus is on future potential before it is widely followed, sift through a 75 high quality undiscovered gems that pair solid fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com